



PW Consulting: Mobile Phone Loudspeaker Market to grow at 4.8% CAGR (2026-2032)

Mobile Phone Loudspeaker Market — Strategic Brief for 2026 Decision-Makers
As mobile devices continue to evolve into multi-sensory platforms, the humble loudspeaker has re-emerged as a strategic differentiator across smartphone tiers, wearables and adjacent consumer electronics. PW Consulting’s latest Mobile Phone Loudspeaker Market study (base year 2025) quantifies this resurgence and translates it into decision-grade intelligence for executives planning through 2026 and beyond. The market stood at USD 1,275 Million in 2025 and is projected to expand at a steady compound annual growth rate (CAGR) of 4.8% through our forecast horizon, reaching approximately USD 1.78 Billion by 2032. This brief outlines the strategic value of that research and highlights the operational levers leaders should consider this year.
Mobile Phone Loudspeaker Market
Why this market matters in 2026
- Audio as a product differentiator: With display, camera and battery improvements reaching maturity, audio systems—driven by loudspeaker module design, materials and acoustic integration—are a measurable way for OEMs to enhance perceived device quality without proportionate increases in BOM cost.
- Cross-industry convergence: Innovations in MEMS, balanced armature drivers and hybrid architectures are being pushed not only by smartphone OEMs but also by suppliers serving wearables, hearables and automotive infotainment, creating scale and technology spillovers.
- Supply chain volatility and resource geopolitics: Raw material dynamics (notably rare-earth based magnets and associated oxides) and changes in export policy have introduced tangible procurement risk that can materially affect lead times and cost curves for acoustic components.
- Consolidation and competitive concentration: The market’s top-tier structure means a strategic few can shape technology roadmaps and supplier economics—an important factor for partnership, sourcing and M&A strategies.
Key market backdrop — what the numbers tell us (without giving everything away)
- Scale and steady growth: The market’s macro trajectory reflects incremental unit volume growth and ongoing product premiumization that increases content value per device. The 4.8% CAGR implies reliable topline expansion but requires targeted operational improvements to protect margin.
- Concentration: The market is meaningfully concentrated at the top—our analysis shows roughly half of industry revenue is controlled by the three largest suppliers, with the top five accounting for around 60%. That concentration creates bargaining power dynamics, but also opens niches for focused specialists and regional players.
- Material and regulatory shocks: Industry-level inputs such as NdFeB magnets and didymium oxide have exhibited wide price swings and supply constraints in recent windows; for example, market-observed price ranges for high-grade sintered NdFeB magnets and a mid-2025 regulatory shift in rare-earth exports have both influenced procurement strategies across the value chain.
Immediate strategic implications for 2026 decisions
- Supply-risk mitigation must move from theoretical to tactical. Procurement teams should accelerate multi-sourcing of magnet suppliers, negotiate forward-flow contracts with indexed clauses that reflect rare-earth price volatility, and evaluate nearshoring or dual-location production for critical modules.
- Product roadmaps should prioritize modularity and acoustic adaptability. OEMs can capture higher perceived value by enabling flagship-class audio features through modular speaker assemblies and software-enabled tuning—approaches that extend across device portfolios with limited redesign cost.
- Cost-to-serve modeling is now table stakes. With component input volatility and intermittent demand shifts (e.g., smartphone production fluctuations tied to memory price shocks), finance teams must embed dynamic TCO models to evaluate design-for-cost vs. premium differentiation trade-offs for each device tier.
- M&A and partnership theses should be outcome-driven. Given the concentrated supplier base, selective bolt-on acquisitions of acoustics specialists or exclusive JV arrangements with module producers can lock in capabilities and secure volume discounts—especially where intellectual property, miniaturization expertise or proprietary materials are involved.
Supply chain and procurement playbook
- Short-term (0–12 months): Secure multi-year supply agreements for magnets and adhesives; implement buffer stock thresholds informed by scenario analysis; prioritize component qualification from suppliers with geographically diversified raw material sources.
- Medium-term (12–36 months): Invest in supplier development programs to transfer manufacturing expertise for ultra-thin and hybrid speaker units; standardize module interfaces to allow rapid supplier substitution; implement supplier scorecards that incorporate geopolitical exposure and environmental compliance.
- Long-term (36+ months): Consider strategic investments into upstream materials or joint ventures that provide preferential access to rare-earth processing; explore material science trade-offs (e.g., motor vs. balanced armature hybrids) to reduce reliance on constrained inputs without degrading perceived audio quality.
Product and technology strategy
Technical choices now translate directly into commercial outcomes. MEMS and ultra-thin dynamic drivers enable slimmer form factors, but balanced armature and hybrid solutions deliver superior mid-range clarity for certain use cases. Our research maps the implications of each architecture against manufacturability, supplier ecosystem maturity and lifetime cost—yielding prioritized technology roadmaps for OEMs and module suppliers. Critical decisions for 2026 include:
Mobile Phone Loudspeaker Market
- Determining where to place investment between incremental driver refinement versus system-level DSP tuning and software-defined acoustic profiling.
- Choosing modular architectures that decouple acoustic performance upgrades from full device redesigns—accelerating time-to-market for electro-acoustic innovations.
- Assessing trade-offs between premium audio content value and BOM constraints across device tiers; this is particularly important in light of cyclical smartphone production trends observed in early 2026.
Competitive landscape — what to watch
The ecosystem is anchored by established electro-acoustic specialists and diversified component conglomerates. Leading firms bring differentiated capabilities:
Mobile Phone Loudspeaker Market
- AAC Technologies: A global leader in miniaturized MEMS and dynamic speaker modules, with proven design wins in flagship segments and expanding exploration into automotive acoustic applications.
- GoerTek: Noted for ultra-thin speaker units and integration across premium mobile and wearable form factors; recent product launches in 2025–2026 reinforce its roadmap for ultra-compact acoustic sensors and speaker families.
- Knowles Corporation: Strong in micro-acoustic and balanced armature technologies that suit compact form factors and niche premium audio requirements.
- Regional specialists and OEM-focused suppliers (including several Japan- and China-based firms): These players often compete on scale, cost and close OEM relationships; they are relevant acquisition targets or partners for supply diversification.
Recent moves—product launches, trade show debuts and financial disclosures—signal supplier intent to broaden addressable markets and secure intellectual property positions. For example, GoerTek’s LBS Series and ultra-compact sensor announcement at CES 2026, and AAC’s automotive acoustics demonstrations at global auto shows, illustrate supplier strategies to monetize platform-level capabilities beyond smartphones.
Regulation and raw materials — risk and opportunity
- Regulatory actions affecting rare-earth exports have already impacted vendor inventories and pricing. Supply-policy changes can cause abrupt cost passthroughs and may necessitate contract renegotiations or design substitutions.
- Price volatility in inputs such as high-grade sintered NdFeB magnets (observed industry ranges) and periodic spikes in didymium oxide emphasize the value of material hedging strategies, formula-based pricing clauses and localized sourcing development.
- Environmental and compliance requirements are increasingly shaping sourcing decisions; manufacturers with transparent supply chains and lower embedded carbon footprints can command a premium with hyperscale OEM partners.
What PW Consulting’s full report delivers (practical, implementable tools)
Our full Mobile Phone Loudspeaker Market study goes beyond headline forecasts to provide a toolkit tailored for executives who must act in 2026. Highlights include:
- Scenario-based demand models that stress-test supplier capacity and material availability under multiple regulatory and cost-shock assumptions.
- Supplier scorecards and a negotiation playbook that quantify supplier risk exposure, IP position and switching cost.
- Design-for-manufacturing (DFM) and design-to-cost (DTC) templates specific to acoustic modules, including BOM sensitivity charts and TCO calculators.
- Roadmaps for technology adoption—mapping MEMS, balanced armature, dynamic and hybrid solutions to device tiers and use-case channels.
- M&A screening criteria and a list of strategic acquisition targets with rationale aligned to different buyer types (OEMs, Tier-1 module integrators, material suppliers).
- Regulatory monitoring dashboard and procurement stress-test templates that can be operationalized within sourcing teams.
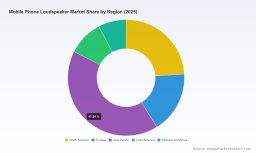
Importantly, the report contains granular segmentation, regional breakdowns and price-volume curves that are intentionally not reproduced in this brief. These data are essential for precise supply-allocation decisions and are included in the full report package.
Action checklist for executives in 2026
- Initiate a 90-day supplier stress audit focused on rare-earth exposure and single-source dependencies.
- Prioritize modular audio designs in 2026 product roadmaps to de-risk future upgrades.
- Lock in at least one second-source supplier for magnets and motor assemblies; revisit contractual terms to include material-indexed reprice clauses.
- Assess strategic inorganic options for acquiring acoustic IP or manufacturing capacity in regions that reduce geopolitical exposure.
- Embed the report’s TCO models into quarter-one budgeting cycles to reflect the latest input cost assumptions and projected volume curves.
Next steps
Given the steady market growth, concentrated supplier base and pronounced material and regulatory risks, leaders who translate insight into procurement discipline and product modularity will capture disproportionate value. PW Consulting’s comprehensive study is designed to convert market intelligence into executable strategy. For access to the full dataset, segmentation tables, supplier-by-supplier benchmarking and downloadable operational templates, please visit our report page or contact a practice lead to arrange a tailored briefing for your leadership team.
For detailed analysis of this topic, please visit the official page: Mobile Phone Loudspeaker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


