



Carbon Black Market to Reach USD 350.36 Million by 2032 — PW Consulting

Carbon Black Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise strategic preview of our latest Carbon Black Market research. This briefing distills the implications of the market’s near-term trajectory and policy environment for 2026 corporate decision-making. It is a selective synthesis – designed to demonstrate the analytical depth underpinning the full study while intentionally withholding granular segmentation detail to drive you to the full report for execution-level intelligence.
Carbon Black Market
Where the Market Stands: A macroscopic view
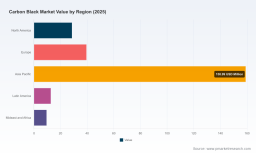
Our research uses 2025 as the base year and covers a comprehensive historical review from 2020–2025, followed by a forward-looking forecast through 2032. The market is on a steady growth path with a compound annual growth rate (CAGR) of approximately 5.0% across the 2026–2032 forecast window. To put this in context: the market exhibits resilient expansion as demand recovery in industrial end-markets combines with structural shifts toward higher-value specialty and sustainable grades.
Carbon Black Market
From a quantitative standpoint, the market size at the start of the forecast is positioned well above the mid-2020s trough and moves meaningfully higher by the early 2030s as cumulative adoption of circular and low-emission carbon black technologies accelerates. These macro numbers signal opportunity, but the commercial prize will hinge on where firms position themselves along the value chain and how they manage feedstock, regulatory and customer transitions.
Carbon Black Market
Strategic Imperatives for 2026
- Lock in feedstock resilience: Upstream exposure is the dominant near-term risk. Volatility in pyrolysis oils, naphtha and other feedstocks is already pressuring margins. The firms that secure diversified, lower-cost and lower-emission feedstock streams will hold a decisive advantage.
- Prioritize compliance-forward capex: Updated effluent and emissions rules in key jurisdictions are raising both operating and capital thresholds. Investments that simultaneously reduce environmental footprint and lower unit costs will pay out earlier in the forecast period.
- Differentiate through sustainable grades: End customers — notably tire and automotive OEMs — are increasing procurement preferences for certified low-carbon and recycled-content carbon blacks. Strategic product roadmaps that accelerate commercial specialty grades strengthen customer stickiness and pricing power.
- Monitor trade-policy leakages: Carbon-content tariffs and border adjustment mechanisms can abruptly re-route trade flows. Companies must model tariff exposure and adapt sourcing and transfer-pricing strategies accordingly.
What the Full Report Delivers (Operational, Actionable)
The full PW Consulting Carbon Black Market study is designed as an executive-playbook. Among the deliverables you will find:
- Market sizing and validated historical trends (2020–2025) plus an integrated forecast model through 2032, enabling scenario sensitivity testing under multiple feedstock, regulatory and demand-growth assumptions.
- Decision-grade go/no-go criteria for capacity investments, including payback windows under conservative and aggressive pricing scenarios.
- Supply-chain risk matrices that map raw-material sourcing concentrations, logistics vulnerabilities and regulatory exposures to CBAM and other border measures.
- Commercial playbooks for premiumization and circular offerings, with route-to-market recommendations for manufacturers and speciality-blenders.
- M&A signal dashboard: capability gaps, attractive acquiror profiles, and valuation methodologies tailored to carbon-intensive assets in an ESG-constrained world.
- Customizable slide sets and an interactive data appendix for board- and investor-level briefings.
Competitive Landscape — Who Matters and Why
The sector remains oligopolistic at the top but fragmented at the regional and specialty levels. The leading global producers continue to compete on scale, feedstock integration, product breadth and sustainability credentials. Key strategic archetypes we emphasize in the report include:
- Integrated global leaders with expansive production footprints and deep technical portfolios — entities that can shape global pricing and deliver cross-border supply assurance.
- Regional strongholds that leverage low-cost feedstocks or regulatory arbitrage to serve domestic and adjacent markets.
- Specialty challengers focused on engineered grades, low-emission processes, or novel feedstock routes (including gas-based and pyrolysis-derived carbon blacks) that command premium positioning.
Representative firms featured in our competitive analysis include global players known for scale and sustainability investments, major regional producers with cost or feedstock advantages, and technology-led entrants commercializing low-emissions production pathways. Each company is profiled on capability, geographic reach, sustainability posture, recent strategic moves and likely next plays. Notable recent corporate actions signal where competitive advantage is migrating:
- A major global producer expanded circular-carbon capabilities and closed a strategic facility acquisition to strengthen recycled-content supply chains and industrial-scale pyrolysis integration.
- Another leading supplier announced portfolio price adjustments while accelerating launches of next-generation sustainable grades to meet rising OEM sustainability specifications.
- Specialty and regional players have been investing in capacity expansions for high-performance grades that feed growing demand in advanced rubber, plastics and industrial coatings segments.
These moves collectively reinforce a two-track competitive development: incumbent scale advantages are being complemented (and sometimes challenged) by targeted investments in circular technologies and specialty grade capability.
Supply, Pricing and Regulatory Dynamics
Raw-material and energy inputs are the immediate lever affecting margins. Regionally visible price spikes in early 2026 are the product of higher upstream feedstock costs, maintenance turnarounds, and compliance-driven supply constraints — dynamics that are not transient. Importantly, regulatory changes are amplifying these effects:
- Updated effluent and emissions guidance in major markets increases the cost of non-compliant operations and raises barriers to entry for small, legacy producers.
- Trade-policy instruments that penalize carbon-intensive imports and the operationalization of border carbon adjustment frameworks are now real considerations for sourcing and pricing strategies.
- Procurement standards from tier-one OEMs increasingly tie purchasing conditions to third-party sustainability verification, altering procurement scorecards and supplier economics.
Tactically, companies must balance short-term margin defense (pricing and hedging) against longer-term structural responses (feedstock diversification, capital upgrades and certification programs). The full report provides region- and feedstock-specific scenario stress tests that quantify trade-offs across capex, opex and price elasticity — intentionally withheld in this preview to preserve the commercial value of the detailed model.
Scenarios and Recommended Playbooks
We present three pragmatic scenarios in the report — Conservative, Transition and Accelerated Decarbonization — each accompanied by a discrete, actionable playbook. Key moves common across scenarios for 2026:
- Make targeted capital commitments to modular, low-emission production lines where payback is demonstrable within a strategic horizon.
- Negotiate long-term feedstock contracts with clauses that allocate price and supply risks; prioritize arrangements that include circular feedstocks and pyrolysis oils.
- Pursue selective partnerships or bolt-on acquisitions to acquire specialty grades, certification capabilities, or regional logistics advantages rather than broad greenfield expansion.
- Institute procurement and pricing frameworks that reflect carbon-content differentials and enable transparent pass-through to customers.
Signals to Watch in 2026
For executives and investors, the clearest near-term signals that should prompt action include:
- Public announcements of capacity conversions to circular-grade production or commercial-scale pyrolysis feedstock adoption.
- Regulatory rule-making or tariff adoption milestones in major consuming economies that would materially alter cost structures or trade economics.
- Large OEM procurement tenders that explicitly mandate low-carbon or recycled-content carbon black suppliers.
- M&A activity focused on specialty grades, low-emission technology providers, or feedstock logistics businesses.
Conclusion — The Strategic Window for 2026
2026 represents a tactical inflection point for the carbon black value chain. Market growth is predictable on a macro basis, but value capture will be uneven. The leaders over the next cycle will be those that: (1) secure resilient, lower-emission feedstocks; (2) move decisively on compliance-driven capex; (3) commercialize certified sustainable grades; and (4) align commercial terms with evolving trade and procurement regimes.
Our full Carbon Black Market research contains the granular models, competitive benchmarks and tactical playbooks required to operationalize these strategic priorities. For boards, strategy teams and investors preparing capital and commercial plans in 2026, the report provides the decision-ready intelligence to act with confidence while maintaining downside protection against regulatory and feedstock shocks.
Access the full study and the interactive forecast tools on the PW Consulting Carbon Black Market page to download the complete dataset and tailored scenario modules.
For detailed analysis of this topic, please visit the official page: Carbon Black Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


