



PW Consulting: Basic Chromic Sulfate Market to Reach USD 820M by 2032 at 3.8% CAGR

Basic Chromic Sulfate Market: Strategic Imperatives for 2026
As companies finalize budgets and capital plans for 2026, the basic chromic sulfate value chain faces a distinct strategic inflection. Our latest market model (base year 2025) shows the industry expanding from roughly USD 550 million in 2020 to about USD 638 million in 2025, with a conservative baseline CAGR of 3.8% across a 2026–2032 forecast horizon and a projected market size approaching the high hundreds of millions by 2032. These headline metrics capture steady demand but mask important pockets of risk and opportunity that will determine winners and losers next year. This executive primer explains why the PW Consulting Basic Chromic Sulfate Market study is a decision-useful input for 2026 planning — and what we intentionally hold back here to drive a deeper, evidence-based conversation.
Basic Chromic Sulfate Market
Why this report matters to 2026 decision-makers
- Translating macro momentum into executable options. Management needs to map the near-term market trajectory (2026 budget window) to concrete operational choices: procurement tenor, inventory policy, and capital upgrades.
- Regulatory shock preparation. Recent regulatory developments require targeted capital and process choices; our analysis quantifies the cost and timing implications for manufacturers and downstream processors.
- Value capture and premium positioning. With demand growing modestly, the path to margin expansion is through product differentiation, yield improvement, and targeted channel plays — not broad-volume bets.
- M&A and partnership screening. The market concentration profile and regional footprint of players create a distinct set of acquisition and alliance opportunities for strategic buyers in 2026.
Market dynamics that will drive 2026 outcomes
Three structural forces should be at the top of any 2026 agenda:
Basic Chromic Sulfate Market
- Feedstock and upstream availability. Global chromite ore production rose modestly in 2025 (about a mid-single-digit uptick year-over-year, USGS). That relieves some raw-material pressure, but volatility in ore grades, freight costs and regional logistics remains a meaningful input into short-term pricing and contract strategy.
- Regulatory tightening and compliance costs. New and updated rules — notably U.S. EPA NESHAP requirements for chromium electroplating and evolving REACH controls across Europe — are driving investments in process upgrades and emissions control. These requirements accelerate reformulation toward trivalent processing and force manufacturers to quantify capex and recurring compliance expenses. We map compliance impact across plant archetypes in the full study.
- Demand mix and application-level shifts. Leather tanning remains a core demand anchor, with ceramics, catalysts, pigments and other industrial uses shaping complementary demand. The composition and growth rates of these end-use segments will determine where premiumization and volume plays make sense.
Competitive landscape — what concentration implies for strategy
The basic chromic sulfate market shows a moderate-to-high degree of concentration: the top three suppliers control a material share of global capacity, and the top five extend that reach further. This structure creates predictable competitive dynamics:
Basic Chromic Sulfate Market
- Market leaders leverage brand, proprietary grades and scale to command reach into regulated markets, where compliance credentials are increasingly part of the purchase decision.
- Regional and local manufacturers preserve cost and logistics advantages in their domestic markets, often filling the middle market and price-sensitive segments.
- Specialty producers supply high-purity and research-grade products, creating attractive margin pockets that are resilient to commoditization.
Notable players covered in our benchmarking include multinational incumbents with integrated footprints and well-known brands, several large regional producers in Asia and Latin America, plus a cohort of specialty suppliers focused on high-purity or niche industrial uses. The full report provides comparative scorecards that synthesize capacity, product breadth, regulatory posture and margin proxies for each named supplier — a practical toolset for sourcing and M&A screening.
What the PW Consulting report delivers (practical, operational content)
We designed the study for executives who need to act in 2026. The deliverables include:
- Top-line market sizing and a seven-year forecast model (2026–2032) with scenario variants around raw-material shocks and regulatory tightening.
- Price and margin modelling templates that roll up feedstock, energy, logistics and compliance costs to plant-level unit economics.
- Supplier and plant scorecards — capacity maps, regulatory compliance status, and readiness indicators for trivalent/formulation shifts.
- Regulatory impact matrix quantifying CAPEX and OPEX implications under U.S. EPA and EU REACH scenarios.
- Use-case level demand analysis (leather, ceramics, catalysts, pigments and other industrial customers) and go-to-market playbooks for premium grades.
- M&A target shortlist and diligence checklist calibrated to 2026 value drivers.
- Operational interventions and procurement levers (contract structures, hedging approaches, inventory strategies) tailored to common enterprise constraints.
- Risk register and mitigation pathways for feedstock, regulatory, and reputational shocks — including a circularity and recycling roadmap for Council-level sustainability programs.
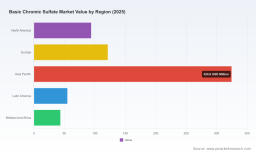
To preserve competitive value in this preview, we intentionally do not disclose the segmented volumetric tables and regional/application-level share breakdowns here — these are available in the full subscriber report and underpin the operational templates above.
Implications for 2026 strategy — targeted recommendations
- Lock feedstock with layered contracts. Implement a tiered contracting approach combining short-term indexed supply to preserve flexibility and a limited set of multi-year anchor contracts to guarantee capacity during regulatory- or logistics-driven tightness.
- Prioritize compliance-led capital upgrades. For manufacturers exposed to electroplating and tanning markets, plan and budget for emissions-control and reformulation projects now; regulatory timetables make 2026 the year to commence spending if you intend to be fully compliant on the planned horizon.
- Segment your product portfolio. Differentiate between commoditized grades (volume plays) and specialty/high-purity grades (margin plays). R&D or partnership investments to improve trivalent formulations can protect customers from hexavalent-related constraints and create a demonstrable value proposition.
- Execute focused M&A and partnership plays. Acquire or partner to shore up regional supply footprints where logistics advantage or regulatory compliance certificates matter most. Bolt-on deals in Asia and targeted partnerships with leather processors can capture downstream margin share.
- Embed regulatory scenarios into pricing. Use price clauses and pass-through mechanisms tied to documented compliance and capex indicators to protect margins against unilateral regulatory cost shocks.
- Invest in circularity pilots. Trial chromium recovery and recycling at scale with lead customers. Even partial recovery programs reduce feedstock exposure and respond to growing sustainability requirements from global buyers.
- Operationalize a 3-tier risk dashboard. Integrate feedstock, regulatory and reputational metrics with leading indicators (e.g., ore-grade alerts, regulatory docket changes, key-customer signaled reformulation timelines) so procurement, operations and commercial can act in weeks, not quarters.
Company playbooks — how different profiles should act in 2026
- Large integrated producers. Accelerate compliance investments, monetize scale through premium compliance-certified offerings, and selectively divest non-core low-margin assets.
- Regional cost players. Double down on logistics and cost-to-serve advantages; pursue certification partnerships to access regulated markets while preserving price leadership at home.
- Specialty and high-purity suppliers. Scale R&D and customer co-development to capture higher-margin niches in research, catalysts and specialty pigments.
Why PW Consulting’s intelligence matters
Two features set our study apart for 2026 planning. First, every recommendation and playbook is tied to a transparent, auditable model that captures feedstock, energy, compliance and logistics variables at the plant and product level. Second, the report translates market concentration and competitive positioning into actionable M&A and sourcing strategies crafted for near-term execution. Given the regulatory backdrop (notably recent EPA NESHAP and REACH-related developments), these elements are not theoretical — they are the difference between a reactive 2026 and a proactive one.
Next steps
If your 2026 plan includes any capacity investment, contract commitments longer than 18 months, or expansion into regulated geographies, the full PW Consulting Basic Chromic Sulfate Market study should be on your desk. It contains the segmented demand maps, supplier scorecards and the downloadable financial models that we withheld from this primer to protect proprietary insights. Reach out to PW Consulting for a custom briefing — we will walk you through the scenario models and recommend the three highest-impact actions tailored to your company profile.
Key sources referenced in this briefing include publicly available mineral supply summaries (USGS) and industry regulatory trackers for EPA and REACH that informed our compliance impact modelling. For access to the full dataset, plant-level risk maps, and supplier scorecards, please consult the PW Consulting report package.
For detailed analysis of this topic, please visit the official page: Basic Chromic Sulfate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


