



TMG Market to Reach USD 344.8 Million by 2032 at 6.8% CAGR — PW Consulting

Trimethylgallium (TMG) Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
The global Trimethylgallium (TMG) market is a niche but strategically critical segment of the larger metalorganic precursors universe that feeds modern semiconductor, LED and emerging micro-LED value chains. Our baseline analysis shows the market expanding from roughly USD 163 million in 2020 to about USD 215 million in the base year 2025, with an expected rise to approximately USD 345 million by 2032. That trajectory implies a compound annual growth rate of 6.8% over the forecast window — a steady expansion driven by capacity additions in optoelectronics, high-volume migration to GaN-based RF and power devices, and rising micro-LED adoption in display—and sensing—segments.
Trimethylgallium (TMG) Market
Why this matters for corporate strategy in 2026
-
Strategic timing: The market is past nascent volatility and entering a phase of structural consolidation and capital intensity. Decisions made in 2026 on supplier partnerships, inventory strategies, and capacity investments will lock in cost curves and supply access for the next decade.
Trimethylgallium (TMG) Market -
Concentration risk: The market exhibits high supplier concentration (CR3/CR5 ≈ 70%), which amplifies the commercial impact of individual supplier moves — capacity ramps, safety investments, or product-grade rollouts translate quickly into global supply shifts.
Trimethylgallium (TMG) Market -
Regulatory and source-material pressure: Heightened export controls, stricter safety and environmental requirements in advanced economies, and gallium supply dynamics have already altered pricing and sourcing logic. These structural elements mean procurement strategies now require scenario-ready hedges, not simple spot contracting.
What this briefing will not do — and why
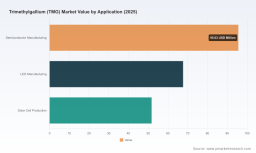
We intentionally present a high-level strategic narrative here to demonstrate the analytical depth of the full study. Key value-driving tables — granular regional and application splits, price-by-grade matrices, and the underlying primary-interview transcripts — are intentionally withheld in this preview. That “teaser” posture is designed so that executives can rapidly validate the report’s strategic relevance here, then access the full dataset and playbooks on the source portal for operational execution.
Market dynamics and drivers
Three structural forces are shaping the TMG market now and will dominate boardroom discussions in 2026:
-
End-market pull from compound-semiconductor deployment. GaN and GaAs device families — in RF, power conversion, and optoelectronics — are the primary demand engines for TMG. Continued migration toward GaN RF for 5G/6G infrastructure and satellite links, and toward micro-LED for high-density displays and optical sensors, is keeping demand visibility strong but lumpy as fabs bring MOCVD capacity online.
-
Supply-chain concentration and materials geopolitics. A small number of suppliers and the geographic concentration of certain upstream gallium production have combined to produce episodes of acute tightness and price dislocation. Policymaker actions — export controls and stricter handling rules — have already forced buyers to rethink single-source exposure and to plan for inventory buffers and secondary sourcing strategies.
-
Regulatory and safety cost inflation. Regulatory requirements in Europe and North America increasingly mandate closed-loop abatement systems, advanced gas-detection architectures, and higher standards for byproduct disposal. These compliance-driven capex and operating-cost increases materially affect the total cost of ownership for new MOCVD lines and change the calculus for fab economics and supplier selection.
Competitive landscape — what to watch
The TMG supplier map blends global chemical majors, specialty organometallic houses, and regional advanced-materials players. Key companies profiled in our research include established European and U.S. chemicals groups, leading specialty-material firms in China, and several premium-purity suppliers focused on research and high-mix production.
-
Large specialty-chemicals groups are leveraging scale and integrated safety systems to dominate high-volume contracts. Expect continued investments in safety automation and logistics tracking as differentiators for contracting MOCVD fabs.
-
Regional players in Asia are advancing higher-purity grades and fast-turn supply models tailored to micro-LED and consumer-driven LED chains — offering attractive lead times and localized support but with different risk profiles versus global suppliers.
-
Small, high-purity specialists remain critically important to R&D customers and niche device lines; their product specs and cylinder-management services command premium positioning in collaboration-heavy programs.
Recent supplier actions illustrate the competitive dynamics executives must track:
-
A leading Chinese materials supplier launched a 6.5N-grade TMG variant targeting defect-sensitive micro-LED stacks — a move that accelerates local sourcing options for Asian fabs and changes qualification timelines for existing suppliers (Dec 2025).
-
A major European chemical company introduced a cylinder-tracking and safety-management platform to reduce handling incidents and inventories at large MOCVD facilities — an example of how operational software plus product can become a procurement differentiator (Sep 2025).
-
Several suppliers have publicly increased industry-facing safety and capacity investments, while others have signed multi-year supply agreements to anchor revenue and offer demand visibility to large fabs (2025 developments across suppliers).
Regulatory, raw-material and pricing tailwinds/risks
-
Export controls and upstream concentration. Geopolitical measures have already tightened external gallium availability and elevated spot prices in certain markets; such shifts compress supplier flexibility and make dual-sourcing and regional inventory hubs more valuable.
-
Stricter safety and environmental regulation. OSHA, REACH, EPA and other regimes are increasing the bar for storage, transport and in-line abatement systems for pyrophoric organometallics. For a fab planning a new MOCVD line, these requirements materially increase capital and operating budgets.
-
Price volatility. Short-term price swings driven by upstream raw material concentration can cascade into project-level P&L impacts for device manufacturers and foundries that do not embed contingency pricing clauses, hedging mechanisms, or strategic inventory playbooks.
Practical report deliverables — what you’ll get
Our full market study is designed as an operator’s toolkit for 2026 planning and contains actionable modules aligned to procurement, technology and corporate-development teams. Highlights include:
-
Bottom-up market sizing and demand modeling across a seven-year forecast period, including grade-by-grade demand scenarios and sensitivity runs keyed to capacity build-outs and adoption curves.
-
Supply-side mapping and risk scoring: plant-level capacity intelligence, supplier financial/operational profiles, and a supplier risk index that integrates concentration, quality, safety history, and geopolitical exposure.
-
Price modeling and contract-playbook: a set of hedging and contracting templates designed to preserve margin and availability under three volatility scenarios, plus a TCO calculator that folds in regulatory capex and abatement operating costs.
-
Operational playbooks for procurement and fab engineering: grade-qualification timelines, cylinder handling and traceability best practices, and a compliance checklist for entering new jurisdictions or scaling MOCVD capacity.
-
Strategic M&A and partnership lens: identification of supply partnership archetypes, acquisition targets by capability, and expected valuation multiples for integrated organometallic assets (with a focus on buyers seeking secure access to high-purity grades).
-
Primary-sourced insights: anonymized interview excerpts with supply-chain managers, lead engineers and regulatory counsel, and a decision-tree matrix that links market signals to recommended executive actions.
How senior managers should use this research in 2026
-
Procurement leaders: update your supplier scorecards to integrate the report’s supplier-risk index and adopt staged contracting — a blend of long-term frameworks for capacity and short-term tactical allocations to manage volatility.
-
Supply-chain and operations: build dual-inventory scenarios into fab ramp plans and fold regulatory capex into MOCVD-line economics before greenlighting new tools or expansions.
-
Corporate development: prioritize targets that provide either access to high-purity grades or embedded logistics/qualification accelerants (e.g., cylinder-tracking or abatement solutions) rather than simple volume plays.
-
R&D and product teams: evaluate trade-offs between higher-grade local suppliers and global suppliers with broader quality assurance programs; time-to-market and yield improvements from grade changes can outweigh per-kg price differentials in high-value device programs.
Conclusion — the strategic choice ahead
For firms that depend on TMG — from LED and micro-LED makers to GaN RF foundries — 2026 is the year to move from reactive buying to strategic supply management. The market’s projected growth, combined with concentration and policy-driven supply shocks, means that procurement and technical decisions made now will define cost and availability through the next expansion cycle. Our full study supplies the data, scenario models, and execution templates needed to convert that strategic imperative into measurable outcomes.
Next step
PW Consulting’s full Trimethylgallium Market Report contains the restricted regional and application-level intelligence, supplier scorecards, and price-by-grade matrices that are intentionally omitted here. For firms ready to operationalize supply resilience, procurement playbooks and M&A screening in 2026, the complete dataset and downloadable toolkits can be accessed on the report landing page.
For detailed analysis of this topic, please visit the official page: Trimethylgallium (TMG) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


