



PW Consulting: Auto Lubricants Market USD 89.9 Billion in 2025; 3.6% CAGR (2026–2032)

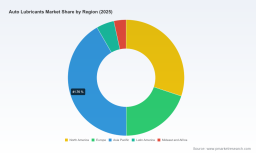
Auto Lubricants Market — Strategic Outlook for 2026 Decision‑Makers
As the global auto lubricants market enters its next phase of structural adjustment, PW Consulting presents an executive preview designed to orient C‑suite and business unit leaders for decisive action in 2026. Anchored on a 2025 base year, the market has expanded from roughly USD 65 billion in 2020 to about USD 89.9 billion in 2025 and is projected to continue growing at a measured compound annual growth rate (CAGR) of approximately 3.6% through our 2026–2032 forecast horizon (reaching an estimated USD 115.2 billion by 2032). These headline figures mask fast‑moving pockets of innovation, regulatory friction and shifting competitive advantage that will determine winners and laggards in the coming 18–36 months.
Auto Lubricants Market
Why this study matters in 2026
- Market sizing that reconciles post‑pandemic demand recovery with structural trends (electrification, synthetic adoption, extended‑drain systems) so resource allocation decisions are evidence‑based.
- Regulatory and OEM approvals mapped to product roadmaps and supply chains — enabling product teams to prioritize formulations that will clear the most important technical and commercial gates in 2026.
- Competitive diagnostics and playbooks for global majors and regional champions so M&A, partnership, and channel investments are targeted rather than speculative.
- Scenario tools and risk matrices that convert macro forecasts into tactical actions (pricing, procurement hedging, inventory strategies) for procurement, manufacturing and aftermarket channels.
Core dynamics reshaping 2026 decisions
Three intersecting forces dominate near‑term strategy: regulation and OEM specification harmonization, technology migration in fluids and additives, and changing demand composition across vehicle types and service intervals.
Auto Lubricants Market
- Regulatory and OEM pressure: The adoption of new industry specifications and harmonized OEM standards is accelerating product obsolescence cycles. For example, API SQ enforcement and the next‑generation passenger car standards (e.g., ILSAC GF‑7 and OEM specification consolidations) are already driving reformulation workstreams across R&D teams. Firms that delay compliance risk being excluded from high‑value OEM and fleet channels.
- Technological migration: Formulation trends favor lower‑viscosity synthetics and advanced additive chemistries that unlock fuel‑efficiency gains and extended drain intervals. Recent approvals for advanced additive packages and OEM validation of extended‑drain heavy‑duty oils demonstrate the commercial value of additive IP and co‑development with engine makers.
- Demand resilience and evolution: While the aggregate market shows steady expansion (roughly mid‑single digit CAGR in our forecast window), demand composition is diverging — growth pockets (aftermarket, fleet maintenance solutions, EV‑specific lubricants and specialty greases) contrast with pressure in legacy segments. This dynamic requires granular portfolio decisions rather than broad market bets.
Competitive landscape — what the leaders’ moves tell us
The market exhibits moderate concentration — the three‑firm and five‑firm concentration ratios indicate that global majors hold meaningful but far from decisive share. Competitive advantage is increasingly driven by technology roadmaps, OEM approvals, branded aftermarket strength, and regional service networks rather than raw scale alone.
Auto Lubricants Market
- Shell plc (The Hague) — Deep OEM and aftermarket integration under Helix/Advance; co‑branding and motorcycle co‑development moves demonstrate a focus on segmented premiumization and brand premium capture.
- ExxonMobil (Irving, Texas) — Mobil 1 remains a technology anchor; continued emphasis on synthetics and fuel‑efficiency messaging positions ExxonMobil to defend high‑margin passenger car segments and transfer learnings to commercial lubricants.
- BP / Castrol (London) — Castrol’s EDGE and RS lines combine motorsport‑driven credibility with commercial productization; their global service footprint supports aftermarket premiumization strategies.
- Chevron (San Ramon) — Rapid upgrade to ILSAC GF‑7 / API SQ formulations shows a play to maintain OEM and heavy‑duty credentials while protecting legacy fleet revenue.
- TotalEnergies (Paris) — The company’s recent role as a primary supplier across a harmonized OEM specification set highlights the strategic value of early co‑development and standards engagement.
- Fuchs Petrolub (Mannheim) — A niche leader in high‑performance synthetics with strong OEM approvals; appealing to premium niche and technical customers where formulation performance matters more than scale.
- Phillips 66 & Valvoline (USA) — Both emphasize heavy‑duty and fleet solutions; Valvoline’s recent OEM‑validated extended‑drain milestone underscores the commercial upside in long‑drain multi‑fuel oils.
- Regional champions (e.g., Indian Oil, PetroChina, Idemitsu) — These players leverage national distribution, strategic OEM relationships and cost leadership for both domestic markets and export corridors.
Recent public developments are instructive for playbooks in 2026: a major extended‑drain OEM approval for a heavy‑duty formulation, additive technology clearing a new OEM specification, and a single supplier gaining broad approval across a harmonized OEM standard — each underscores the strategic value of early technical alignment with engine OEMs and additive partners.
What’s inside the PW Consulting report — actionable deliverables
- Concise market sizing and trend analysis (2020–2025 historical reconciled; 2026–2032 forecast), with sensitivity scenarios tied to base oil pricing and vehicle mix evolution.
- Regulatory and OEM approval tracker that maps which specifications are binding by market and timeframe and which product types require priority reformulation.
- Technology and additive landscape: supplier matrix, IP hotspots, and co‑development pathways that accelerate OEM approvals.
- Competitive scorecards for the leading players and regional champions, including strategic positioning, go‑to‑market models, and likely next moves.
- Go‑to‑market playbooks for aftermarket, OEM, and fleet channels with channel economics, margin sensitivities and promotional levers.
- M&A and partnership screening tools — target lists and valuation heuristics for bolt‑on acquisitions or JV candidates that close capability gaps fast.
- Operational checklists (manufacturing, quality, compliance) and procurement hedging templates for base oils and additive exposure.
- Executive dashboards and tailored scenario models for internal planning and investor communications.
Note: This preview intentionally omits our full, granular segmentation tables and region/application breakdowns to preserve the report’s proprietary value. The full research contains area‑level and application‑level splits, price‑by‑product schedules, and detailed company financial proxies that are critical for transaction‑level decision making.
How to use these insights in 2026 — prioritized actions
- Short term (0–12 months): Validate reformulation roadmaps against binding specifications; secure critical OEM approvals by investing in targeted co‑development; harden supply agreements for base oils and strategic additives to avoid disruptive cost spikes.
- Medium term (12–36 months): Reallocate R&D and capex toward low‑viscosity synthetic platforms and EV‑relevant fluids; develop commercial propositions around extended‑drain and lifecycle services for fleets; build aftermarket propositions that monetize service intervals and diagnostics.
- Strategic / long term (36+ months): Consider capability‑based M&A or JVs to acquire additive IP or regional service networks; institutionalize an OEM‑alignment function to shape emerging specifications rather than only react to them; deploy selective digital‑services to increase customer lifecycle revenue.
Implications for risk and value capture
Moderate market concentration means there is room for well‑executed challengers and regional specialists to capture disproportionate value. However, the path to scale is increasingly technical: access to additive IP, fast OEM validation cycles and branded aftermarket channels now determine margin expansion more than raw distribution reach. Firms that proactively manage regulatory timelines, secure OEM approvals and lock in additive supply will materially outperform peers in 2026.
Next steps — where PW Consulting adds value
For leaders preparing 2026 budgets, portfolio reviews or M&A pipelines, the full PW Consulting Auto Lubricants report provides the executable intelligence missing from public summaries: granular regional and application splits, price/volume tables, OEM‑approval roadmaps, and bespoke scenario modeling. If your objective is to prioritize capex, select acquisition targets, or accelerate an OEM approval program, our analysts and industry strategists can map those outcomes against the quantitative forecast and competitive playbooks in the full study.
To access the complete dataset, company scorecards, and executable playbooks (including the granular segmentation withheld from this preview), please visit the report landing page or contact PW Consulting for a confidential briefing.
For detailed analysis of this topic, please visit the official page: Auto Lubricants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


