



PW Consulting: Basalt Fiber Market to Reach USD 688M by 2032 at 8.5% CAGR; Asia-Pacific Leads

Basalt Fiber Market — A Strategic Preview for 2026 Decision-Makers
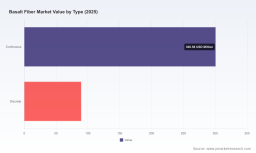
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused strategic preview of our full Basalt Fiber Market study — designed specifically to shape executive decision-making in 2026. Our model shows the global basalt fiber market expanding from a base-year revenue of USD 390 Million (2025) with a compound annual growth rate (CAGR) of 8.5% across the 2026–2032 forecast window, reaching an addressed market exceeding USD 680 Million by 2032. Historical traction is clear: the market scaled materially from 2020 through 2025, reflecting technology maturation, improving cost curves and accelerating commercial adoption across several heavy-volume applications. This preview signals where competitive advantage will be created — and what leaders must prioritize next quarter — while reserving the granular segmentation and tactical tables for subscribers of the full report.
Basalt Fiber Market
Why this report matters for 2026 planning
Basalt fiber is no longer a niche material. Two structural shifts converge to create a sustained growth runway through the next decade. First, macro policy and procurement trends — notably decarbonization mandates, circular-material preferences in advanced economies, and lifecycle regulations in construction — are elevating demand for alternatives to traditional glass and steel reinforcement. Second, the industry is proving that basalt feedstock, available from abundant volcanic sources, can be converted into high-value fiber at competitive economics: the conversion of raw basalt into fiber markedly multiplies the product economic value and creates opportunities for regional beneficiation.
Basalt Fiber Market
Operationally, basalt fiber manufacturing uses high-temperature processes (melting in the ~1450–1500°C range) but, crucially, does not require extensive chemical synthesis nor generate persistent harmful gas streams during processing. That characteristic simplifies certain regulatory pathways and supports sustainability narratives that many buyers now require. Price dynamics are maturing too — current industry benchmarks place average selling prices in the mid-teens per kilogram, with grade and application sensitivity — creating predictable scenarios for cost engineering and contract negotiation.
Basalt Fiber Market
What the full report delivers (actionable highlights)
- Market sizing and forward-looking demand model (2020–2032), with scenario runs for high- and low-adoption pathways tailored to policy and energy-price shocks.
- Supply-side mapping and a manufacturing cost curve that identifies where incremental capacity will be most economical to add.
- Technology and product segmentation that differentiates continuous vs. chopped/discrete fibers and grades optimized for wind, construction, automotive and specialty composites.
- Competitive benchmarking and capability scorecards (including market concentration metrics), with practical guidance on partner selection and deal structures for supply assurance.
- Commercial playbooks — pricing strategies, long-term offtake structuring, and specification pathways to accelerate procurement adoption.
- M&A and greenfield investment screens: payback sensitivity, break-even volumes, and recommended integration pathways for downstream converters.
- Regulatory & sustainability impact assessment: lifecycle GHG profiles, circularity pathways and compliance risks in core regions.
- Primary research appendices: expert interviews, supplier audits, and a validated buyer demand pipeline to underpin business-case level decisions.
Competitive landscape — what to watch
The market shows a balance of established industrial producers and technically-focused specialists. Concentration indicates meaningful scale players but also clear room for strategic entrants: the top three firms account for around 46% of the market by revenue, and the top five capture roughly 58%. That structure fosters both competition on cost/scale and opportunities for differentiation through product performance and value-added services.
- Integrated large-scale producers: Several long-running manufacturers have capabilities across continuous roving, fabrics and composite preforms. Their playbook emphasizes volume, established distribution and cost leadership through automated drawing and integrated downstream conversion. These firms are best positioned to serve large-volume construction and industrial reinforcement needs.
- Performance- and specialty-focused suppliers: A second group emphasizes higher-strength grades, engineered rovings and tailored fabric architectures for demanding automotive, aerospace and wind-energy components. Their differentiation lies in product-grade engineering, technical support, and co-development with OEMs.
- Regional and project-stage challengers: New or growing producers focus on localized feedstock integration and niche applications, using proximity to raw basalt sources or targeted R&D to accelerate commercialization.
Representative examples from our competitive review reflect these archetypes. Some producers have recently expanded capacity to address surging demand from construction and renewable-energy OEMs; others have introduced coated fibers or patented processing methods to open new performance and application windows. These moves illustrate two strategic vectors: (1) scale and vertically-integrated supply to win volume contracts, and (2) product-led differentiation to capture premium margins in high-performance applications.
Recent industry moves and their strategic signals
- Capacity expansions at established continuous-fiber producers indicate confidence in near-term demand from construction and wind segments — signaling an industrialization phase where securing feedstock and stable energy supplies will be critical.
- Novel product launches, such as metal-coated fibers for EMI/RFI shielding and thermal management, demonstrate that basalt fiber is extending beyond structural use into multifunctional roles — opening routes to higher-margin specialty markets.
- Patents and new production methods for rebar and high-strength reinforcement reveal that a subset of players is targeting direct displacement of incumbent materials in infrastructure, creating sizable addressable opportunities where specifications can be updated.
- Grade optimizations for wind-energy blades and large-structure composites point to priority demand pockets; firms positioning as preferred suppliers in those supply chains can capture durable revenue streams if they meet certification and quality thresholds.
Strategic implications for 2026 executive decisions
For management teams evaluating entry, scaling or defense strategies in 2026, the study distills into five pragmatic imperatives:
- Secure feedstock and energy exposure: Vertical integration or long-term feedstock agreements materially reduce cost risk and support predictable margin modelling — crucial for capital-intensive fiber lines.
- Choose your value capture model: Compete on scale (volume contracts + low unit costs) or on differentiation (engineered grades, coatings, technical services). Attempting both without clear allocation of capital and capabilities dilutes returns.
- Certify early for priority end-markets: Winning wind-turbine, infrastructure or automotive programs requires preemptive investment in testing, certification and OEM co-development — a lead-time-sensitive activity.
- Design commercial contracts to de-risk price volatility: Indexing mechanisms, tiered pricing by grade and multi-year offtakes with flexibility clauses will be standard in 2026 negotiations.
- Prioritize modular, scalable manufacturing investments: Given the projected CAGR and market expansion profile, modular capacity additions and licensing are more defensible than large single-step greenfields in many geographies.
Risk map — what could change the outlook
- Energy price shocks: Melting temperatures for fiber production are energy intensive; abrupt fuel or electricity cost increases compress margins and slow new-build economics.
- Regulatory shifts: While sustainability tailwinds currently favor basalt, unanticipated changes to emissions accounting or waste-handling rules could introduce localized hurdles.
- Supply chain constraints: Bottlenecks in drawing equipment, specialty sizing chemistries or conversion capacity could delay market absorption of new fiber volumes.
- Competitive innovation: Breakthroughs in coatings, hybrid composites or alternative reinforcement materials could alter relative value propositions in certain applications.
Five board-level questions this preview answers
- Is now the right time to commit capital to basalt fiber manufacturing, or should we secure supply through contracts and partnerships?
- Which commercial model (scale vs. differentiation) aligns with our balance sheet and customer relationships?
- How should we structure long-term sales agreements to protect margins while enabling customer adoption?
- What technology capabilities and certifications unlock the largest, most defensible opportunities within wind and infrastructure markets?
- Which acquisition targets or regional partnerships would shorten our time-to-market with minimal integration risk?
Our full Basalt Fiber Market report expands each of these answers into executable plans, complete with financial model templates, supplier scorecards, and a prioritized action timeline for 2026 implementation. It also contains the detailed segmentation and regional/application-level forecasts that underpin the strategic recommendations summarized here.
For teams making capital allocation and market-entry choices in 2026, the decision horizon is short. The market is growing at a steady double-digit-adjusted rate by historical proxy and consensus dynamics, competition is bifurcating along scale and technical differentiation, and regulatory tailwinds favor early movers who can demonstrate low-carbon, high-performance credentials. Access the full study to obtain the granular datasets, segmentation tables and tactical playbooks required to convert strategic intent into measurable outcomes.
For detailed analysis of this topic, please visit the official page: Basalt Fiber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


