



PW Consulting: Feeding Bottle Market Poised for 4.89% CAGR Through 2032

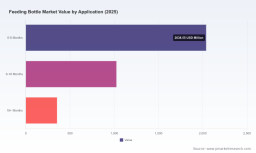
Feeding Bottle Market: Strategic Outlook for 2026 Decision‑Makers
PW Consulting’s Feeding Bottle Market study (base year 2025; historical window 2020–2025; forecast horizon 2026–2032) is designed as an executive-grade intelligence product to inform boardroom decisions in 2026. Built on a transparent market model and validated primary research, the study projects a steady expansion of the global market at a compound annual growth rate (CAGR) of 4.89% across the forecast period. The market’s aggregate size—measured in USD Million—has shown recovery and premiumization since 2020 and is projected to expand meaningfully toward 2032, reflecting simultaneous forces of regulatory tightening, material and design innovation, and shifts in clinical purchasing behaviour.
Feeding Bottle Market
Why this study matters for 2026 strategy
- Capital allocation: Understand when a product line merits incremental CAPEX (e.g., automation and new-material tooling) versus when to pursue leaner routes such as contract manufacturing or licensing.
- Portfolio prioritization: Distinguish hospital-grade and enteral offerings from consumer and premium consumer segments to align R&D and marketing spend with margin pools.
- Regulatory and commercial risk management: Anticipate compliance costs and market access implications driven by regional food-contact regulations and breastfeeding promotion frameworks.
- M&A and partnership screening: Use concentration and competitor dynamics to identify acquisition targets that deliver scale, specialty capabilities (medical-grade PPSU, enteral interfaces), or access to automated capacity.
- Go-to-market optimization: Calibrate sales coverage, channel mix and pricing architecture for 2026 procurement cycles—particularly for hospital and neonatal channels that are governed by different procurement timelines and compliance rules than retail.
Market trajectory and strategic implications
The aggregate market recovered from pandemic-era dislocations and exhibited year-to-year variability during 2020–2025 before resuming a stable upward trajectory. That trajectory underpins three actionable implications for corporate strategy in 2026:
Feeding Bottle Market
- Resilience with selective upside. The underlying demographic base provides a stable demand floor; incremental growth is being driven by product premiumization (safety-certified materials, anti-colic designs) and expanded clinical applications (enteral/ supplemental feeding solutions).
- Margin differentiation by product class. Companies that migrate to higher-spec materials and clinical-grade features capture outsized pricing power, but must manage cost and supply-chain complexity associated with medical-grade polymers and sterilization validation.
- Timing matters. The forecast horizon offers a clear window—2026 is an inflection point where investments in automation, material upgrades, and regulatory compliance begin paying off through improved margins and accelerated hospital adoption.
Competitive dynamics: what leading players reveal
The market displays moderate concentration (CR3 ~ 38.7%; CR5 ~ 52.3%), leaving ample space for regional champions and specialized entrants. Several competitive patterns are decisive for 2026 planning:
Feeding Bottle Market
- Medical‑grade differentiation: Established brands with hospital footholds (e.g., those specializing in medical‑grade PPSU and silicone products) are reinforcing clinical positioning—an attractive route for premium margins and longer procurement cycles.
- Channel realignment in response to codes and standards: Some firms have made strategic decisions to withdraw non‑medical consumer offerings or reclassify go‑to‑market activities to align with the WHO Code and local marketing restrictions. These moves reallocate competitive intensity across hospital and retail channels and create windows for competitors to capture displaced consumer demand.
- Material and safety innovation as a competitive moat: A wave of product upgrades—PPSU, improved thermoplastics, and medical silicone—has become a primary basis for differentiation; companies that control validated material supply or proprietary formulations have an advantage.
- Automation and scale: Firms that invested early in automated production capture both cost advantage and consistent quality for clinical customers. That capability shortens time to contract compliance for neonatal and enteral use cases.
Leading players (global brands and specialized clinical suppliers alike) are pursuing slightly different strategies: premiumization and hospital-centric offerings, targeted geographic expansion into fast-growing health systems, and platform plays that bundle bottles with feeding systems and clinical accessories. Recent corporate moves—such as the cessation of consumer feeding bottle sales by a major medical supplier in mid‑2025 to honour international marketing codes, and the launch and material‑upgrade initiatives by regional challengers—underscore an industry in the midst of structural rebalancing.
Regulatory and clinical context shaping 2026 decisions
Regulation and clinical guidance are major strategic levers. Recent developments include regional bans on certain plasticizers in infant feeding articles and new EU rules on food-contact materials that have implications for compliance testing, labelling, and permitted formulations. At the same time, breastfeeding promotion initiatives and hospital accreditation programmes explicitly constrain bottle-use messaging in maternity settings, altering demand and marketing access in hospitals.
For manufacturers and distributors, this means: proactive product certification workflows, investment in validated material suppliers, and the design of compliant commercial strategies that separate clinical from consumer messaging. Companies that can demonstrate medical-grade processes (sterilization validation, traceability, clinical compatibility) will be advantaged in hospital procurement while preserving compliant retail placements.
Supply-side and operational considerations
- Materials strategy: Transitioning to PPSU, high‑performance thermoplastics, and medical silicones reduces breakage and supports sterilization expectations. Supplier partnerships and validated supply‑chain mapping are prerequisite investments.
- Automation and cost profile: Fully automated bottle production, already implemented by some professional manufacturers, reduces labour variability and delivers consistent clinical-grade output. For mid‑sized producers, contract manufacturing partnerships can be an effective near-term alternative.
- Clinical device integration: Opportunities exist in modular systems—bottles designed to interface with enteral holders, infusion stands, and hospital feeding workflows. These interfaces require clinical validation but open higher-margin revenue streams.
- Quality and testing: Enhanced testing regimes for leachables, sterilization cycles, and durability are not optional; they are becoming the cost of entry for hospital channels and premium retail segments.
What the PW Consulting report delivers (practical contents)
The report is structured as an operational playbook rather than an academic review. Key deliverables include:
- A validated market model (base 2025) with scenario options for conservative, base, and aggressive adoption paths through 2032—delivered in a reusable spreadsheet model.
- Probabilistic forecast and sensitivity analysis illustrating the revenue and margin impact of material cost changes, regulatory compliance expenditures, and channel shifts.
- Competitive landscaping with strategic profiles of the major global and regional players, mapped by capability (medical vs. retail), material expertise, and manufacturing posture.
- Product and clinical matrix highlighting design features (anti‑colic systems, neonatal ergonomics, enteral compatibility) and their procurement implications for hospitals vs. retail channels.
- Regulatory tracker and compliance playbook covering major markets, key standards, and required documentation for medical‑grade claims.
- M&A and partnership heatmap prioritizing targets by capability, scale, and integration risk, and a procurement negotiation toolkit for hospital tenders.
- Actionable go‑to‑market blueprints for 1) hospital penetration, 2) premium consumer launches, and 3) channel defense against private‑label entrants.
To preserve the competitive utility of this intelligence and to maintain the “trailer” principle of this executive summary, segmented allocations by region, product type and application—together with full company market shares and detailed unit‑level economics—are presented only in the full report and the downloadable model.
How to convert insight into 2026 actions
- Fast‑track clinical validation for any new material or anti‑colic mechanism—buyers in neonatal and hospital channels demand documented performance and traceability before awarding contracts.
- Reassess consumer portfolio footprints where marketing constraints (and reputational risk) intersect with low margin competitive activity; consider premium sub‑brands or licensed clinical lines as alternatives.
- Invest selectively in automation or secure long‑term manufacturing contracts to stabilize cost and quality for medical streams—this is a multi‑year payback but a near‑term procurement differentiator.
- Use scenario planning to set M&A price thresholds that reflect concentration dynamics; target assets that close capability gaps (medical-grade materials, automated capacity, hospital channel access).
- Implement a regulatory watch function inside product development to ensure that material choices and marketing claims remain compliant as local food-contact and breastfeeding‑support policies evolve.
Next steps and how to access the full intelligence
PW Consulting’s Feeding Bottle Market study is intentionally structured to show strategic contours in this executive preview while reserving the full disaggregated data, proprietary models, and company-level share calculations for licensed subscribers. If you are evaluating capital allocation, product roadmaps, or corporate development options in 2026, the full report provides the detailed segmentation, interactive forecast model, and negotiation playbooks required to act with conviction.
Contact PW Consulting to arrange a briefing, license the report, or obtain the model and the complete set of appendices that contain the granular regional, type and application splits, as well as the unabridged competitive intelligence dossiers and primary‑source citations.
For detailed analysis of this topic, please visit the official page: Feeding Bottle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


