



PW Consulting: EFB Market to Grow at 8.1% CAGR Through 2032

Electronic Flight Bag Market 2026: A Strategic Preview for Executive Decision-Making
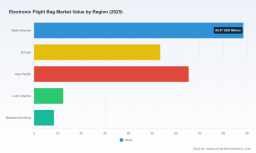
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present this focused preview of our full Electronic Flight Bag (EFB) Market research to orient decision-makers preparing for 2026. The EFB market has moved from a nascent operational convenience to a core element of avionics architectures and flight operations strategy. Our study—anchored on a 2025 base year—documents a market that has expanded steadily from 2020 and is set to grow at a compounded annual growth rate (CAGR) of 8.1% through the 2026–2032 forecast window. The total market size, measured in USD millions, rose markedly in the 2020–2025 historical period and is forecast to approach the high hundreds of millions by 2032, creating a multi‑vector set of opportunities and risks for OEMs, airlines, systems integrators, and service providers.
Electronic Flight Bag Market
Why this study is material for 2026 corporate decisions
-
Investment prioritization: rapid product cycles, software-first business models, and certification timelines mean capital allocation needs to differentiate between near-term revenue capture and long-term platform plays.
Electronic Flight Bag Market -
Regulatory timing: recent and upcoming guidance changes create windows for accelerated adoption for compliant solutions—and conversely, cliff‑edge risks for suppliers that miss new accuracy or authorization requirements.
Electronic Flight Bag Market -
M&A and partnership sequencing: the market exhibits concentrated supplier leadership at the top, yet niche functional and geographic gaps remain attractive targets for bolt‑on acquisitions and alliances.
-
Procurement and fleet transition planning: airlines and larger operators must align EFB procure-to-certify roadmaps with avionics retrofits and broader digitization programs to avoid duplicate spends and operational disruption.
What the full report delivers — operational, actionable content
-
Concise executive summary and scenario-based outlooks that translate a single CAGR into three operational growth trajectories, with linked implications for revenue mix, CAPEX, and service models.
-
Validated market sizing and historical trend analysis (2020–2025) and a granular forecast to 2032—presented as an executive decision tool rather than raw tables.
-
Regulatory impact framework mapping EASA, FAA and industry guidance onto certification timelines, operator authorization risk, and required product feature sets.
-
Technology and product roadmaps covering hardware platforms (portable vs installed), avionics interfaces, connectivity stacks, and software ecosystems—aligned to innovation priorities and certification constraints.
-
Implementation playbooks for different buyer archetypes—airlines, business aviation operators, MROs and OEMs—detailing procurement timing, STC/PMA pathways, and integration checkpoints.
-
Competitive benchmarking and vendor scorecards with strengths, capability gaps and partner fit—linked to go‑to‑market options such as white‑label, OEM partnership or direct airline contracts.
-
Risk matrices and mitigation levers for cybersecurity, data integrity, and regulatory non‑compliance, plus operational KPIs for rollout and in‑service performance monitoring.
-
Commercial models and pricing strategies including SaaS subscriptions, per‑seat licensing, hardware-as-service propositions and aftermarket support economics.
-
M&A and partnership playbook identifying target profiles, valuation sensitives and integration pitfalls drawn from a detailed industry concentration analysis.
Market dynamics shaping 2026—what executives must internalize
The EFB market in 2026 is being re‑shaped by three concurrent forces: regulatory tightening, platform convergence, and connectivity maturation. Regulators have sharpened expectations for Type B applications used in aircraft performance and mass & balance computations, and guidance updates have clarified authorization pathways for both commercial and general aviation operators. At the same time, tablet and installed solutions are converging functionally as avionics interfaces, aircraft interface devices, and certified Class 3 systems support richer real‑time data flows. Connectivity—satcom, ground links and ADS‑B relay services—has moved from “nice to have” to a differentiating operational capability for procedural efficiency and situational awareness.
These dynamics translate into concrete commercial consequences: buyers will favor suppliers that can deliver demonstrable compliance evidence, minimal retrofit disruption, and predictable lifecycle economics. Suppliers that combine certified avionics interfaces, robust software update mechanisms, and scalable commercial models will capture disproportionate value. The market concentration metrics reflect a competitive structure where a small group of established vendors controls a majority of the market, but meaningful space exists for specialists with unique IP or regulatory approvals.
Competitive landscape — capabilities to watch in 2026
-
Established avionics integrators are leveraging certified hardware and dual‑processor architectures to address installed Class 3 demands and streamlined STC/PMA certification pathways.
-
Software-centric providers focus on UX, real‑time charting and augmented overlays to win portable EFB traction, especially among smaller operators and GA segments.
-
Systems and connectivity vendors are bundling Aircraft Interface Devices and ground link suites with analytics and aircraft data capture to offer “EFB+” propositions that address both operational workflows and data monetization.
Among named players, notable strategic positions include established avionics OEMs concentrating on integrated installed systems and Type B capability assurance; specialized tablet and app providers prioritizing user experience and rapid certification paths for portable use; and component/system vendors emphasizing FAA/EASA compliant interface units and mounting solutions with existing approvals. Recent market signals—industry subcommittee reports and product updates—underscore a tangible acceleration in device capability expansions, legal guidance for pilot-operator compliance, and vendor participation in experiential forums. These developments materially affect both product roadmaps and buyer procurement windows in 2026.
Strategic recommendations — a 12‑36‑month playbook
-
Immediate (next 12 months): Conduct an EFB compliance gap assessment linked to your fleet mix and operational model. Prioritize pilots for retrofit opportunities where new guidance lowers certification friction.
-
Near term (12–24 months): Secure partnerships or STC pathways with vendors that demonstrate both avionics integration credentials and a certified update mechanism. Negotiate commercial terms that align upgrade costs with operational savings.
-
Intermediate (24–36 months): Build or acquire analytics capabilities that leverage EFB data streams—this drives recurring revenue and operational differentiation while enhancing safety and performance insights.
-
Longer term (36+ months): Position for consolidation by identifying niche targets—software platforms, interface device makers or regional integrators—that close capability gaps and accelerate time‑to‑market for new EFB services.
Each stage should be governed by quantifiable KPIs: time‑to‑certification, mean time to deploy per aircraft, lifecycle TCO per seat, and percentage of operations migrated to digitally validated workflows. These metrics convert the macro CAGR into operational thresholds for investment approval and program gating.
Using this preview — next steps to access complete intelligence
This preview surfaces the strategic contours you must consider in 2026, while the full PW Consulting report contains the granular market segmentation, vendor financial models, scored vendor profiles and downloadable scenario workbooks you need to operationalize decisions. We have intentionally withheld core segment‑level numbers and detailed profit pool breakdowns in this executive preview to protect analytical integrity and to guide procurement teams to the complete study for transaction‑grade detail.
For senior leaders preparing capital plans, certification programs, or M&A pipelines, the right next step is a focused briefing with our analysts: we will map the full model to your fleet and product positions and surface the three highest‑probability actions that protect and grow your share in the EFB value chain.
PW Consulting’s EFB market study is engineered to convert a market CAGR and multi‑year forecast into concrete, risk‑adjusted actions. In an environment where regulatory clarity and systems convergence are rewriting procurement rhythms, executives who translate these high‑level signals into disciplined tactical plans in 2026 will secure both near‑term operational gains and durable strategic advantage.
For detailed analysis of this topic, please visit the official page: Electronic Flight Bag Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


