



PW Consulting Insights: Chlorinated Polyolefin Market—5.1% CAGR to USD 5,920M by 2032

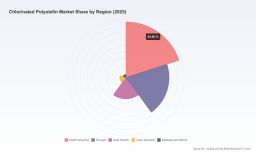
Chlorinated Polyolefin Market — Strategic Preview for 2026 Decision Makers
Executive snapshot
As PW Consulting’s senior strategy and industry analysis team, we present a forward-looking primer on the Chlorinated Polyolefin (CPO) market to orient executive decisions in 2026. Anchored on a 2025 base year and a detailed historical review (2020–2025), our full study projects the market through 2032 under multiple scenarios. At a macro level, the market has expanded steadily from the early 2020s and, with a compound annual growth rate of roughly 5.1% in our forecast window (2026–2032), is expected to continue that trajectory. Our modeled headline sizing shows the market at approximately USD 4.2 billion in 2025 with a path to just under USD 6.0 billion by 2032 under the central case—figures that capture both cyclical recovery patterns and structural demand shifts.
Chlorinated Polyolefin Market
Why this matters for 2026 strategic choices
Executives evaluating capex, commercial strategy, or M&A in 2026 face a market that is neither hyper-consolidated nor atomized: concentration metrics indicate a modestly fragmented supplier base, with the top three and top five suppliers accounting for less than one-third of global share. That structure favors differentiated plays—technical leadership, tight downstream partnerships, or regional cost advantage—over undifferentiated scale alone. At the same time, ongoing technology and regulatory pressures are altering value capture: formulators and compounders who can re-engineer property trade-offs or vertically integrate balance sheets stand to secure outsized margins.
Chlorinated Polyolefin Market
What the full report delivers (practical, board-ready intelligence)
- Proprietary market sizing and a trio of forecast scenarios (central, upside, downside) rooted in demand-driver micro-models and risk overlays covering 2026–2032.
- Demand-driver diagnostic: end-use elasticities, substitution risk matrices, and a near-term demand heat map calibrated to macro and sector-specific indicators.
- Supply-side mapping: an original global capacity ledger, cash-cost curves, and integration archetypes that explain which asset footprints drive margin resilience.
- Commercial playbooks: go-to-market options for specialty grades (adhesion promoters, impact modifiers, flame-retardant resins), distributor economics, and price-indexing strategies tailored to different customer segments.
- Regulatory and formulation risk assessment: scenario-testing for halogen restrictiveness, labelling shifts, and lifecycle compliance that materially affect formulation choices and market access.
- Competitive benchmarking: comparative scorecards for technology, cost position, and route-to-market for leading suppliers, plus a prioritized M&A and partnership pipeline with integration checklists.
- Implementation roadmaps: 90/180/360-day action plans for commercial pilots, cost-curve improvements, and a staged investment plan for capacity and product development.
Market dynamics that will shape 2026 decisions
The CPO market sits at the intersection of raw-material volatility, regulatory evolution, and persistent end-use demand from adhesives, paints & coatings, and specialty polymer applications. Key dynamics we stress in the report:
Chlorinated Polyolefin Market
- Raw-material and feedstock structure: CPO producers’ margins are sensitive to feedstock swings in olefin and chlorine markets. Producers with integrated hydrocarbon-to-chlor-alkali linkages demonstrate clear cash-cost advantages and have historically outperformed peers on margin stability.
- Regulatory headwinds and substitution: Increasing halogen-free preferences in parts of Europe and North America are accelerating trial adoption of alternative elastomers and polyolefin blends in certain cable and wire applications. Nevertheless, CPO retains an economically defendable niche where oil resistance, weatherability, and flame performance are non-negotiable.
- Fragmentation and specialization: With top-supplier concentration relatively low, technical differentiation—grade portfolios and custom compounding capabilities—remains the primary route to premium pricing. That creates opportunity for mid-market players to capture specialty pockets via targeted commercialization or JV structures.
- Cost-structure divergence across regions: Chinese and other integrated producers benefit from domestic integration and scale dynamics that drive lower operating costs, influencing global trade flows and competitive tension in price-sensitive segments.
Competitive landscape — what executives need to know
The competitive field is populated by a mix of global chemical majors, regional-scale specialists, and compounders focused on application-specific formulations. Our full analysis profiles leading players across capability, strategic intent, and recent moves:
- Aurora Material Solutions (Streetsboro, Ohio): A focused elastomer and compounder that recently expanded its polymer compounding capabilities via acquisition. Their strategy demonstrates a playbook centered on capability-based vertical expansion—blending specialty CPE/CPO grades into higher-value alloys and cable compounds.
- Eastman Chemical Company (Kingsport, Tennessee): A major supplier of adhesion promoters and specialty resins, Eastman has announced capacity expansion to meet rising global demand—an indication of OEM-driven pull for adhesion solutions and a signal for competitors to consider capacity and premium product roadmaps.
- Resonac (formerly Showa Denko, Tokyo): A producer of specialty chlorinated resins positioned around flame-retardant and high-performance grades; Resonac’s technical-grade focus is a reminder that application-specific formulations command margins that are resilient to commodity cycles.
- Large Chinese manufacturers and regional producers (several well-established players across Zhejiang and Shandong provinces, and Indian groups): These suppliers combine scale manufacturing, domestic feedstock integration, and global distribution to pressure price-sensitive segments while selectively moving up the value chain.
- Specialist suppliers and compounders in North America and Europe: They emphasize technical service, fast prototyping, and low-volume custom grades—an attractive proposition for OEMs seeking formulation security against regulatory shifts.
Recent commercial signals
- Capacity and capability expansion by major resin suppliers signals anticipated demand growth in adhesion promoters and specialty coatings applications; such moves typically presage tighter supply in premium grades and create short- to medium-term arbitrage opportunities for nimble regional players.
- M&A activity among compounders points to consolidation of application know-how rather than raw material assets—an insight that should shape acquisition screens and post-merger integration plans.
Strategic imperatives for 2026
Based on our central forecast and sensitivity testing, we recommend that executives evaluate initiatives across three time horizons:
- Near term (0–12 months): Secure dual-sourced feedstock contracts and negotiate indexed supply agreements to buffer chlorine and olefin volatility. Pilot customer co-development projects for specialty adhesion and impact-modifier grades to lock in long-lead, high-margin programs.
- Medium term (12–36 months): Consider targeted capacity additions or tolling arrangements near strategic downstream clusters (coatings hubs, cable-manufacturing corridors). Pursue bolt-on acquisitions in compounding or formulation services to close the capability gap with technical incumbents.
- Long term (36+ months): Evaluate vertical integration or strategic JVs for feedstock security in regions where chlorine and ethylene integration materially improves cash costs. Build product stewardship and lifecycle-assessment capabilities to maintain market access under evolving environmental regulation.
How to use the full report in board-level decision making
Leaders should use the full PW Consulting study to translate market-level projections into specific investment cases. The report’s scenario outputs feed directly into NPV and real-options models for greenfield capacity, acquire-versus-build syndicates, and pricing strategy simulations. Importantly, our sensitivity matrices allow procurement, R&D, and commercial teams to stress-test portfolio choices against plausible regulatory and feedstock shocks.
Invitation — what we are intentionally withholding here
This preview is designed to demonstrate depth and frame high‑impact choices for 2026. In keeping with the “trailer” approach, we have intentionally withheld detailed subsegment breakouts, regional/application-level share tables, and exact per-grade demand forecasts—data that our clients consistently use to validate specific capex and go-to-market decisions. Those granular data sets, supplier scorecards, and scenario tables are included in the full report and the downloadable spreadsheets that support investment modeling.
Next steps — where to go for the complete intelligence
If you are preparing capital allocation, M&A screens, or product roadmaps for 2026, PW Consulting’s full Chlorinated Polyolefin Market study provides the operative datasets, validated unit-cost models, and prescriptive playbooks your leadership team needs. Access to the full report unlocks the subsegment granularity and supplier-level metrics required to execute with confidence.
For a tailored briefing or to obtain the complete dataset and scenario models, connect with our industry practice. Our team will walk you through how the market sizing, cost curves, and supplier risk matrices translate into actionable decision triggers for your 2026 plans.
For detailed analysis of this topic, please visit the official page: Chlorinated Polyolefin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


