



PW Consulting: Polysilicon Market to Hit USD 19.03 Billion by 2032, Driven by 13% CAGR

Polysilicon Market 2026: Strategic Preview for Executive Decision-Making
Executive overview
As 2025 closes with a global polysilicon market worth approximately USD 8.1 billion (base year), the sector is entering a phase of accelerated structural change. Our modelling shows the market expanding at a robust 13.0% CAGR over the 2026–2032 forecast window, with a projected market size approaching USD 19.0 billion by 2032. Those headline numbers capture more than cyclical upswings: they reflect technology transitions, policy-driven reshoring, and a rebalancing of the supply chain that will directly influence capital allocation, procurement strategy, and M&A activity in 2026.
Polysilicon Market
Why this matters for 2026 corporate strategy
-
Timing and scale of investment: With mid‑decade demand accelerating, decisions on greenfield capacity, tolling agreements, or brownfield upgrades made in 2026 will determine competitive positioning for the next decade. The forecasted trajectory implies that marginal capacity additions can shift price dynamics and utilization rates materially.
Polysilicon Market -
Supply security and sourcing premiums: Policymakers and large downstream buyers are increasingly valuing on‑shore or allied-source polysilicon to mitigate geopolitical and trade risk. Corporates that secure diversified offtake or strategic equity positions in upstream capacity in 2026 will reduce disruption risk and command pricing optionality.
Polysilicon Market -
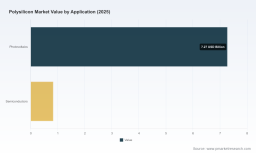
Technology and product segmentation: Demand bifurcation between standard PV-grade material and high‑purity semiconductor-grade polysilicon highlights different investment profiles. Technology choice (e.g., fluidized‑bed vs. Siemens vs. silane-process approaches) will influence CAPEX intensity, energy consumption, unit cost, and emissions performance — all increasingly material to customers and regulators.
-
Compliance and ESG premiums: Low‑carbon/low‑water polysilicon is shifting from niche to value‑add. Buyers are prepared to pay for lower lifecycle emissions and traceable supply chains; producers that can certify and scale such production in 2026 will access a growing premium pool.
Market dynamics in plain terms
The recent historical phase (2020–2025) saw rapid recovery and expansion from a smaller base, driven principally by photovoltaic deployment and replenishment cycles in semiconductor wafer supply chains. The coming period is defined by three intersecting dynamics: (1) demand growth from both energy and electronics applications; (2) concentrated feedstock and capital intensity of production; and (3) policy interventions that are actively reshaping trade flows and investment incentives. Together these factors create both upside opportunity and execution risk for corporate decision‑makers in 2026.
What the PW Consulting polysilicon study delivers (practical deliverables)
Our full report is structured for operational use by strategy, procurement, and corporate development teams. Highlights include:
-
Actionable market sizing and scenario-based forecasts (2026–2032) with sensitivity to price, capacity additions, and policy shocks.
-
Supply‑chain heat maps identifying pinch points from quartz feedstock to specialty gases and power, and practical mitigation options (contracting, vertical integration, buffer inventory strategies).
-
Technology and cost‑curve analysis comparing dominant process routes across CAPEX/OPEX, energy intensity, water use, and emissions; includes benchmarked plant economics to support investment appraisal.
-
Regulatory scenario playbooks that quantify potential impacts of trade measures and critical‑minerals policy on sourcing cost and lead times.
-
Procurer’s toolkit with template RFP language, offtake negotiation levers, and hedging structures tailored for polysilicon buyers in 2026.
-
Competitive intelligence dossiers on key producers, including strategic posture, technology strengths, and likely capex trajectories — designed to support partner selection, JV negotiations, and M&A diligence.
-
Deal and integration checklists for investors targeting upstream assets, including liabilities to consider, common integration pitfalls, and recommended governance models.
Competitive landscape — what to watch in 2026
The upstream market exhibits moderate concentration: a competitive triad controls a meaningful share of supply, while the top five firms together represent a clear majority. This structure produces strategic leverage for vertically integrated players and creates pockets of scarcity that agile mid‑market entrants can exploit.
Key corporate archetypes and strategic implications:
-
Established European chemical players: Companies with deep process know‑how and established quality credentials are investing to improve efficiency and reduce emissions. Their options in 2026 include premium pricing for differentiated product and selective capacity upgrades rather than aggressive greenfield expansion.
-
North American specialist producers: Domestic capacity addition and modernization efforts are responding to downstream demand for local sourcing. These players are attractive partners for offtake or co‑investment for companies prioritizing on‑shore supply in 2026.
-
East Asian manufacturers: Firms combining scale and process innovation continue to exert cost pressure on the global market. Their strategic playbook often includes volume‑driven contracts, integrated feedstock sourcing, and selective overseas investments.
-
New entrants and resource integrators: Developers focused on cluster economics or integrated silicon value chains are pursuing rapid capacity deployment. These projects can create localized oversupply if not matched with demand commitments — a critical variable for 2026 planning.
Recent developments and their implications
-
Targeted capacity investments and facility upgrades announced in late 2025 and early 2026 indicate that producers are responding to both projected demand and policy signals. These moves increase near‑term supply risk if multiple large projects come online contemporaneously; conversely, tied financing and strategic partners reduce that risk and are therefore worth prioritizing in offtake negotiations.
-
Downstream firms investing in domestic manufacturing capacity signal a willingness to pay jurisdictional or traceability premiums. Buyers planning procurement for 2026 should quantify their tolerance for such premiums versus the risk of import disruption.
-
Regulatory activity — notably trade investigations and critical‑materials scrutiny — is elevating the value of provenance and supplier diversification. Firms should run regulatory-stress scenarios on contracted supply and capex plans this year.
Strategic playbook for 2026
-
Prioritize supply diversification now: secure staggered offtake across geographies and process types to reduce single‑point failure and capture quality optionality.
-
Design CAPEX with flexibility: favor modular or phased buildouts and technology choices that allow toggling between product grades as market mix evolves.
-
Pursue strategic partnerships: equity offtakes or minority stakes in upstream projects can secure feedstock and create priority access without full greenfield exposure.
-
Incorporate regulatory contingencies into price and delivery terms: include pass‑throughs and renegotiation clauses tied to trade remedies or critical‑materials tariffs.
-
Differentiate on sustainability metrics where possible: low‑emissions polysilicon programs can underpin premium contracts and reduce future stranded‑asset risk.
Where PW Consulting adds value
Our polysilicon study blends granular operational analysis with transaction‑grade commercial insights. We combine plant‑level economics, supply‑chain mapping, and scenario modelling to produce decision‑ready outputs: investment memos, procurement playbooks, and M&A due‑diligence packages. The intention is to move clients from high‑level awareness to executable strategies in the first half of 2026.
Next steps (how to use this preview)
-
Use this brief to align 2026 capital allocation and procurement priorities across business units.
-
Request the full report to access detailed regional and application demand curves, per‑tonne cost curves, plant‑level capacity tables, and downloadable NPV templates needed for transaction appraisal.
-
Engage PW Consulting for a 90‑day sprint: we will run a customized scenario analysis, refine your sourcing strategy, and support negotiations or diligence on priority targets.
The 2026 decision window is narrow: early movers who combine disciplined commercial terms with selective upstream exposure will capture the majority of strategic upside while limiting downside. For the detailed datasets, executable templates, and company‑level dossiers that underpin these conclusions, please consult the full Polysilicon Market report available on our publications page.
For detailed analysis of this topic, please visit the official page: Polysilicon Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


