



PW Consulting: Underwater Pelletizer Market to Reach USD 1,087.66M by 2032 at 4.0% CAGR

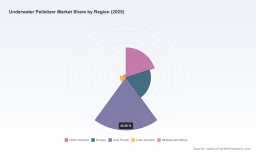
Underwater Pelletizer Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s senior industry analyst, I present a forward-looking primer on the Underwater Pelletizer market designed to inform capital allocation, product strategy and supply-chain decisions across 2026. This article distils the strategic imperatives from our full market study (base year 2025, historical window 2020–2025, forecast period 2026–2032) to give executives a clear line-of-sight on market momentum, structural constraints and competitive positioning — while intentionally reserving the granular subsegment tables and model outputs for the full report.
Underwater Pelletizer Market
Why this market matters in 2026
-
Underwater pelletizing remains a foundational technology for polymer producers, compounding houses and recyclers. After a period of volatility from 2020–2024, the market stabilized through 2025 and is set to grow at a steady compound annual growth rate of approximately 4.0% across our 2026–2032 forecast horizon. This growth is driven by a mix of recycling mandates, demand for higher-spec polymer formulations and continued investment in integrated compounding-pelletizing solutions.
Underwater Pelletizer Market -
From a portfolio perspective, the market is neither a hyper-fragmented long tail nor a tightly consolidated oligopoly: the top three vendors account for under half of market share, while the top five capture just over half. That structure rewards technically differentiated propositions — precision engineering, integrated systems and digital enablement — and creates repeatable opportunities for mid-sized specialists to scale through geographic expansion and channel partnerships.
Underwater Pelletizer Market
Market trajectory — the headline numbers
Our benchmarking uses 2025 as the base year. In that year the total market reached a level that confirms recovery and re-investment trends seen since 2022. At a 4.0% CAGR across the forecast window, the market is projected to expand meaningfully by 2032, reflecting sustained demand for pelletizing capacity upgrades, recyclate handling and new-material processing. These headline figures should be read as directional inputs for capacity planning, M&A screening and R&D prioritisation rather than as a substitute for the detailed segment-level tables available in the full study.
Structural dynamics that will shape supplier and buyer strategies
-
Capital intensity and adoption barriers. Our sector intelligence shows that a significant share of processors identify high initial equipment cost as the primary gatekeeper to adopting underwater pelletizers. For purchasers, this means procurement decisions increasingly hinge on total cost of ownership (TCO) models that account for energy, maintenance and downtime — not just upfront CAPEX.
-
Labor and skills. Maintenance skill shortages are a non-trivial constraint for nearly a quarter of processors. Buyers are therefore preferring systems with lower skill-dependency (modular designs, guided maintenance software) or vendors offering bundled service contracts and local training.
-
Energy and sustainability. Energy-optimized pumps and motor systems are now mainstream: our analysis finds that a substantial portion of new systems incorporate designs that can reduce energy use by nearly a fifth. This is both a cost lever and a regulatory/sustainability differentiator — manufacturers that can demonstrate validated energy savings and lower coolant burdens will gain procurement advantage.
-
Consumables and metallurgy. Critical wear components such as pelletizer knives are increasingly manufactured from premium tool steels, extending service intervals and improving pellet quality. This technical detail matters: it alters spare-parts strategies and influences lifetime TCO calculations for technical buyers.
Strategic implications for 2026 decision-making
-
For OEMs: prioritize modularity and digital service layers. Given the market’s growth profile and the concentration dynamics, OEMs that combine mechanical robustness with smart-sensor integration and remote diagnostics will capture higher-margin aftermarket revenue.
-
For processors: adopt TCO-driven procurement and staged modernization. Instead of wholesale replacement, incremental upgrades (energy-optimized pumps, improved knife metallurgy, smart monitoring) typically deliver faster payback and lower implementation risk.
-
For investors and M&A teams: the market structure points to attractive roll-up opportunities in regions with fragmented local supply. Targets should be assessed on the basis of installed-base service revenues, intellectual property around pellet quality, and proximity to high-growth polymer segments such as recyclates and bioplastics.
-
For sustainability leads: prioritize vendors that can substantiate energy savings and reduced coolant footprints. These operational efficiencies often align directly with carbon and cost reduction targets and can unlock incentives in jurisdictions with green procurement policies.
Competitive landscape — who to watch
The competitive field combines global system integrators, specialist pelletizer manufacturers and regional machine builders. Key vendors profiled in the full report illustrate the range of go-to-market strategies and technology emphasis:
-
MAAG Group (Switzerland) — notable for precision-focused product lines and lab-scale systems designed to minimize fines and optimize pellet geometry.
-
Nordson Corporation (USA) — recognized for robust underwater pelletizer platforms that serve high-density pellet applications and complex polymer blends.
-
Coperion GmbH (Germany) — strong in thermoplastic, sticky-product and high-throughput polyolefin applications; their UG series targets throughput and process stability.
-
ECON GmbH (Germany) — active in both lab and industrial systems, with designs tailored for low-durometer and challenging pelletizing tasks.
-
Farrel Pomini and Davis-Standard (USA) — positioned as integrated compounding and pelletizing solution providers, appealing to large compounders seeking single-vendor responsibility.
-
Specialist intelligent-sensor vendors (e.g., IPS) and a cohort of established Chinese OEMs (including Cowell, Wuxi Huachen, Jieya, USEON, Xinda and others) — the latter offer cost-competitive systems and are increasingly present in export markets.
Recent market activity underscores these strategic moves: product launches and trade-show demonstrations in 2025–2026 have centered on precision blade adjustment, intelligent control architectures and new structural designs for reliability. These events are early indicators of where differentiation will occur over the next 18–24 months.
What our full report delivers — practical, transaction-ready outputs
To translate strategy into action, our full Underwater Pelletizer Market study provides a practical toolbox rather than only descriptive analysis. Highlights include:
-
Vendor benchmarking framework and CR-based competitive maps that show concentration patterns and adjacency risks.
-
TCO and payback templates (CAPEX/OPEX models) adapted to typical processing profiles — enabling site-level procurement comparisons.
-
Scenario-based capacity planning templates for recycling-led versus virgin-polymer demand pathways across the 2026–2032 horizon.
-
A procurement playbook that addresses procurement levers: service bundling, performance SLAs, spare-parts pooling and upgrade pathways.
-
M&A screening criteria and a priority-target shortlist methodology for roll-up strategies in under-served regions.
-
Technology adoption checklist (mechanical, hydraulic, metallurgical and digital layers) to help engineering and operations teams validate supplier claims during pilot tests.
How C-suite teams should use this intelligence in 2026
-
CEOs and Heads of Strategy: use the market growth trajectory and concentration metrics to set inorganic growth thresholds and to prioritise regions/verticals for expansion. Treat TCO-led product roadmaps as a top-three strategic vector for near-term differentiation.
-
CFOs: insist on scenario-modeled CAPEX approvals that incorporate energy-savings and service revenue upside. Allocate pilot budgets for energy-optimized retrofits that can de-risk larger rollouts.
-
CTOs and Plant Heads: deploy the procurement playbook and technology adoption checklist during factory acceptance tests. Prioritise knife metallurgy and pump efficiency as high-impact upgrade items.
-
Business Development and Sales Leaders: align go-to-market propositions around bundled service offerings and demonstrable lifecycle cost advantages rather than purely price-driven competition.
Final perspective — the strategic payoff
For organisations that act in 2026, the strategic payoff lies in three converging trends: steady market expansion at an attractive CAGR, operational savings unlocked by energy and materials innovations, and competitive mobility enabled by digital services and modular designs. The market is neither static nor purely commoditised; there is room for margin uplift through technical differentiation, aftermarket excellence and disciplined M&A. However, to capture that value you must pair macro-market timing with rigorous site-level financials and a pragmatic rollout sequence.
PW Consulting’s full Underwater Pelletizer Market report contains the segment-level data, vendor scorecards and downloadable decision-support models that will allow your team to move from insight to procurement, investment or product strategy with confidence. For the detailed subsegment tables, regional breakdowns and the complete set of models and templates referenced here, please consult the full report on our website.
For detailed analysis of this topic, please visit the official page: Underwater Pelletizer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


