



PW Consulting: Optical Lens Edger Market to Reach USD 790M by 2032 at 5.05% CAGR

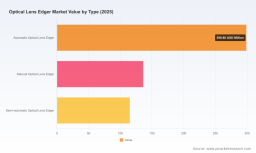
Optical Lens Edger Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As the optical manufacturing ecosystem enters 2026, the global market for optical lens edgers is moving from standalone capital equipment purchases to integrated, data-enabled production systems. PW Consulting’s latest market research — anchored on a 2025 base year and a 2026–2032 forecast window — quantifies this transition and translates it into decision-grade guidance for executives, investors, and product leaders. The headline metrics are unambiguous: a market sizing of approximately USD 550 million in 2025, and a steady compound annual growth rate (CAGR) of 5.05% through our forecast horizon, driving the market toward material expansion by the end of 2032.
Optical Lens Edger Market
Why this research matters for 2026 strategic decisions
-
Timing matters: procurement and product development decisions made in 2026 will determine competitive positioning throughout the decade. With projected growth and the accelerating adoption of automation and AI-enabled finishing, capital allocation and go-to-market choices taken now compound in return and risk exposure.
Optical Lens Edger Market -
Regulatory and supply-side timelines are non-linear. FDA 510(k) pathways, tightened EU MDR enforcement, and ISO 13485 requirements introduce multi-quarter to multi-year delays for new models. Our analysis quantifies these delay factors and models their impact on time-to-revenue scenarios — critical for budgeting R&D and commercial launches in 2026.
Optical Lens Edger Market -
Market consolidation is real but incomplete. The top tier of vendors controls a majority share of the market, creating distinct opportunities for both scale and niche players. Our competitive mapping identifies where scale offers defensibility and where focused innovation or service models can disrupt incumbents.
What the report delivers — practical, actionable sections
-
Robust market sizing and forecast model: granular historical baseline (2020–2025), 2026–2032 scenario matrices, and sensitivity tests anchored to technology adoption and regulatory shocks.
-
Decision-ready playbooks: capital purchase vs. service-leasing analyses; ROI calculators for automation upgrades; operating models for in-house finishing vs. outsourced lab networks.
-
Technology and product benchmarking: feature parity charts, throughput-to-footprint trade-offs, and integration roadmaps for AI tracing, CNC precision, and block-less finishing systems.
-
Regulatory roadmap and compliance checklist: time-lined pathways for FDA and EU filings, recommended documentation practices to compress approval cycles, and procurement timing to avoid regulatory-driven stockouts.
-
Supply chain and cost-risk mapping: vendor concentration analysis for critical consumables, lead-time impact modeling, and contingency sourcing strategies for cornerstone inputs such as diamond-abrasive wheels.
-
M&A and partnership screen: target profiles for bolt-on acquisitions, JV criteria for market access, and commercial partnership templates for integrating ocular data platforms and in-store finishing suites.
-
Commercial and service playbooks: pricing ladders, recurring revenue mechanics for maintenance & software subscriptions, and field-service capacity planning tied to geographic growth scenarios.
Competitive landscape — leaders, challengers, and strategic moves to watch
Our competitive review synthesizes product capabilities, go-to-market models, and recent strategic moves across the supplier ecosystem. Several vendor archetypes emerge: global platform leaders with integrated lab-to-clinic suites; specialized OEMs focusing on high-throughput lab automation; and agile players targeting in-store finishing with compact, ease-of-use units.
-
NIDEK Co., Ltd. — A platform leader originating from optics and diagnostics, NIDEK continues to push automation and AI into finishing workflows. Their recent launches broaden the lens-processing suite and signal a push toward end-to-end shopfloor automation. For partners and buyers, NIDEK’s roadmap raises the bar on integration expectations and lifecycle services.
-
Coburn Technologies, Inc. — Known for CNC-based precision and tooling, Coburn’s strength lies in repeatability and retrofit friendliness. Their modular CNC architecture offers a pragmatic upgrade path for labs balancing throughput and capital constraints.
-
MEI System — MEI’s block-less and block-based systems cater to high-volume labs aiming for low cycle times. Their design choices highlight a trade-off: throughput optimized for large labs versus flexibility demanded by mixed-channel finishing.
-
Shanghai Supore Instruments Co., Ltd. — As a supplier with broad instrument portfolios, Supore’s competitiveness is tied to price-performance and channel reach. Their full-line offering positions them as a low-friction partner for labs upgrading multiple workstations.
-
Luneau Technology Group (Briot) — Focused on patternless edgers for in-office finishing, Briot’s 3D tracing and compact designs enable opticians to offer fast-turn services. They exemplify the in-store convenience model that is pressuring traditional lab volumes.
-
Essilor Instruments (EssilorLuxottica) — Their compact, precision in-store units and recent acquisition activity reflect a broader vertical play: combining retail footprint and processing technology to reclaim margin across the value chain.
Recent strategic moves — new product introductions and acquistions in 2025–2026 — underscore several market dynamics: consolidation of optical processing capabilities into larger eyecare platforms, acceleration of AI and automation integration, and targeted acquisitions to access data platforms and robotics. These moves compress time-to-market for combined offerings and raise switching costs for laboratory networks.
Operational and regulatory risk vectors to monitor in 2026
-
Regulatory timelines: FDA 510(k) pathways and EU MDR enforcement are extending product development cycles. For companies planning launches in or after 2026, allocate an additional 12–18 months for clearance and certification activities in medical device jurisdictions.
-
Quality systems: ISO 13485 remains a gating factor for OEMs and contract manufacturers. Early investment in compliant QMS accelerates distributor approvals and reduces commercial friction.
-
Supply concentration: Critical consumables — notably premium diamond-abrasive wheels — have extended lead times and limited vendor diversity. Our supply-risk model shows that single-source reliance can create operational stoppages; 2026 procurement strategies must include multi-sourcing or inventory hedging to avoid throughput loss.
-
Market concentration: The market exhibits moderate concentration among the top players, with the three largest vendors commanding a majority share and the top five controlling an even greater portion. This creates both a moat for incumbents and an opening for differentiated entrants focused on software, service, or niche workflows.
Strategic recommendations for executives in 2026
-
Prioritize modular automation investments: Opt for platforms that enable phased upgrades (e.g., retrofittable CNC cores, software-enabled tracing) to align capital deployment with demand realization and regulatory milestones.
-
Lock critical supplies and diversify sources: Secure multi-year agreements or develop secondary suppliers for long-lead consumables to protect throughput. Consider nearshoring or strategic stocking for high-impact components.
-
Embed regulatory strategy into product roadmaps: Start FDA and MDR preparatory activities early. Build regulatory costs and time into NPV and payback models before committing to large-scale manufacturing ramps.
-
Capture recurring revenue opportunities: Expand service contracts, consumable subscriptions, and software licensing tied to AI-enabled shape libraries and diagnostic integrations to smooth revenue and increase lifetime customer value.
-
Use M&A and partnerships selectively: Target acquisitions that fill capability gaps (robotics, AI, ocular data platforms) rather than chasing geographic scale alone. Partnerships with retail chains or diagnostic platforms can rapidly accelerate installed-base monetization.
-
Differentiate through integration: The competitive frontier is shifting from raw throughput to integrated workflows — linking ocular data, edging, tinting, and finishing into frictionless customer experiences. Invest in open APIs and service ecosystems.
How to use this preview
This preview is designed to crystallize the strategic stakes for 2026 decisions. PW Consulting’s full report contains the detailed segmentation models, scenario tables, vendor scorecards, and downloadable tools referenced above — information that we intentionally reserve for the full deliverable to preserve its decision-utility. If your 2026 plan includes capital expenditure for finishing cells, product launches that target medically-regulated markets, or M&A activity, the full dataset and playbooks will materially change the timing and structure of those initiatives.
In summary: with a market base in 2025 near USD 550 million and a steady CAGR of about 5% through 2032, the optical lens edger market is mature but actively reconfiguring. Success in 2026 will favor organizations that couple disciplined regulatory and supply-chain planning with modular automation, service-led monetization, and strategic partnerships. PW Consulting’s complete study maps those choices to financial outcomes and operational timelines to help you convert foresight into executable advantage.
To access the full analysis, scenario models, and vendor playbooks, visit our report page for the Optical Lens Edger Market — the complete intelligence you will need to execute confidently in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Optical Lens Edger Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


