



PW Consulting: DNA Forensic Market to Hit USD 328M by 2032 with 6.98% CAGR

DNA Forensic Market 2026 — A Strategic Preview for Executives and Practitioners
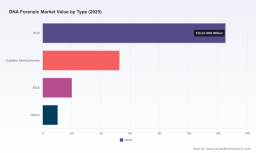
PW Consulting’s new DNA Forensic Market study (base year 2025; historical 2020–2025; forecast 2026–2032) distills the evidence base senior leaders need to make high-conviction decisions in 2026. Our macro findings show a market that expanded from roughly 155 Million USD in 2020 to about 208 Million USD in 2025 and is forecast to reach approximately 328 Million USD by 2032, reflecting a compound annual growth rate of 6.98% over the forecast window. Market concentration is meaningful: the top three players account for just over half of industry revenues (CR3 ≈ 52.5%), while the top five approach roughly 68% (CR5 ≈ 68.2%).
DNA Forensic Market
Why this report should be part of your 2026 decision toolkit
- Translate growth forecasts into capital plans: understand where to allocate CapEx for sequencing platforms, Rapid DNA investments, and lab automation to align with demand projections and procurement windows.
- Navigate new compliance burdens: convert regulatory shifts into operational checklists and vendor specifications that reduce audit risk and procurement friction.
- De-risk supply chains: identify pinch points in consumables and reagents and build contingency strategies for pricing and inventory.
- Calibrate M&A and partnership strategies: use concentration and capability maps to find bolt-on targets, strategic partners, or acquisition gaps for 12–24 month timelines.
- Improve pricing and reimbursement positioning: benchmark unit cost inflation and grant opportunities to shape tender responses and budget requests.
What the report delivers — practical, actionable content
We structure the research to be operational from day one. Highlights of the deliverables include:
DNA Forensic Market
- Scenario-based market sizing and demand modeling (2026–2032) with downloadable Excel models that allow you to test assumptions for adoption rates, reagent cost inflation, and customer segment elasticity.
- Technology decision framework comparing PCR, capillary electrophoresis, NGS, Rapid DNA and complementary workflows — including throughput, turn-around-time, validation complexity and total cost of ownership (TCO) templates.
- Regulatory impact matrix: direct mapping of new and updated standards (including FBI Quality Assurance Standards updates) to lab policies, consumable requirements, and procurement specifications.
- Vendor capability assessments and sourcing playbooks: profiles, scorecards and negotiation levers for leading suppliers and OEMs plus an RFx checklist tailored to forensic procurement rules.
- Operational playbooks for forensic labs: sample handling, contamination reduction (ISO 18385 implications), evidence chain-of-custody protocols, and Rapid DNA integration pathways.
- Cost-pressure and margin sensitivity analysis: models that capture recent reagent and extraction cost inflation, labor impacts, and the operational levers available to preserve margins.
- M&A and partnership screening: priority target archetypes, integration risks, and expected synergies for acquisitive and non-acquisitive players.
Market dynamics shaping 2026 strategy
Several converging forces will determine winners and losers over the next 18–36 months:
DNA Forensic Market
- Regulatory tightening. The FBI’s updated Quality Assurance Standards, now effective, raise the bar on consumable controls, environmental contamination mitigation and validation regimes. Practical consequence: buyers will increasingly require ISO 18385-compliant consumables and documented performance checks, and labs participating in national databases must formalize data-ownership and Rapid DNA governance protocols.
- Cost inflation across the value chain. Forensic genetic genealogy testing and consumables have seen marked price pressure in recent years; for example, sector analysis shows an escalation in per-case forensic genealogy testing costs, driven by reagent scarcity and supply chain disruption. DNA extraction input costs similarly jumped materially between 2021 and 2025. These trends necessitate unit-cost redesigns and re-negotiated commercial terms with suppliers.
- Technology convergence. NGS and mass parallel sequencing are moving from specialized use-cases into mainstream workflows, while Rapid DNA systems are maturing into validated tools for front-line deployments. Organizations must decide when to standardize on new platforms versus maintaining mixed-technology portfolios.
- Public-sector funding variability. Targeted grants and programs (examples exist at state levels) create episodic demand spikes for high-cost analyses like forensic genetic genealogy; procurement strategies should include grant-readiness and flexible resourcing models to capture these opportunities.
- Concentration and competitive dynamics. With a moderate-to-high market concentration, established vendors maintain strong negotiating power, but there is also room for niche innovators to win through specialized workflows, service models or forensic genealogy capabilities.
Competitive landscape — profiles and strategic implications
Below are concise strategic reads on the core players to watch and the moves that will matter in 2026. These are synthesized to inform partner selection, procurement strategies and competitive threat assessment.
- Othram (The Woodlands, Texas) — Strengths: forensic genetic genealogy and full-service case resolution offerings combining STR, SNP and genomic sequencing. Strategic implication: the firm’s end-to-end service model is a force-multiplier for agencies lacking in-house genealogy expertise; public-sector partnerships (including high-profile state engagements announced in 2026) create pathway risks and opportunities for labs and vendors that want to collaborate rather than compete.
- Copan Group (Brescia, Italy) — Strengths: sample collection consumables engineered for direct DNA collection and contamination control. Strategic implication: with regulators emphasizing ISO-compliant consumables, Copan’s ISO 18385-aligned products are positioned to capture procurement mandates; buyers should factor premium pricing against contamination risk reduction.
- QIAGEN (Venlo, Netherlands) — Strengths: integrated investigator kits and digital PCR quantification platforms. Strategic implication: QIAGEN’s strength in upstream sample prep and quantification enables labs to drive reproducibility and throughput; consider multi-year reagent contracts to stabilize pricing exposure.
- Promega Corporation (Madison, Wisconsin) — Strengths: STR and NGS kit portfolio for human identification. Strategic implication: Promega is a logical partner for labs transitioning to mixed STR/NGS workflows; procurement teams should negotiate validation support and bundle pricing for kits plus engineering services.
- Thermo Fisher Scientific (Waltham, Massachusetts) — Strengths: established forensic genotyping kits and sequencing systems. Strategic implication: Thermo’s platform scale and service network make it a default choice for large labs; organizations must weigh long lead-times and preferred-vendor lock-in against total lifecycle cost advantages.
- Illumina (San Diego, California) — Strengths: NGS sequencing platforms and kit ecosystems. Strategic implication: Illumina’s throughput leadership is attractive for labs planning high-volume NGS adoption, but buyers should plan for reagent lifecycle management and certification pathways to satisfy accreditation bodies.
Recent developments that alter execution risk and timing
- April 2026: A high-profile state-level partnership with a full-service forensic genealogy provider signals accelerating public adoption of outsourced genealogy services for cold-case resolution; expect more jurisdictions to announce similar collaborations in 2026.
- Effective mid-2025: FBI Quality Assurance Standards updates carry operational mandates—especially around consumable compliance (ISO 18385), Rapid DNA performance checks and data ownership practices for participating laboratories—requiring immediate policy and procurement updates in calendar-year 2026.
Strategic recommendations for 2026
- Prioritize compliance-forward sourcing. Make ISO 18385 conformity and performance-validation support non-negotiable in all consumable and instrument RFPs.
- Lock short-term reagent stability. Pursue staggered multi-supplier contracts and safety-stock agreements to insulate against input-cost spikes and shipment volatility.
- Adopt a hybrid technology pathway. Pilot Rapid DNA in controlled use-cases while expanding NGS capacity for complex identifications — use our TCO templates to quantify the break-even point for automation and platform consolidation.
- Monetize grant and program windows. Build a small, agile team to track and win state and federal grants that fund forensic genealogy and lab modernization projects.
- Use competitive tension to lower barriers. Leverage the market’s moderate concentration: invite at least three qualified vendors for strategic deals and insist on field-validation commitments as part of commercial terms.
- Prepare M&A playbooks. For strategic acquirers, target firms that close capability gaps (service providers, niche consumable makers, or validated Rapid DNA integrators) rather than chasing scale alone.
How PW Consulting’s report helps you act quickly
This study is intentionally practical: it couples high-level trend maps with modular tools you can deploy in procurement, budgeting and compliance workflows. We deliberately follow a “trailer” approach in public summaries — illustrating depth and methodology while withholding the full confidential segmentation tables and downloadable annexes to preserve competitive value for subscribers. If your priority is rapid operationalization, the full report includes the Excel models, validation checklists, RFx templates, and vendor scorecards referenced above.
For executives, lab directors and procurement leads, the 2026 inflection in DNA forensics is less about if change will happen and more about whether you are positioned to shape outcomes. Use the forecast and the playbooks to move from reaction to design: align CapEx to projected demand, lock compliance into supplier contracts, and convert one-off grants into sustainable capability gains.
To access the complete dataset, granular segmentation, and the downloadable operational annexes that power tactical planning, visit the PW Consulting DNA Forensic Market study webpage for subscribers and clients.
For detailed analysis of this topic, please visit the official page: DNA Forensic Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


