



PW Consulting: Aroma Chemicals Market Poised for 5.45% CAGR Through 2032

Aroma Chemicals Market 2026 Strategic Brief: Positioning for Growth and Resilience
Executive snapshot
As the fragrance, flavor and personal-care value chains continue to reconfigure around sustainability, traceability and regional supply resilience, the aroma chemicals market enters 2026 from a position of steady expansion and structural change. Our PW Consulting analysis uses 2025 as the base year and shows the global market expanding from approximately USD 140 million in 2020 to roughly USD 180 million in 2025, with a projected compound annual growth rate (CAGR) of about 5.45% over the 2026–2032 forecast window — taking the market toward the high two-hundreds million-dollar range by 2032. These macro dynamics create a discrete set of strategic dilemmas for manufacturers, ingredient buyers and investors as they plan capex, contract terms and M&A activities for calendar-year 2026 and beyond.
Aroma Chemicals Market
Why this study matters for 2026 decision-making
- Aligning capacity with changing demand vectors. A mid-single-digit CAGR disguises important reallocation of demand across molecule families and applications. Executives planning production runs, debottlenecking investments or brownfield expansions must reconcile steady aggregate growth with shifts in end-use intensity driven by sustainability requirements and regulatory phase-outs.
- Pricing and margin management in a volatile upstream. Raw-material sourcing and certification costs are becoming a principal margin lever. Buyers and sellers who assume historical cost relationships will misprice risk in 2026 unless they model certification-driven premiums and tariff volatility.
- Strategic M&A and partnership timing. With the market neither hyper-consolidated nor atomized — the top three suppliers account for a significant minority share and the top five push that share higher — selective acquisitions and partnerships remain a high-return play for firms aiming to scale capability in biobased molecules or regional supply chains.
What the PW Consulting report delivers (operationally actionable)
The full study is designed as a decision-support toolkit for corporate strategy, procurement and corporate development teams. Key practical deliverables include:
Aroma Chemicals Market
- Market sizing and validated topline forecasts (base year 2025) with scenario sensitivity to feed directly into budgeting and capacity-utilization models.
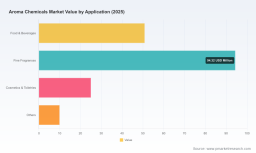
- Segment maps and demand-driver matrices that translate macro growth into product- and application-level pipeline forecasts (note: detailed regional and application splits are contained in the full report).
- Supply-chain heatmaps showing raw-material sourcing routes, cost-driver nodes and likely pinch points under alternative geopolitical and climate scenarios.
- Supplier scorecards and a playbook for third-party certification (ISCC PLUS, TÜV Rheinland reduced product carbon footprint) to support commercial negotiation and product positioning.
- Regulatory and ingredient-level risk assessment: an operational checklist for reformulation, labelling and compliance timelines tied to IFRA/REACH changes.
- Deal-screening templates and valuation comparables tuned to aroma chemical margins, concentration metrics and recent transactions in the sector.
Competitive landscape — structure and strategic moves
The aroma chemicals market displays moderate concentration: the three largest global players hold a meaningful minority share of the market while the top five collectively increase that share further. This structure favors companies that combine manufacturing scale with differentiated product portfolios and certification credentials.
Aroma Chemicals Market
- Givaudan (Vernier, Switzerland) — continues to take a dual approach of capacity build and sustainability innovation. Recent investments include a new fragrances manufacturing facility established in Mexico (April 2025) and strategic biotech partnerships (August 2025) to accelerate renewable-molecule development.
- Privi Speciality Chemicals (Mumbai, India) — executing a capacity-expansion trajectory with targeted debottlenecking investments to scale pinene-derived output; this positions the company strongly on raw-material adjacencies where pine-derived intermediates remain material to the global supply mix.
- LANXESS (Cologne, Germany) — recognized for high-purity, nature-identical aroma chemicals and a growing portfolio of sustainable ingredients; their product breadth and European manufacturing footprint place them centrally in customers’ sustainability sourcing strategies.
- BASF, IFF and other strategic players — recent product launches (biodegradable lines) and acquisitions underscore a trend: traditional chemical majors and fragrance firms are either vertically integrating or partnering to secure sustainable feedstocks and market access in growth regions.
- Regional manufacturers and specialists — companies across India, the U.S., China, Egypt and Latin America provide competitive depth in both natural and synthetic molecules. These players are critical as tactical suppliers for formulation flexibility, regional lead times and spot-volume needs.
Collectively, these competitors illustrate three playable strategies in 2026: (1) scale + certification leadership, (2) niche specialization in high-value aroma molecules, and (3) regional supply mastery leveraging cost and logistic advantages. The optimal choice depends on capital availability, customer relationships and desired margin profile.
Raw materials, certification and regulatory inflection points
- Feedstock realities. Crude sulfate turpentine (CST) from pine trees continues to underpin pinene-derived chemistry — industry sources estimate it supplies a material portion of global output for those molecules. That dependence exposes producers to forestry supply dynamics, processing yields and bio-certification requirements.
- Certification and price premium. ISCC PLUS bio-based certification and emerging customer mandates are creating premium buckets for certified terpenes and other biobased molecules, particularly in European fragrance markets. Firms that internalize certification costs and can demonstrate chain-of-custody will capture differentiated margin.
- Regulatory trajectories. IFRA and REACH-driven reformulations continue to accelerate the phase-out of legacy nitro-musks and drive adoption of safer alternatives. Parallel to chemical safety constraints, carbon footprint verification methods (e.g., TÜV Rheinland’s reduced product carbon footprint) are migrating from optional to contractually required for many global buyers.
Geopolitical and macro risks that will matter in 2026
- Trade policy volatility. Recent reciprocal tariff policies implemented in 2025 are already increasing landed costs for imported aroma chemicals in certain markets; procurement teams must build tariff stress into supplier scorecards and explore nearshoring or hedged contract structures.
- Certification-driven regionalization. As North-South policy differentials on sustainability regulation evolve, expect sourcing patterns to regionalize: buyers will prefer certified local supply to minimize Scope 3 exposure and logistical risk.
- Raw-material shocks. Weather, forestry policy and processing constraints can create episodic price spikes in pine-derived intermediates and other botanical feedstocks. Scenario planning that models 6–12 month feedstock shocks is now a board-level priority.
Strategic plays for 2026 — what winning looks like
- Capex and debottlenecking to meet premium demand. Prioritize investments that increase capacity for certified or nature-identical molecules where price realizations exceed legacy product lines.
- Certification as a go-to-market lever. Treat ISCC PLUS and reduced-carbon-footprint certification not merely as compliance costs, but as revenue-enabling assets that open shelf-space and preferred supplier lists.
- Flexible sourcing and dual-supplier strategies. Combine long-term contracts for core molecules with short-term spot arrangements to manage margin volatility and avoid production downtime during raw-material dislocations.
- M&A with capability overlays. Target sellers that add either regional logistics strength, specialty molecule know-how, or certification credentials rather than purely incremental volume.
- Customer co-development and transparency. Embed product carbon and provenance claims into co-development agreements with key brands to lock in customer loyalty and reduce churn risk as regulations tighten.
Recent industry events that should shape your 2026 playbook
- Givaudan’s facility groundbreaking in Mexico (April 2025) and biotech partnership (August 2025) — signals demand for regional manufacturing and renewable-molecule development.
- Privi’s production capacity increase announced mid-2025 — an example of incremental capacity scaling to serve global fragrance and flavor firms.
- BASF’s launch of biodegradable aroma chemicals (September 2025) — underscores product innovation oriented to regulatory and consumer pressure for safer, degradable molecules.
- Recent acquisition by IFF (October 2025) expanding regional footprint in Asia-Pacific — indicative of consolidation activity where scale meets local market access.
Next steps — how to use the full PW Consulting study
The concise intelligence above is intentionally directional. Our full Aroma Chemicals Market report provides the granular segmentation, regional and application splits, supplier benchmarking, transaction comparables and product-level pricing trajectories that procurement, strategy and M&A teams will need to operationalize the plays described here. If your 2026 plan includes capex decisions, contract renegotiations, or acquisition screening in aroma chemicals, the report supplies the calibrated inputs and ready-to-use templates to shorten decision cycles and reduce execution risk.
Contact your PW Consulting client adviser or visit our report page to access the full analysis, downloadable models and an executive Q&A with our lead industry analyst. For firms that must make hard choices this year — whether to expand, partner or buy — the difference between acting on high-level momentum and acting on validated, product-level intelligence will determine whether 2026 is a year of capture or attrition.
For detailed analysis of this topic, please visit the official page: Aroma Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


