



PW Consulting: Two‑Wheeler Lighting Market to Grow at 4.9% CAGR Through 2032

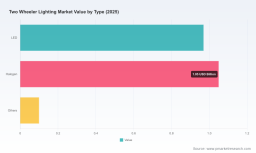
Two Wheeler Lighting Market — PW Consulting Strategic Preview (2026 Lens)
Executive preview
As two-wheeler platforms continue to evolve — electrification, tighter safety regulations, and a premiumization of lighting features — the lighting systems that serve these vehicles are shifting from commodity components to strategic modules that influence vehicle architecture, cost, and consumer perception. PW Consulting’s latest market study, anchored on a 2025 base year with a historical window of 2020–2025 and a forecast horizon of 2026–2032, synthesizes quantitative projection and qualitative strategy into a single practical resource for commercial, product, and M&A decision-makers.
Two Wheeler Lighting Market
At the macro level, the global two-wheeler lighting market grew from an approximate USD 1.72 billion in 2020 to USD 2.12 billion in 2025, and the market is modeled to continue expanding through 2032. Our baseline forecast uses a compound annual growth rate (CAGR) of 4.9% across the 2026–2032 window. These headline numbers set the scope for planning capex, R&D cadence, and channel strategies in 2026 and beyond.
Two Wheeler Lighting Market
Why this research matters for 2026 decisions
- Prioritize investments: The 2026 planning cycle is the inflection point for converting emerging lighting features (adaptive beams, DRLs, integrated sensors) into scalable production programs. Our study quantifies where and when to prioritize R&D and manufacturing investments relative to market demand trajectories.
- Regulatory preparedness: New safety standards and testing regimes introduced through 2023–2026 create compliance obligations that directly affect product roadmaps, homologation timelines, and outsourcing strategies.
- Commercial playbook: For OEM procurement and aftermarket players, the report provides go-to-market templates, margin benchmarks, and price-sensitivity scenarios calibrated to 2026 procurement cycles.
- M&A and partnership screening: We supply a reproducible scoring model to identify bolt-on targets and technology partners that can accelerate access to LED, adaptive lighting, or premium aftermarket segments.
Key market dynamics shaping 2026
- Regulatory acceleration. Policy moves over 2023–2026 have materially reshaped technical requirements and time-to-market for lighting modules. Mandatory daytime running lights (DRLs) adopted in recent years and updated safety standards for self-ballasted LED lamps require re-certification and add testing obligations for new products entering markets with rigorous standards.
- Rapid cost deflation of LED modules. Between 2019 and 2025, LED module costs for motorcycle forward lighting declined substantially (industry benchmarking indicates a c.38% step-down), driven by scale economies, intensified supplier competition, and component standardization. This cost trajectory both enables broader LED adoption and compresses supplier margins unless value is captured through integration and feature differentiation.
- Concentration and competitive position. The market exhibits a moderate-to-high level of concentration among leading suppliers, creating a channel structure in which a small set of established players capture a large portion of OEM volume while aftermarket and premium niches remain accessible to specialists.
- Technology convergence. Lighting systems are no longer discrete electromechanical parts; they are integrated with vehicle electronics, ADAS-ready architectures, and styling platforms. This convergence creates cross-functional procurement and engineering implications for wiring, ECU integration, and diagnostic support.
- Aftermarket premiumization. Independent and accessory segments continue to absorb demand for higher-performance lighting (auxiliary lamps, premium LED kits) especially in markets where riders seek both functional and aesthetic upgrades.
Competitive landscape — strategic implications
The competitive field is functionally tiered: domestic OEM suppliers serving high-volume two-wheeler manufacturers, global Tier‑1 lighting specialists, and premium niche aftermarket vendors. Key industry players illustrate distinct strategic postures that buyers and competitors should decode:
Two Wheeler Lighting Market
- Leading Indian OEM suppliers (examples): These companies have long-standing relationships with regional OEMs and demonstrate rapid product localization cycles. They excel at scale manufacturing of LED headlamps, tail lamps, and signaling devices for high-volume platforms and are progressively introducing modular LED series tailored to cost-sensitive markets.
- Global Tier‑1s (examples from Japan and Europe): Established suppliers bring advanced optics, adaptive lighting experience, and systems-integration capabilities that accelerate the introduction of higher-functionality lighting on flagship models. Their strength lies in R&D depth and global homologation know-how — valuable when planning exports or global platform programs.
- Premium aftermarket specialists (examples from North America and the UK): These firms dominate performance and auxiliary segments, targeting riders who prioritize lumen output, build quality, and installation simplicity. They operate with higher ASPs (average selling prices) and bespoke distribution channels.
For strategic buyers and sellers, the market’s structure implies three practical moves: (1) OEMs should maintain a two-track sourcing strategy—secure commodity supply while selectively partnering with Tier‑1s for integrated features; (2) suppliers should prioritize platformized product families to defend against margin erosion; and (3) aftermarket entrants can capture value via differentiated performance and branding rather than direct commodity competition.
Selected recent developments and their reading for 2026
- Product innovation: Regional suppliers have continued to launch mid‑range LED product lines aimed at bridging OEM cost and performance requirements — an example being a product launch in 2025 that signals market-ready iterations of compact, high-output LED bulbs for mass-market two‑wheelers.
- Standards updates: National and regional standards bodies revised LED safety/testing requirements and harmonized some homologation processes in 2025–2026. These regulatory changes increase entry costs and favor suppliers who have established in‑house testing capabilities or access to accredited labs.
- Training and certification: Industry training workshops in early 2026 focused on vehicle-level certification and integration practices, indicating OEMs’ attention to end-to-end compliance rather than component-only certification.
What the full PW Consulting study delivers (practical table of contents)
- Market sizing and validated forecast model (2020–2032) with scenario toggles and sensitivity drivers aligned to 2026 budgeting cycles.
- Regulatory and standards tracker with compliance checklists and implementation timelines for priority markets.
- Technology and cost curve analysis — LED, halogen legacy transitions, and emerging technologies — including component cost breakdown and long‑term supplier roadmap implications.
- Competitive landscaping with heat maps of capabilities (manufacturing, homologation, R&D), supplier risk profiles, and a five‑step partnership evaluation framework.
- Commercial playbooks: OEM procurement negotiation levers, aftermarket channel strategies, pricing elasticity matrices, and a distributor qualification checklist.
- M&A and investment toolkit: target scoring, integration playbooks, and valuation sensitivities tied to expected synergies in the two‑wheeler lighting stack.
- Operational resilience modules: supplier concentration risk modelling, alternative sourcing strategies, and inventory/capex timing models keyed to forecast inflection points.
Strategic recommendations for 2026 planning
- Lock in compliance early. With updated safety standards and test requirements in effect, factor homologation lead times and factory testing upgrades into 2026 product launch calendars to avoid missed vehicle program windows.
- Invest selectively in modular LED platforms. Given continuing LED cost declines and margin pressures, the winning suppliers will be those who offer scalable modules that reduce SKU complexity while enabling differentiated functionality across trim levels.
- Prioritize supplier resiliency. Build dual-sourcing or tiered-sourcing strategies for critical optical components and ICs; use the 2026 procurement cycle to negotiate flexible contracts tied to volume and quality KPIs.
- Target aftermarket premium channels for margin uplift. Where OEM penetration is narrow, invest in branded, performance-oriented accessories to capture higher ASPs and shorter product cycles.
- Use M&A and partnerships to buy capability, not just capacity. Access to advanced optics, adaptive lighting controls, and homologation labs buys time-to-market advantage in a concentrated supplier landscape.
Risks and scenario planning
- Regulatory tightening: Unexpected changes to safety or environmental standards could require redesigns or additional testing at short notice.
- Technology substitution: Rapid advances in microLED or OLED could impair incumbent LED module roadmaps; maintain a watchlist and optionality in R&D pipelines.
- Raw material volatility: Although LED costs have fallen materially, commodity and semiconductor disruptions remain a tail risk for production continuity and margins.
- Consolidation dynamics: Continued consolidation among top suppliers can shift bargaining power and alter go-to-market economics; scenario modeling for supplier concentration impacts is essential.
Conclusion — how PW Consulting’s study supports your 2026 playbook
For executives finalizing 2026 budgets and strategic milestones, this research provides the quantitative scaffolding and qualitative playbooks required to make informed choices about product portfolios, sourcing, and growth initiatives. The study balances a disciplined forecast (baseline CAGR of 4.9% over 2026–2032) with hands‑on tools — from compliance checklists to acquisition scorecards — to convert market insight into executable outcomes.
In this preview we have intentionally surfaced headline market sizing, growth trajectory, and strategic frameworks while withholding the granular segmentation tables and region/application splits that power procurement optimization and M&A screening. Those detailed segment-level granules, supplier scorecards, and financial models are available in the full PW Consulting Two Wheeler Lighting Market report for organizations that require playback-ready deliverables to inform 2026 decision-making.
For detailed analysis of this topic, please visit the official page: Two Wheeler Lighting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


