



PW Consulting: Conveyor Belts Market to Reach USD 7.79B by 2032 at 3.81% CAGR

Conveyor Belts Market — 2026 Strategic Brief (PW Consulting)
As companies plan capital allocation, supply-chain hedging, and product roadmaps for 2026, few asset classes combine operational significance with market complexity like conveyor belts. PW Consulting’s latest study (base year 2025, historical 2020–2025, forecast 2026–2032) synthesizes market sizing, demand drivers, supplier economics, and regulatory change into an actionable playbook. At a glance: the global conveyor belts market expanded from approximately USD 4.1 billion in 2020 to about USD 6.0 billion in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of 3.81% through our 2026–2032 horizon — reaching roughly USD 7.8 billion by 2032 under our central scenario.
Conveyor Belts Market
Why this research matters for 2026 decision-making
- Investment allocation: Capital planners need market timing signals for capacity expansion, product-line investments, and automation upgrades that align with a modest but steady market expansion.
- Procurement and sourcing: Raw-material volatility and regulatory updates require refined supplier strategies and contract structures to protect margins without sacrificing service levels.
- Product and R&D roadmaps: Shifts in application demand (e.g., hygienic food processing, heavy-duty mining, automated warehousing) are creating technical and material priorities that determine which product features will capture premium pricing.
- M&A and partnerships: The market structure and pockets of specialization create repeated opportunities for bolt-on acquisitions, joint development, and distribution expansion.
Understanding the macro trajectory
The market’s recovery and expansion since 2020 reflect both cyclical end-market demand and structural refreshes in industrial automation. After growing from about USD 4.1 billion in 2020 to roughly USD 6.0 billion in 2025, our forecast anticipates steady growth into the late 2020s, moderated by commodity-driven input-cost cycles and episodic capex slowdowns. This trajectory — a modest ~3.8% CAGR across 2026–2032 — implies reliable baseline demand but also highlights the premium for companies that can engineer higher-margin, application-specific solutions.
Conveyor Belts Market
Demand drivers and cost dynamics
- Raw-materials regime: Rubber and polymer inputs dominate manufacturing cost structures. Rubber constitutes the single largest raw-material exposure for many producers, and recent years have shown that movements in PVC resin and synthetic-rubber prices can materially shift OEM margins and final pricing. Our scenario work models swings that have historically translated into double-digit percent variation in input costs.
- Automation and labour dynamics: Labour constraints in bulk-material handling, logistics, and processing sectors accelerate adoption of higher-throughput, lower-maintenance belting systems and integrated conveying solutions.
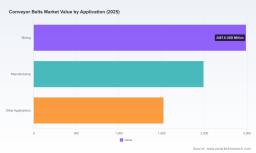
- Application-driven differentiation: Food & beverage and pharmaceutical lines push for hygienic, modular belting; mining and bulk handling demand abrasion resistance and steel-cord reinforcement; e-commerce and parcel handling require modular, high-speed solutions.
- Regulatory and standards pressure: New testing and safety standards — including recent updates such as EN ISO 21181:2025 for elastic-modulus testing of light conveyor belts and mandatory guarding/spacing requirements under OSHA conveyor safety rules — are forcing product redesigns, third‑party testing budgets, and changes in vendor qualification.
- Sustainability and circularity: Recycled-content solutions and lower-carbon production processes are increasingly part of procurement specifications for major OEM and end-user customers.
Supply-side structure and competition
The industry sits in a middle ground of concentration: the largest three players account for a meaningful but not dominant share of the market, and the top five increase that foothold modestly. This structure supports both scale players that compete on breadth and specialty manufacturers that win on niche performance attributes. For corporate strategy, the implication is clear: scale helps in raw-material procurement and global distribution, but focused product differentiation or service models unlock margin premium opportunities.
Conveyor Belts Market
Competitive landscape — strategic reading of core players
Below we synthesize the strategic positioning of leading and influential firms operating across metal, rubber, PVC and modular-plastic domains. The summary is selective — the full vendor dossiers, benchmarking matrices and supplier scorecards are contained in the full PW Consulting report.
- Wire Belt Company of America (Northampton, MA) — Specialist in engineered metal conveyor belting (Flat-Flex®, Compact-Grid®, Eye-Flex®, Versa-Link®). Their emphasis on metal solutions gives a strong foothold in high-temperature, bakery, and oven-conveying niches. Recent trade-show participation (IPPE Atlanta and ASB BakingTECH Chicago in early 2026) underscores a market approach centered on direct engagement with food-processing OEMs and integrators.
- Semperit AG Holding (Vienna) — A leading provider of high-performance belts for heavy sectors such as mining and steel. Their portfolio strength is reinforced by targeted trade-show activity (NAEC Chicago, mid‑2026) and engineering-led differentiation focused on longevity and damage resistance in bulk-material applications.
- Continental AG (Hannover) — Longstanding innovation capabilities across industrial and automotive adjacencies provide Continental with advantages in materials science and integrated-systems thinking, especially where conveying interacts with automation and predictive maintenance ecosystems.
- Intralox (Louisiana) — A recognized leader in modular-plastic belting for hygienic processing, packaging and washdown environments. Their modular approach aligns with food-safety requirements and allows rapid reconfiguration for changing production recipes.
- Fives Group (Paris) — Focused on integrated conveyor systems as part of broader processing lines; Fives emphasizes systems engineering and turn-key delivery, which appeals to capital-project buyers seeking single-vendor responsibility for throughput guarantees.
- Bando Chemical , Fenner Dunlop , and other rubber specialists — These firms maintain advantage in heavy-duty, reinforced rubber belts and pursue incremental gains through fabric- and steel-cord reinforcement technologies. They are central actors where durability and safety standards are paramount.
- China-based manufacturers (including Zhejiang Double Arrow and Qingdao Rubber Six) — Large-volume, cost-competitive producers that serve global industrial demand with scalable capacity. Their positioning pressures commodity pricing while leaving room for premiumization by technology-focused Western suppliers.
- Regional and systems-focused firms (ARTEGO, Lutze, Muller Beltex, etc.) — These suppliers win through application engineering, local service networks, and fast-response replacement logistics, critical in industries where downtime penalties are high.
Across the vendor universe, recent trade-show activity (Pack Expo, CONEXPO-CON/AGG, and other 2025–2026 events) shows an industry investing in both hygiene-focused modular solutions and space-saving, sanitation-forward conveyors — a clear signal about where end-user willingness to pay is moving.
What PW Consulting’s full report delivers (practical assets)
- Executive synthesis with prioritized strategic initiatives for suppliers, OEMs, and end-users mapped to 2026 decision cycles.
- Proprietary historical market sizing (2020–2025) and detailed forecasting scenarios (2026–2032) with sensitivity runs for raw-material shocks, regulatory tightening, and demand slippage.
- Commercial playbooks: pricing levers, contract templates for raw‑material pass-throughs, and supplier-RFQ evaluation criteria.
- Supply‑chain and procurement risk matrix that includes supplier concentration, lead-time exposures, and substitution pathways.
- Regulatory compliance checklists and product redesign implications for standards such as EN ISO 21181:2025 and OSHA conveyor rules.
- Competitive benchmarking, vendor scorecards, and an M&A target short-list with valuation heuristics based on margin archetypes.
- Case studies and implementation roadmaps for margin improvement via product modularization, predictive maintenance, and circular-material substitution.
- Interactive appendices and dashboards containing granular regional, type and application splits (note: detailed segment-level tables are available exclusively in the full report).
Immediate actions for 2026 — a tactical checklist
- Quarter 1: Run an input-cost stress test across key product lines; renegotiate supply contracts with tiered pass-through clauses where possible.
- Quarter 2: Pilot a high-value, application-specific belt offering (e.g., hygienic modular or steel-cord reinforced) with one marquee customer; use pilot results to set premium pricing references.
- Quarter 3: Execute a compliance audit mapped to EN ISO 21181:2025 and OSHA 1910 requirements; budget for third-party testing and certification.
- Quarter 4: Reassess channel strategy — accelerate partnerships for geographies where local service wins; scope bolt-on acquisitions that address gaps in materials or service capabilities.
Conclusion — a trailer that directs next steps
The conveyor belts market in 2026 is neither a high‑growth bubble nor a stagnant commodity pool: it is a stable, technically evolving space where differentiated product engineering, supply‑chain agility, and regulatory compliance translate directly into competitive advantage. PW Consulting’s study equips executives with the market context, scenario tools, and vendor intelligence needed to convert modest baseline growth into outsized returns. For companies that need the granular regional, type and application breakdowns, interactive dashboards, and full vendor dossiers referenced above, access to the complete report and appendices is required — the detailed segment-level analytics are intentionally reserved for the full publication to support client-grade decision-making and confidential benchmarking.
For detailed analysis of this topic, please visit the official page: Conveyor Belts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


