



PW Consulting: ICP Monitoring Market Outlook — 7.8% CAGR (2026–2032)

Intracranial Pressure (ICP) Monitoring Devices Market: Strategic Preview for 2026 Decision-Making
As PW Consulting’s senior strategy advisors and industry analysis team, we present a high‑level, tactically oriented preview of our full market research on the Intracranial Pressure (ICP) Monitoring Devices market. This executive primer synthesizes the structural forces, competitive tensions and regulatory inflection points that will shape strategic choices in 2026. It intentionally demonstrates analytical depth while withholding granular segment-level disclosures reserved for the full report—consider this a professional trailer that makes the case for why executive teams should prioritize a rapid, data‑driven response.
Intracranial Pressure (ICP) Monitoring Devices Market
Market at a Glance: Macro Trajectory and Strategic Consequences
Using 2025 as the base year, our analysis shows the ICP monitoring market has experienced steady growth across the last half‑decade and is entering a higher‑velocity phase. From 2020 through 2025 the market expanded meaningfully, and our forecast through 2032 projects continued momentum with a compound annual growth rate (CAGR) of approximately 7.8% across the forecast period. By 2026 and beyond the market enters a multi‑billion dollar scale and materializes new opportunities across clinical settings, product modalities and service models.
Intracranial Pressure (ICP) Monitoring Devices Market
Why this matters for 2026 planning: a near‑8% structural growth rate implies that incremental improvements in product positioning, regulatory timing, reimbursement strategy and channel execution can yield outsized returns. Conversely, companies that defer investment in monitoring innovation, telemetric solutions or value‑based access strategies risk being marginalized as buyers shift toward integrated neuromonitoring systems and home/remote care pathways.
Intracranial Pressure (ICP) Monitoring Devices Market
Key Dynamics Driving Value Creation
- Technological substitution and modality convergence. Non‑invasive telemetric approaches are gaining clinical attention alongside established invasive sensors. The clinical tradeoffs—accuracy, infection risk, ease of use and longitudinal data capture—create white spaces for differentiated value propositions (hardware, consumables, analytics and services).
- Shifting care locations. Acute care settings remain core, but regulatory approvals and CE markings for ambulatory or home‑based ICP monitoring are catalyzing new pathways for chronic management and remote follow‑up. This opens recurring revenue models and care coordination partnerships.
- Regulatory and standards tightening. Recent device recalls, regulatory clearances and increased attention to biological evaluation standards are raising the bar for market entry and supplier risk management. Compliance speed and post‑market surveillance capabilities are now strategic assets.
- Reimbursement as a gating mechanism. Updated neuromonitoring reimbursement guidance and code utilizations materially influence hospital procurement and physician adoption cycles—companies that proactively align coding strategies with clinical workflows improve commercial access.
- Data and analytics monetization. Continuous ICP signal capture creates opportunities to layer analytics, predictive alerts and outcome‑linked services. Firms that define interoperable data‑to‑care pathways will unlock new capture of system value.
Competitive Landscape: Who Matters and Why
The market remains moderately consolidated, with the leading three and five players holding meaningful shares but leaving ample room for challengers and niche specialists. Our research estimates market concentration metrics that signal both incumbent strength and opportunity for focused disruption; these metrics also underline why strategic partnerships and targeted M&A can be decisive in 2026.
- Integra LifeSciences (United States) — A portfolio approach combining bedside monitoring systems with disposables and reimbursement guidance positions Integra as a go‑to partner for health systems. Their emphasis on clinical education and coding support makes them a commercial force in settings where procedural workflows and CPT utilization matter.
- Medtronic (Ireland) — With integrated neuro monitoring platforms and established transducer/catheter technologies, Medtronic competes on scale, clinical relationships and the ability to bundle ICP offerings within broader neurosurgical solutions. Their route to market benefits from wide hospital penetration and established procurement channels.
- Natus Medical (United States) — Focused neuromonitoring expertise and legacy clinical trust underpin Natus’s competitive position. Their systems appeal to clinicians seeking specialized monitoring fidelity and service continuity.
- European and regional specialists — A set of agile suppliers (RAUMEDIC, Sophysa, Spiegelberg, Gaeltec, IRRAS, Aesculap) are advancing telemetric devices, epidural probes and non‑invasive instruments. These companies move quickly on product designations, CE mark updates and targeted clinical niches, enabling rapid penetration in verticals such as hydrocephalus management and home monitoring.
Strategic implication: incumbents derive advantage from scale and integrated portfolios; challengers win on focused clinical differentiation and regulatory agility. For buyers and investors, the key question is whether to partner with a scaled platform for broad coverage or to back a nimble innovator that can capture high‑value niches.
Regulatory, Reimbursement and Standards Environment
- Recent regulatory actions have immediate commercial impact: a Class 2 device recall has increased scrutiny on legacy sensor kits, while a 510(k) clearance addition for a sensor line demonstrates active regulatory pathways for incremental innovations.
- Standards such as AAMI/ANSI/ISO 10993‑6 are now operationally relevant for design and biocompatibility testing of implantable ICP components—compliance timelines and testing strategies should be embedded in product roadmaps.
- Reimbursement guidance updates (including CPT coding nuances) materially affect utilization economics. Firms that invest in payer engagement and coding education see faster adoption and reduced procurement friction.
Collectively, these dynamics alter time‑to‑market calculus. Regulatory foresight, an accelerated clinical evidence program and proactive reimbursement mapping will be decisive in 2026.
Recent Market Events Worth Executive Attention
- Aesculap’s Breakthrough Device Designation for a non‑invasive telemetric ICP system signals regulatorally enabled acceleration for select novel approaches, particularly in chronic hydrocephalus care.
- RAUMEDIC’s CE marking for a home‑based ICP device highlights the fast‑emerging home monitoring opportunity and the practical reality that ambulatory pathways will be commercially accessible before long.
- Regulatory recalls underscore the importance of robust supply‑chain quality and post‑market surveillance—both for risk mitigation and for preserving hard‑won clinical trust.
What PW Consulting’s Full Report Provides (Practical, Not Generic)
Our complete market study is designed as a hands‑on strategic tool for corporate boards, commercial leaders, R&D heads and M&A teams. Key deliverables include:
- Proprietary market sizing and topline growth projections (historical 2020–2025 and detailed forecast 2026–2032) with scenario analyses that stress‑test slower and faster adoption assumptions.
- Commercial playbooks for four strategic pathways: (1) Platform expansion via bundling and service, (2) Focused product innovation on telemetric/non‑invasive modalities, (3) Channel and partnership models for home and ambulatory monitoring, and (4) M&A and alliance roadmaps that accelerate capability gaps.
- Regulatory and reimbursement roadmaps tailored to ICP device classes—timelines, critical documentation, and payer engagement frameworks to compress adoption lag.
- Competitive profiles and capability matrices for the market’s active players, including product maps, differentiated value propositions and likely strategic moves for 2026–2028.
- Implementation templates—commercial launch checklists, clinical evidence index, and an ROI model that links device economics to hospital procurement KPIs.
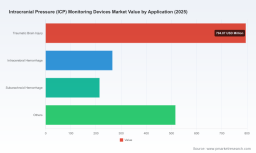
Note: this executive preview purposefully abstracts proprietary segment tables and region/application splits that are included in our full deliverable. Those granular layers convert high‑level opportunity into executable market entry and pricing plans.
How Executives Should Use These Insights in 2026
- Prioritize product/regulatory sequencing. Map R&D release plans against reimbursement cycles and regulatory milestones to maximize early commercial advantage.
- Adopt a hybrid go‑to‑market model. Blend hospital channel coverage for acute care with pilot programs and partnerships for home monitoring—aim to create stickiness through integrated monitoring services and analytics.
- Use M&A selectively. Acquire capabilities that fill one of three gaps—telemetry hardware, analytics/data orchestration, or channel access—rather than acquiring duplicate devices at scale.
- Invest in clinical economics evidence. Generate cost‑of‑care and outcomes data that align with payer value frameworks to accelerate reimbursement conversations.
- Strengthen quality systems and post‑market intelligence. Recalls and regulatory actions penalize complacency; robust surveillance and rapid corrective action plans protect market position and brand.
Methodological Rigor and Confidence Intervals
Our estimates combine primary interviews with clinicians, procurement managers and C‑suite executives; device shipment and revenue triangulation from manufacturer disclosures; and a proprietary demand model that embeds adoption curves by modality and care setting. We apply scenario stress tests for regulatory events, reimbursement delays and accelerated adoption of non‑invasive alternatives to provide resilient planning bands for decision makers.
Closing: Why 2026 Is a Strategic Inflection Year
In short, the ICP monitoring market is no longer a stable, niche arena—it's evolving into a dynamic landscape with new modality entrants, shifting care locations and elevated regulatory and payer scrutiny. The market’s projected growth trajectory through 2032 makes 2026 a year for defining strategic direction: double down on platform plays, selectively incubate telemetric and home monitoring solutions, or pursue targeted inorganic moves to secure capability gaps.
This preview is intended to equip executives with the strategic frame and urgency they need. For teams preparing 2026 budgets, R&D roadmaps, or M&A pipelines, the full PW Consulting report contains the granular segmentation, regional and application breakdowns, and actionable financial models required to translate this strategic intent into executable plans. Access to that level of detail will materially shorten your decision‑making cycle and reduce execution risk.
Next Steps
- Contact PW Consulting to schedule a tailored briefing that walks through scenario maps and the commercial playbooks most relevant to your strategic objectives for 2026.
- Request a demo of our ROI and adoption model to stress‑test your product or acquisition thesis against market pathways and reimbursement scenarios.
For detailed analysis of this topic, please visit the official page: Intracranial Pressure (ICP) Monitoring Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


