



PW Consulting: Food Processing Equipment Market to Reach USD 77,553M by 2032 at 5.3% CAGR

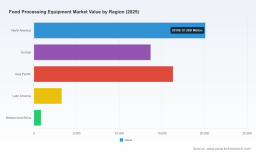
Food Processing Equipment Market: Strategic Outlook for 2026 Decision‑Makers
PW Consulting’s latest Food Processing Equipment Market study (base year 2025, historical 2020–2025, forecast 2026–2032) provides a decision‑oriented roadmap for executives planning investments, M&A, and operational transformations in 2026. The global market—valued at approximately USD 54,201 Million in 2025—is projected to grow at a compound annual growth rate (CAGR) of 5.3% over 2026–2032, reaching roughly USD 77,553 Million by 2032. These headline numbers are the starting point; this brief synthesizes the report’s strategic implications while reserving granular segment and regional breakdowns for the full study.
Food Processing Equipment Market
Why this research matters for 2026
-
Capex prioritization: Capital allocation choices made in 2026 will play out across an equipment life cycle that now must factor in energy transition, changing regulatory standards, and rapid automation adoption.
Food Processing Equipment Market -
M&A and portfolio design: With mid‑single digit growth and moderate concentration at the top of the industry, 2026 is a window for bolt‑on acquisitions and capability fills—particularly in automation, aseptic processing, and energy efficiency.
Food Processing Equipment Market -
Supply chain de‑risking: Tariffs, input price volatility, and logistics constraints are reshaping sourcing calculus. The right sourcing and hedging strategy in 2026 reduces long‑term unit costs and protects margins.
-
Compliance & market access: New and revised equipment standards are changing product specifications and procurement cycles; companies that are early to comply capture first‑mover advantages in tender and retrofit markets.
Headline market dynamics
-
Measured, resilient growth. The market’s projection trajectory shows steady expansion rather than explosive disruption—consistent with demand drivers such as protein processing modernization, convenience foods, beverage line optimization, and growing investment in packaging and shelf‑life technologies.
-
Moderate market concentration. The market concentration metrics indicate a landscape where leading suppliers retain significant share without forming an impenetrable oligopoly: the three largest players account for roughly one‑third of market value, and the top five under half. This configuration keeps strategic options open for agile challengers and private equity.
-
Cost pressure from raw materials and trade policy. Input cost variability (notably for stainless steel and other metals) and the persistence of tariffs introduced in recent years are elevating project budgets and lead times. Manufacturers must integrate material‑cost scenarios into business cases rather than using single‑point estimates.
-
Standards and regulation driving product development. Revisions to major equipment standards and calls to update food safety norms are increasing engineering requirements—particularly in areas such as surface finishes, glass and glass‑like coatings, and hygienic design. These regulatory shifts are accelerating replacement cycles for legacy equipment in some segments.
Technology & sustainability inflection points
-
Energy efficiency as a competitive axis. Recent product introductions emphasize drastic reductions in energy use for key unit operations. Early adopters of high‑efficiency technologies can realize step changes in total cost of ownership and qualify for incentive programs in jurisdictions that subsidize decarbonization investments.
-
AI and factory‑level operating systems. Vendors are now offering AI‑ready factory platforms and integrated control layers that convert equipment into nodes of a data fabric. This is shifting value from individual machines to systems that optimize across throughput, yield, and energy consumption.
-
Modularization and automation. Customers increasingly prefer modular, upgradeable lines over bespoke monoliths; the modular approach reduces downtime risk, lowers upgrade costs, and shortens electrification and automation timelines.
Regulatory and programs that matter in 2026
-
Updated equipment standards are tightening hygiene and materials requirements, with implications for OEM design, aftermarket service, and retrofit markets.
-
Regional incentive programs that fund energy efficiency and renewable integration at processing plants are creating pockets of accelerated demand for energy‑saving equipment and integrated systems.
-
Procurement rules in many large buyers now include supplier sustainability criteria and lifecycle carbon scoring—criteria that must be addressed by equipment vendors and specifiers before contracts are awarded.
Competitive landscape: strategic positions and evolving capabilities
Across system suppliers, specialists, and equipment OEMs, 2026 will distinguish firms by three capabilities: integrated systems expertise, digital and automation offerings, and lifecycle services including retrofits and consumables. Below is a practical strategic read on the core players covered in the report (profiles and company resources are included in the full dataset).
-
GEA Group (Düsseldorf, Germany) — Systems supplier strength. GEA’s portfolio of separation, heat transfer and line systems positions it well in integrated supply opportunities with large processors pursuing turnkey upgrades.
-
Bühler Group (Uzwil, Switzerland) — Grain and value‑chain leadership. Bühler’s depth in milling, extrusion and sustainable value chains makes it a preferred partner where raw material handling and processing are core to customer differentiation. Recent product refreshes in its grains and food portfolio reaffirm R&D momentum.
-
Alfa Laval (Lund, Sweden) — Fluid handling and thermal processes. Alfa Laval’s specialization in separation and heat transfer translates into strong margin capture on retrofit and efficiency projects.
-
SPX FLOW (Charlotte, NC, USA) — Engineered unit operations. SPX’s capability in mixing, separation and thermal systems is complementary to processors looking for applied engineering expertise rather than commodity equipment.
-
JBT / Marel (Chicago / global) — Automation and line orchestration. JBT Marel’s automation solutions are increasingly central to processors seeking throughput improvements and labor‑optimization gains.
-
Tetra Pak (Lausanne, Switzerland) — Aseptic and packaging systems. Recent launches focused on integrated heat‑pump pasteurization and AI‑ready factory platforms strengthen its value proposition on energy and digital fronts.
-
Marmon Foodservice Technologie (Glendale Heights, IL, USA) — Commercial foodservice and beverage equipment: niche breadth that supports quick‑turn projects and service networks.
-
Krones AG (Neutraubling, Germany) — Beverage filling and packaging lines. Krones’ end‑to‑end capabilities make it a go‑to for beverage customers consolidating suppliers.
-
The Middleby Corporation (Elgin, IL, USA) — Cooking and food processing platforms. Middleby’s planned spin‑off of its food processing business signals strategic portfolio refocusing and creates potential acquisition targets or partnership opportunities for rivals and private equity.
-
Multivac Group (Wolfertschwenden, Germany) — Packaging and slicing, with a global aftermarket network and strong hold in value‑added packaging innovations.
-
Marel (Iceland) — Protein processing automation, combining hardware and software for protein processors seeking traceability and yield optimization.
-
BAADER (Büchen, Germany) — Fish and meat processing machinery with deep application know‑how in filleting and portioning that remains sticky with customers.
Recent developments worth watching in 2026
-
Major product launches from leading OEMs are emphasizing energy reduction (including heat‑pump pasteurization) and factory OS platforms that prepare plants for AI‑driven operations.
-
Corporate restructurings and spin‑offs are reshaping competitive dynamics and creating acquisition targets for firms seeking to scale specific capabilities.
-
Standards bodies and industry associations are actively revising food equipment norms—firms participating early in standards development influence outcomes and accelerate customer acceptance of new technologies.
What the full PW Consulting report delivers (practical components)
-
A granular market model with historic reconstructions (2020–2025) and forecast scenarios (2026–2032), enabling sensitivity analysis by growth, price, and input‑cost trajectories.
-
Vendor landscape with capability maps and comparative assessments of product, software, and service portfolios across the leading OEMs.
-
Regulatory impact assessment that quantifies implications of recent standard revisions and regional incentive programs on CAPEX timing and retrofit cycles.
-
Supply chain and raw‑material risk matrix with practical mitigations (sourcing strategies, hedging approaches, and modular design to reduce metal exposure).
-
Use cases and ROI calculators for key investments such as energy‑efficient pasteurization, aseptic packaging conversions, and factory OS rollouts.
-
M&A and partnership playbook identifying target archetypes and valuation benchmarks—critical for 2026 deal screening.
-
Comprehensive dataset (regional, product‑type and application splits) and downloadable tables for desk and board‑level analysis.
How to act on these insights in 2026
-
Prioritize investments that reduce total cost of ownership rather than lowest upfront cost—energy efficiency and digital control systems should be evaluated with multi‑year TCO models.
-
Revisit sourcing: consider regional supplier redundancy and inventory strategies to shield projects from tariff and material‑price shocks.
-
Accelerate standards compliance and certification roadmaps to win competitive tenders where equipment hygiene and materials are procurement differentiators.
-
Use 2026 to pilot modular, AI‑ready lines in lower‑risk production cells: the lessons will scale with limited disruption and create reference cases for broader rollouts.
-
Scan the corporate actions pipeline for attractive divestitures and spin‑offs; disciplined buyers can capture capabilities at attractive multiples if timing aligns with internal synergy plans.
PW Consulting’s Food Processing Equipment Market study combines a robust market model with practical execution tools designed for boardrooms and corporate development teams. We intentionally provide a high‑level strategic synthesis here while reserving the full regional, application and product‑type data tables—plus vendor revenue syntheses and downloadable models—for the complete report. For the detailed segment numbers, supplier revenue splits, and model access that will inform 2026 procurement, capex, and M&A decisions, please consult the full report on our website.
For detailed analysis of this topic, please visit the official page: Food Processing Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


