



PW Consulting — Onychomycosis Market: USD 5,460M by 2032, 5.5% CAGR (2026–2032)

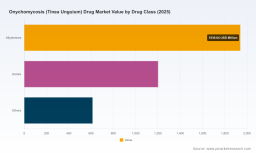
Onychomycosis (Tinea Unguium) Drug Market — Strategic Preview for 2026 Decision‑Making
Market snapshot
The onychomycosis drug market has moved from a mid‑single‑billion dollar category in 2020 to a materially larger, more dynamic market by 2025. With a clearly established historical trend spanning 2020–2025 and a dedicated forecast window covering 2026–2032, our modeling shows sustained expansion through the coming investment cycle. The market’s compound annual growth rate across the forecast period is 5.5%, and total market value rises markedly from its 2025 base as new formulations, label strategies and commercial partnerships reshape access and uptake.
Onychomycosis (Tinea Unguium) Drug Market
Why this report matters to corporate leaders in 2026
-
Timing of portfolio bets. The next 12–24 months will determine which late‑stage topical and reformulated oral products capture sustainable share. Our report aligns clinical, regulatory and commercial timelines so executives can sequence M&A, licensing and geographic launches around inflection points rather than quarterly noise.
Onychomycosis (Tinea Unguium) Drug Market -
Payer and pricing pressure. Reimbursement dynamics—particularly for high‑cost topical prescriptions—are already influencing regimen selection in major payor systems. Executives who integrate payer sensitivity and prior‑authorization risk into pricing strategies will avoid launch underperformance.
Onychomycosis (Tinea Unguium) Drug Market -
Channel and brand strategies. Recent OTC/brand permutations and licensing agreements are redefining route‑to‑market options for topical terbinafine and other differentiated agents. Understanding the tradeoffs between prescription-only, OTC, and licensed‑brand launches is now a core commercial decision.
Key dynamics shaping the near‑term landscape
-
Clinical and safety profile tradeoffs. Oral antifungals remain clinically attractive for efficacy, but require routine liver‑function monitoring and carry hepatotoxicity considerations that influence HCP prescribing behavior. Topical innovations seek to bridge efficacy gaps while avoiding systemic safety monitoring—but reimbursement and adherence remain barriers to realizing their potential.
-
Price and utilization distortion in topicals. Certain topical agents command very high per‑prescription prices in established markets, which heightens scrutiny from payers and accelerates formulary management actions such as prior authorization. Manufacturers must balance list price with contracting strategies to preserve patient access and volume.
-
Consolidation and concentration. The competitive structure is materially concentrated—market leadership is dominated by a handful of multinational and regional players—making M&A, licensing deals and co‑promotion agreements powerful levers to scale quickly in priority markets.
-
Regulatory nuance and brand migration. Country‑level brand approvals and trademark licensing can materially affect launch timing and brand positioning. Recent approvals and supplier decisions for novel topical terbinafine products illustrate how regulatory sequencing and supply‑chain readiness create first‑mover advantages.
Competitive landscape — who matters and why
The competitive mix blends established pharma incumbents with specialist dermatology players and agile generics manufacturers. Global innovators maintain strong footholds with legacy oral agents and branded topicals; specialist firms have leveraged differentiated formulations and licensing models to build fast followers and, in some cases, displace incumbents at launch.
-
Large multinationals: Companies with broad antifungal portfolios remain influential through longstanding global distribution, clinical trial resources and payer relationships. Their scale supports lifecycle management (line extensions, new dosings) and negotiation leverage with payers.
-
Dermatology specialists and biotech: Smaller companies focused on topical innovation are increasingly relevant—especially where novel formulations deliver improved tissue penetration or OTC positioning. Their strategic value often lies in nimble regulatory filings and targeted licensing deals.
-
Generics and regional manufacturers: Price competition from generics continues to cap systemic agent margins and compress entry economics in mature markets, but generics makers are also important commercial partners for co‑marketing or regional roll‑outs.
Recent strategic developments spotlight
A cluster of licensing agreements, regulatory approvals and regional launches in late 2025 and early 2026 illustrates how quickly commercial dynamics can flip. Exclusive regional licensing of a novel topical terbinafine formulation has delivered immediate market leadership in select small markets, while supplier approvals and expanded manufacturing capacity have removed near‑term production constraints—enabling accelerated European commercialization. These moves underline three tactical points for 2026:
-
Secure dual or backup suppliers early for novel actives to prevent launch delays.
-
Consider selective licensing to accelerate entry in constrained geographies rather than a self‑led rollout that may be slower and costlier.
-
Anticipate brand approval and trademark migration rules in key markets when planning co‑marketing and promotional strategies.
What the PW Consulting report contains — practical, actionable modules
The full study synthesizes epidemiology, clinical practice, regulatory frameworks and commercial levers into a single decision support tool tailored for boardrooms, business units and corporate development teams. Key deliverables include:
-
Market architecture and forecasting: A robust bottom‑up model (base year 2025) projecting through 2032 with scenario and sensitivity testing around pricing, adherence and payer access assumptions.
-
Payor mapping and reimbursement playbook: Payer segmentation, prior‑authorization risk matrices, and contracting scenarios to model net pricing outcomes by market archetype.
-
Go‑to‑market sequence planner: Tactical frameworks for launch sequencing, channel selection (Rx vs OTC), and promotional mixes that reflect differing payer and HCP adoption curves.
-
Competitive and pipeline dossier: Strategic profiles of leading multinational, specialist and generics players, plus a rolling pipeline tracker for late‑stage topical and systemic programs—highlighting where opportunities for licensing or acquisition create asymmetric upside.
-
Operational readiness checklist: Manufacturing, supplier qualification and regulatory submission playbooks keyed to avoid common launch delays encountered in recent rollouts.
-
M&A and licensing scorecards: Deal valuation heuristics, royalty benchmarks, and integration risk matrices to accelerate diligence and term‑sheet development.
Strategic implications — how to convert insight into decisions in 2026
-
Prioritize assets that de‑risk payer negotiations. Given the high cost per topical prescription observed in mature markets, prioritize formulations and clinical evidence that demonstrably lower total cost of care or reduce the need for repeat therapy.
-
Lock in commercial partners for a phased regional rollout. Licensing deals that grant well‑known trademarks into new markets reduce educational spend and can accelerate pharmacy adoption—particularly where brand recognition drives patient and prescriber trust.
-
Embed safety monitoring requirements into launch planning for oral agents. Products requiring hepatic monitoring should be bundled with HCP education and digital adherence supports to limit drop‑off and to mitigate payer concerns.
-
Design flexible pricing corridors. Use the forecasting model’s scenario outputs to build tiered contracting approaches that adapt to formulary pressure without compromising long‑term brand positioning.
-
Use concentration to your advantage. The market’s degree of concentration means well‑timed partnerships or targeted acquisitions can meaningfully shift share dynamics—seek bolt‑on assets that fill channel or formulation gaps rather than duplicating capabilities.
How to use this preview — governance and execution
Bring the full report into strategic reviews that govern 2026 resource allocation: R&D prioritization, Q1 launch readiness, and BD&L pipelines. Use the included decision matrices in investment committees to translate market scenarios into spend thresholds and milestone‑based commitments. For corporate development teams, the report’s licensing scorecards and royalty benchmarks will materially shorten term‑sheet drafting and valuation debates.
Closing note — a preview that points the way forward
We designed this briefing as a strategic trailer: it demonstrates the depth of our modelling, the granularity of our commercial frameworks, and the immediacy of the market events that will shape outcomes in 2026. The full PW Consulting Onychomycosis (Tinea Unguium) Drug Market report contains the detailed segmentation, market‑by‑market forecasts, and proprietary tools you need to convert insight into high‑confidence decisions. For licensing, launch sequencing, payer negotiation strategy and M&A prioritization, the comprehensive dataset and actionable playbooks are available in the published study.
For detailed analysis of this topic, please visit the official page: Onychomycosis (Tinea Unguium) Drug Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


