



PW Consulting: Tissue Engineering Market Set to Grow at 14.35% CAGR to 2032

Tissue Engineering Market 2026: Strategic Imperatives for Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a forward-looking perspective on the tissue engineering market that frames the most consequential strategic decisions for 2026. This briefing synthesizes market-scale dynamics, regulatory and reimbursement inflections, competitive developments, and high-impact strategic options — all rooted in our full market study. The intent is to surface the signals you cannot afford to miss while preserving the granular, transaction-ready data in the full report to which this article directs you.
Tissue Engineering Market
Market trajectory: a compact, high-growth opportunity
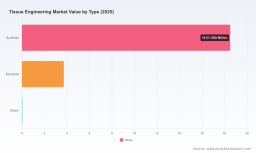
The tissue engineering market has moved from an emergent niche into a clearly defined growth market. Using 2025 as the base year, our topline sizing indicates a market on the order of tens of millions of USD in 2025, with a robust compound annual growth rate (CAGR) of approximately 14.35% across the 2026–2032 forecast window. Under that trajectory the market expands materially by 2032, reflecting maturation across product classes (acellular scaffolds, synthetic matrices, bioprinted constructs) and commercialization progress in several clinical segments.
Tissue Engineering Market
What this means for corporate strategy in 2026 is straightforward: the market is large enough to justify meaningful investment in industrialization and commercialization, yet nascent enough that product, reimbursement, and regulatory plays will determine winners and losers. Tactical choices made this year about capacity, partnerships, and regulatory sequencing will compound into durable competitive advantage.
Tissue Engineering Market
Why 2026 is an inflection year
- Regulatory clarity and momentum: Regulatory pathways are accelerating for tissue engineered products. Programs such as the FDA’s Breakthrough Devices pathway (which recorded over a thousand designations and nearly two hundred authorizations across CDRH and CBER by late 2025) are lowering time-to-market for qualifying innovations. Notably, several products achieved meaningful regulatory milestones recently, providing real-world precedent and market signaling.
- Reimbursement signals: Payer movement is tangible. For example, the U.S. CMS finalized a payer mechanism for skin substitute products in the CY 2026 physician fee schedule, establishing a per-area payment benchmark for incident-to supplies in outpatient settings. This kind of explicit pricing construct reduces commercial uncertainty for certain dermal applications and alters go-to-market calculus.
- Commercial validation through approvals and clearances: Over the past 18 months, early commercial approvals and 510(k) clearances for scaffold and acellular products have created precedent and traction in clinical adoption. These events have shifted tissue engineering from speculative to executable for many strategic buyers and investors.
Competitive landscape — who’s shaping the market
The ecosystem is composed of specialist therapeutics companies, advanced-materials manufacturers, and platform bioprinting firms. Several companies are already moving from R&D to commercialization, each pursuing different product and market strategies. Key players we highlight in our analysis include:
- Humacyte Global, Inc. (Durham, NC, USA; https://humacyte.com) — commercializing an acellular tissue-engineered vascular conduit that received full FDA approval as a first-of-its-kind product for extremity vascular trauma. Humacyte’s regulatory success and clinical positioning exemplify how regulatory strategy can unlock commercial opportunity for biologically engineered constructs.
- Poietis Biosystems (Saint-Germain-en-Laye, France; https://poietis.com) — offering GMP-compliant bioprinting platforms and clinical-grade skin graft candidates. Their platform-centric model highlights the strategic value of industrialized bioprinting capabilities.
- 3D BioTherapeutics (AuriNovo) (United States; https://aurinovo.com) — delivering autologous 3D-bioprinted implants for reconstructive indications. Autologous approaches underline trade-offs between clinical personalization and operational scalability.
- Dimension Inx (Chicago, IL, USA; https://dimension.bio) — developing 3D-printed synthetic bone grafts for oral/maxillofacial reconstruction, demonstrating how advanced materials and additive manufacturing are combining to address surgical segments.
- PolyNovo Biomaterials Pty Ltd (Port Melbourne, Australia; https://polynovo.com) — an example of scaffold innovation commercialized through degradable foam technology, which recently achieved U.S. regulatory clearance for dermal applications.
- Helios Biomedical, Inc. (Weston, MA, USA; https://heliossurgical.com) — a player in acellular dermal matrices with recent U.S. device-clearance milestones supporting wound healing applications.
These companies represent different strategic archetypes: platform providers, product-specialists, autologous innovators, and synthetic-materials manufacturers. Our full benchmarking maps each archetype against capital intensity, time-to-revenue, margin profiles, and exit pathways.
Regulatory and reimbursement dynamics to prioritize
- Program leverage and early engagement: Pursue Breakthrough/Breakthrough-analog designations where applicable; regulatory programs are showing real ability to accelerate market entry for qualifying tissue-engineered products. Early engagement with agencies to align on pivotal endpoints is now a basic expectation.
- Payer-first evidence generation: Design clinical programmes to produce payers’ required real-world and cost-effectiveness evidence alongside safety and efficacy data. Recent CMS actions on skin substitutes demonstrate the power of explicit payer guidance to unlock commercial uptake.
- Post-market surveillance as commercial strategy: Given evolving regulatory precedent and real-world requirements, investment in robust post-market data systems is both a compliance necessity and a commercial differentiator.
Strategic plays that matter in 2026
Based on our scenario modeling and commercial due diligence, companies should consider the following strategic priorities for 2026:
- Scale manufacturing with a phased capital plan: For allogeneic/acellular products the path to margin improvement runs through scale. Build modular, cGMP-capable lines that can be validated incrementally to reduce upfront capital exposure.
- Verticalize selectively; partner for everything else: Vertical integration makes sense for core platform elements (e.g., biofabrication hardware, critical polymer chemistries), but most firms will accelerate time-to-market through targeted partnerships for distribution, fill-finish, and localized regulatory expertise.
- Differentiate on total cost of care: Payers will evaluate tissue engineered therapies against alternatives on the basis of clinical outcomes and downstream cost offsets. Clinical and health-economic evidence that demonstrates fewer complications or reduced reinterventions is a primary commercial lever.
- Adopt a hybrid commercialization model: For many indications, combining direct specialist-hospital sales with OEM partnerships for broader channels yields the best balance between control and reach.
- Stay opportunistic on M&A: Given the market’s structure, tuck-ins for manufacturing capacity, clinical-data assets, or regional regulatory coverage can be high-leverage plays to accelerate scale.
Risks and mitigants
- Clinical adoption lags: Even with approvals, adoption can be slowed by clinician workflow friction and training needs. Mitigation: invest in key-opinion leader programs and deploy focused clinical implementation pilots.
- Reimbursement gaps: Payer policy can lag technology. Mitigation: proactive payer engagement and parallel real-world evidence collection to shorten reimbursement timelines.
- Supply chain and raw-material risk: Advanced biomaterials sometimes rely on specialized inputs. Mitigation: dual-sourcing, long-term supplier contracts, and early qualification of alternative materials.
- Regulatory uncertainty in new modalities: Heterogeneity in country-level pathways can slow expansion. Mitigation: use precedent cases (recent clearances and approvals) as templates and adopt a country-prioritization strategy.
What the full PW Consulting report delivers
The research behind this briefing contains operationally actionable deliverables designed for executive teams pursuing market entry, scale-up, or investment in tissue engineering. Key deliverables include:
- Detailed top-down and bottom-up market sizing and scenario-modeled forecasts for 2026–2032, with downloadable model files to test assumptions;
- Segment- and country-level opportunity mapping (note: granular segment data and exact regional breakdowns are included in the full report);
- Regulatory pathway playbooks tailored to device-like versus biologic-like tissue engineered products, including stepwise clinical evidence plans and exemplar timelines;
- Reimbursement matrices that translate local payer rules into time-to-revenue and pricing sensitivity analyses;
- Commercialization playbooks covering channel strategies, salesforce sizing, and partnership criteria;
- Competitive intelligence dossiers and M&A heatmaps for strategic planning and diligence;
- Manufacturing and supply-chain design templates for phased scaling of biomanufacturing and scaffold production;
- Investment due diligence checklists and ROI modeling for private equity and corporate venturing teams.
Because the full report contains the granular segmentation and financial tables that underpin commercial decisions, we intentionally omit those tables here to preserve the value of the source deliverable. If you are evaluating a market entry, partnership, or investment, the granular segment slices, price assumptions, and market-share scenarios in the full report are indispensable.
Immediate next steps for executives
- Run a rapid capability assessment against the five strategic plays outlined above to identify near-term investment needs (R&D, regulatory, manufacturing, commercial);
- Prioritize regulatory interactions in 2026 to exploit program advantages and convert designations into accelerated market access;
- Engage payers early, using the CY 2026 reimbursement structure in key markets as a benchmark for pricing and evidence collection strategies;
- If acquisition is on the table, use the full report’s M&A heatmap to shortlist targets that offer immediate capability uplift or market access.
In closing, tissue engineering presents a high-growth, high-strategy market where 2026 decisions on scale, regulatory sequencing, and commercialization model will disproportionately determine mid-decade outcomes. PW Consulting’s full Tissue Engineering Market report delivers the granular data, scenario models, and playbooks needed to convert this market potential into repeatable commercial success.
Learn more
Access the full report for the segment-level forecasts, country and application breakdowns, downloadable financial models, and company dossiers that underpin the recommendations above. The report is designed as an executable manual for 2026 decision-makers navigating a pivotal year in tissue engineering commercialization.
For detailed analysis of this topic, please visit the official page: Tissue Engineering Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


