



PW Consulting: Oat Protein Market to Reach USD 252.1M by 2032 at 9.5% CAGR

Oat Protein Market 2026: Strategic Preview for Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present an executive preview of our latest Oat Protein Market research. This briefing translates market dynamics, regulatory inflections, value-chain economics and competitor moves into a practical decision framework for 2026. It is designed as a “trailer”: rigorous, insight-rich and directional — while reserving the proprietary, segment-level figures and granular scenario outputs for the full report.
Oat Protein Market
Why Oat Protein Matters for 2026 Strategy
The oat protein sector has moved from niche experiment to scalable ingredient class within a short window. At a macro level, the market expanded from roughly USD 92 million in 2020 to USD 133.5 million in our base year (2025) and is projected to more than double by 2032 — reaching about USD 252.1 million. That trajectory implies a compound annual growth rate in the high single digits (our forecasts use a 9.5% CAGR for 2026–2032), reflecting broad adoption across food, beverage and nutrition applications. For boards and commercial leaders planning 2026 tactics, the implication is clear: oat protein is no longer an experimental SKU — it is a strategic growth vector where timing, partner selection and differentiation will determine winners.
Oat Protein Market
What This Research Delivers (Practical, Actionable)
- Market sizing and trend validation: a reproducible topline model showing historical performance (2020–2025) and scenario-based forecasts for 2026–2032 including downside and accelerated-adoption pathways.
- Commercial playbook: go-to-market options by customer segment (F&B formulators, sports nutrition, personal care), pricing levers and margin bridge analysis for concentrates vs. isolates.
- Supply and sourcing analysis: cost buckets for oat raw material, byproduct streams, and processing pathways (mechanical, enzymatic, membrane separation) with illustrative cost curves and capacity thresholds.
- Regulatory and claims roadmap: a compliance tracker for major markets (U.S., Canada, EU) and recommended labeling/claims approaches that materially affect shelf acceptance and trade risk.
- M&A and partnership screening: acquisition targets, JV structures, and integration checklists tailored to acquirers seeking immediate capacity, IP, or downstream market access.
- Risk & resilience diagnostics: supply shock scenarios, feedstock volatility modelling, and mitigation strategies (contract farming, upcycling pipelines, strategic inventory).
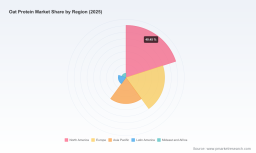
Note: this preview intentionally omits core segment-level sales breakdowns and regional revenue tables. Those details are central to tactical decisions and are available only in the full report.
Oat Protein Market
Competitive Landscape — Who’s Shaping Supply, and How
The market remains relatively unconsolidated: our concentration metrics show the largest three players account for under one-quarter of the market, and the top five barely exceed a quarter. This low concentration signals continued opportunity for mid-sized ingredient suppliers and agile start-ups, as well as risk of margin compression where inputs commoditize.
- Lantmännen (Sweden) — Strength: integrated grain handling and growing downstream processing capacity. Recent capacity investments (new grain terminal in Uddevalla, May 2026) signal a strategy to own more of the feedstock-to-ingredient chain, which reduces raw-material cost volatility and improves traceability for customers requiring provenance for sustainability claims.
- Avena Foods (Canada) — Strength: protocol-driven purity and allergen control. Their focus on documented gluten-free oat protein concentrates plays well into coeliac and allergen-sensitive segments; their farm-to-factory customer engagements (e.g., regenerative agriculture events) also strengthen supplier relationships and traceability narratives.
- Tate & Lyle (UK) — Strength: formulation and health-claims capability. Their branded functional ranges (e.g., beta-glucan-focused lines) illustrate the value in coupling protein with demonstrable wellness claims for premiumization.
- Cargill, Glanbia, Kerry, Royal Avebe, DSM-Firmenich — Strength: scale, formulation services and broad customer reach. These firms compete on reliability, integrated product portfolios and co-development resources for large food manufacturers.
- Swedish Oat Fiber, The Green Labs — Strength: specialization and agility. Smaller, focused players are advantaged in niche technical applications (e.g., fiber-protein combinates, nutraceutical-grade isolates) and in rapid customer co-development cycles.
Strategic inference: buyers seeking guaranteed supply and traceable sustainability will favor integrated processors; formulators seeking tailored functional performance will partner with specialty suppliers. For investors, the fragmented structure presents roll-up opportunities, but careful diligence is required to avoid acquiring low-margin commodity processing assets without pathway to formulation value.
Recent Developments That Alter 2026 Playbooks
- Capacity movements. High-profile capacity expansions by processors and oat-dominant brands (notably Lantmännen’s terminal and Oatly’s 2026 production investment) are creating incremental upstream demand and new sources of oat co-products. Sourcing strategies must account both for incremental supply and for the timing of lift in processing throughput.
- Upcycling & feedstock economics. Oat-milk pulp and other process residues are increasingly used as low-cost feedstock for protein extraction and formulation. This materially alters raw-material cost curves and creates circularity narratives that many brands will monetize.
- Regulatory tightening and clarity. Since early-2025, regulators in the U.S., Canada and Europe have sharpened guidance on plant-based labeling, ingredient status and allergen declarations. These changes accelerate commercialization for compliant players, but raise rework costs for those using ambiguous claims or lacking traceability documentation.
Segment Dynamics You Need on Your Radar
From a formulation standpoint, oat protein concentrates (typical protein content range 55–80% on a dry basis) offer an attractive balance of cost, solubility and mouthfeel for many food and beverage uses. Isolates and hydrolysates remain higher-margin, higher-performance options where amino-acid profile or functional performance demand justifies price premiums. The byproduct economics of oat milk processing are particularly important: the availability of insoluble oat pulp as an upcycled feedstock is lowering effective raw-material costs and creating vertically integrated opportunities for processors that can convert pulp into protein-rich formulations.
Regulatory & Claims Imperatives
- U.S. FDA guidance on plant-based labeling (draft, Jan 2025) emphasizes explicit ingredient declaration and avoids ambiguous analog claims. Companies must align product passports and labeling templates with the guidance before large-scale launches to avoid trade disruption.
- North American regulatory frameworks continue to require GRAS processes and allergen disclosure for oat-derived ingredients, a non-negotiable for sports nutrition and pediatric product segments.
- In the EU, EFSA’s stance on novel-food pathways and sustainability reporting imposes additional documentation burdens — but also creates a competitive advantage for suppliers with traceable, minimally processed concentrates.
Implications for 2026 Corporate Actions
Organizations that treat oat protein as a discrete strategic initiative — not merely another SKU — will outperform. Below are tactical pathways we recommend prioritizing in 2026:
- Secure upstream supply with dual levers: strategic contracts with oat growers (including regenerative clauses where relevant) and investments in processing capacity or offtake agreements with processors expanding capacity.
- Differentiate through formulation: target product segments where oat’s sensory and functional profile provides defensible advantage (e.g., blended dairy alternatives, certain sports-nutrition matrices) and couple with clinically supported claims where possible.
- Operationalize upcycling: integrate or partner with oat-milk processors to capture low-cost pulp feedstock and reduce substitution risk versus commodity protein inputs.
- Regulatory-first commercialization: implement an ingredient passport and regulatory checklist to fast-track launches while avoiding post-market compliance costs.
- Pursue selective M&A: target assets that deliver incremental margin (formulation, branded health-claims, proprietary extraction IP) rather than scale for scale’s sake in a fragmented landscape.
Commercial Roadmap — First 100 Days
- Audit: validate current product portfolios for oat-protein compatibility, regulatory readiness and margin resilience.
- Sourcing: open negotiations for staggered offtake with at least two primary processors to reduce single-source risk (consider co-location benefits).
- Product pilots: launch 2–3 joint development projects with leading ingredient suppliers (one with a scale player, one with a specialty supplier) and embed shelf/stability testing into contracts.
- Claims & labeling: finalize labeling frameworks in collaboration with regulatory counsel to ensure cross-border marketability.
Why PW Consulting’s Full Report Is Strategic for 2026 Decisions
Our full analysis provides the missing tactical layers required for commitment decisions: detailed segment and regional revenue splits, customer-level channel economics, contract-pricing benchmarks, and a prioritized list of acquisition targets with indicative valuations. We also provide downloadable modeling templates to stress-test your capital allocation and go-to-market strategies under alternative uptake scenarios. This preview demonstrates the analytical direction; the full study supplies the operationally critical numbers and playbooks your leadership team will need to execute in 2026.
To summarize: the oat protein opportunity in 2026 is real, measurable and accessible — but it is time-sensitive. Success hinges on anchoring supply, differentiating at the formulation level, and navigating a tighter regulatory environment with documented traceability. The market’s low concentration today favors agile entrants and well-executed roll-ups; however, early investments in regulated compliance and integrated feedstock will define who captures the long-term margin pool.
Contact PW Consulting to access the full Oat Protein Market report and the proprietary model that translates these strategic insights into board-level options for 2026 capital and commercial planning.
For detailed analysis of this topic, please visit the official page: Oat Protein Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


