



PW Consulting: Micronized Wax Market to Expand at 5.9% CAGR Through 2032

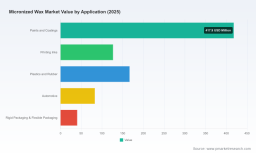
Micronized Wax Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest Micronized Wax Market research positions CFOs, heads of product, procurement leaders, and M&A teams to make high-conviction decisions in 2026. The market—anchored by specialized synthetic and natural waxes used across paints & coatings, printing inks, plastics, rubber and packaging—has demonstrated resilient expansion through the early 2020s and continues into the next planning cycle. Our base-year assessment (2025) and seven-year forecast (2026–2032) deliver the quantitative foundation and qualitative context that senior executives need: the global market size registers at USD 835.0 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 5.9% through 2032, reaching a modeled USD 1,240.0 Million by the end of the forecast horizon.
Micronized Wax Market
Why this research matters for 2026
- Timing: 2026 is a strategic inflection point—raw material normalization after pandemic-era volatility, accelerating sustainability regulation, and application-led innovation (e.g., sub-micron waxes for additive manufacturing) converge to reshape supplier and customer economics.
- Capital allocation: With steady mid-single-digit CAGR and clear pockets of premiumization, our study helps prioritize R&D investments, brownfield/greenfield capacity programs, and M&A targets against expected ROI timelines.
- Commercial strategy: The report translates market growth into prioritized go-to-market plays by application and product architecture—enabling sales leaders to tune commercial coverage and pricing strategies without chasing marginal segments that add complexity but dilute margins.
Market dynamics — what we uncovered
Three dynamics dominate near-term strategy for micronized-wax participants.
Micronized Wax Market
- Feedstock and price dispersion: Paraffin and polyethylene feedstock prices remain regionally disparate and serve as the primary input-cost swing. Our tracking indicates meaningful regional variance in paraffin pricing throughout 2026, creating near-term windows for margin capture where producers can align sourcing and regional production. Firms that lock flexible supply agreements or invest in feedstock diversification can both mitigate input-price shocks and extract incremental margin.
- Sustainability and product differentiation: Buyers increasingly demand low-carbon product footprints and non-PFAS formulations. Leading suppliers are responding with lower-CO2 product lines and alternate feedstock blends (e.g., rice-bran-based blends) to reduce exposure to constrained natural waxes like carnauba. Our analysis shows that sustainability-aligned product launches command a structural premium in certain applications and can accelerate qualification timelines with large global converters.
- Application-driven innovation: Technical progress—particularly particle-size control into sub-5 μm regimes—has opened new application adjacencies (for example, in advanced 3D printing and high-performance coatings). These product innovations shift value from commodity pricing toward specification-driven supply, altering the competitive battleground from volume to technical know-how and application support.
Competitive landscape — who is shaping the market
The market has a measurable level of concentration: the leading three players account for a significant minority share of global revenue (CR3 ≈ 38%), and the five largest suppliers increase that share materially (CR5 ≈ 45%). That structure creates both opportunities and risks for mid-sized players and new entrants.
Micronized Wax Market
- Large integrated players: Global incumbents with broader chemical franchises are leveraging platform capabilities to extend into specification-grade waxes and emulsions—rapidly turning product launches into commercial wins. Recent examples include new polyethylene emulsion waxes tailored for food packaging inks and advanced sub-5 μm PE waxes for additive manufacturing, signals that incumbents are prioritizing higher-margin, specification-led segments.
- Sustainability-first and specialty challengers: Select mid-sized specialists are targeting niche differentiation—either via feedstock innovation (rice-bran blends, oxidized wax grades) or life-cycle footprint reduction. Product carbon footprint reductions disclosed in recent launches demonstrate this shift and are being used as a wedge in commercial conversations with tier-1 converters.
- Regional and contract manufacturers: Several high-quality regional producers focus on supply flexibility and price competitiveness for industrial-grade micronized PE waxes. These players remain attractive partners for converters seeking localized supply chains and lower landed costs.
Recent strategic moves are illustrative: some global chemical groups introduced new PE emulsion waxes and sub-micron powders in 2025 to capture growth in printing inks, overprint varnishes, and emerging 3D-printing use-cases; a major producer announced lower-carbon spray wax grades in early 2025; another launched a rice-bran-based product specifically to reduce reliance on constrained natural wax sources. At the same time, one specialty supplier formally announced an exit from PFAS-containing product lines—underlining regulatory pressure and the need for reformulation roadmaps across value chains.
What the PW Consulting report contains (practical, actionable elements)
- Quantitative base and forecast model (2020–2032) with scenario toggles for feedstock price shocks, regulatory constraints, and accelerated adoption of low-carbon grades—presented at global and detailed segment levels (note: segment-level tables and client-only datasets are accessible via the full report).
- Competitive benchmarking that scores manufacturers across product breadth, technical capabilities (particle-size control, dispersions), sustainability credentials, and channel strength to identify realistic M&A and partnership candidates.
- Bottom-up demand-driver analysis by application cluster, including sensitivity to end-market cycles (automotive, packaging, coatings/inks) and manufacturing CAPEX assumptions for key downstream converters.
- Procurement playbook and sourcing decision matrix to optimize raw-material hedging, regional production footprints, and tolling vs. captive strategies under multiple cost scenarios.
- Roadmaps for product and regulatory risk mitigation—covering PFAS phase-outs, alternative feedstock qualification, and life-cycle assessment (LCA) benchmarking to support procurement and sustainability reporting.
- Commercial growth plays: prioritized account lists, qualification acceleration tactics, sample-to-spec timelines, and pricing architectures for both commodity and specification-led products.
Strategic implications and recommended actions for 2026
- For manufacturers with R&D muscle: Accelerate development of sub-micron and low-CO2 grades targeted at high-growth, high-margin applications. Protect innovations with application validation partnerships and proprietary dispersion technologies rather than competing solely on price.
- For mid-sized producers: Double down on regional supply advantages and specialty niches. Build alliances with converters who value localized logistics and fast qualification cycles; consider bolt-on acquisitions that add technical capability or downstream access.
- For buyers (converters, formulators): Reassess supplier scorecards to include life-cycle footprint and reformulation risk. Implement dual-sourcing for critical wax families and demand supplier transparency on product carbon footprints and feedstock provenance.
- For private equity and corporates: The market’s mid-single-digit CAGR combined with fragmentation outside the top tiers creates attractive buy-and-build opportunities—especially where integration can capture synergies from downstream access, technical service, or feedstock contracts.
A note on granularity and next steps
This preview is intentionally diagnostic rather than exhaustive. We show market size and trajectory to establish context and strategic urgency, but detailed segment-level revenue splits, geographic shares, and application-specific pricing schedules are reserved for the full dataset. That granular intelligence—when combined with our scenario-enabled model and competitor scorecards—enables precise ROI calculations, supplier selection, product roadmaps, and M&A target lists tailored to a company’s risk tolerance and strategic ambition.
How executive teams should use this research in 2026
- Make the market baseline (2025) and the 2026–2032 projections the starting point for 3-year strategic plans—aligning R&D, procurement, and commercial KPIs to the projected CAGR and scenario outcomes.
- Use the procurement playbook to redesign supplier contracts with clauses addressing feedstock-price pass-through, CO2 metric reporting, and qualification timelines for alternative waxes.
- Prioritize tactical pilots for low-CO2 and sub-micron products with strategic customers to accelerate adoption and create commercial references—then scale manufacturing capacity matched to validated demand curves.
Conclusion — the strategic takeaway
For 2026, micronized wax market participants face a classic industrial-chemicals crossroad: modest but consistent growth, rising technical requirements, and an accelerating sustainability mandate. The winners will be those that convert technical differentiation into durable commercial advantage—through targeted product development, disciplined capital deployment, and tightly choreographed supplier-customer partnerships. PW Consulting’s full Micronized Wax Market report equips leaders with the quantitative models, competitive benchmarks, and hands-on playbooks required to move from observation to execution in 2026. To access the full segment tables, company scorecards, and scenario model, request the complete report on the PW Consulting portal.
For detailed analysis of this topic, please visit the official page: Micronized Wax Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


