



PW Consulting: Specialty Tire Market to reach USD 368.85 Million by 2032 at 6.98% CAGR

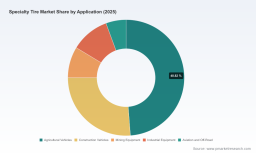
Specialty Tire Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive snapshot
The specialty tire market has entered a structurally attractive phase for disciplined players. Our baseline analysis (base year 2025) shows a sustained expansion since 2020 and a projected acceleration through the 2026–2032 forecast horizon at a compound annual growth rate of 6.98%. After recovering from the COVID-era shock, the market’s topline in our model expanded meaningfully to the 2025 base and is forecast to move materially higher by the end of the planning window. Market concentration remains meaningful: the top-three vendors control a majority share, and the top-five approach nearly seven in ten units of market share — conditions that favour scale-driven product investment but also create openings for focused challengers and high-value niche suppliers.
Specialty Tire Market
Why this report matters for 2026 decision-makers
-
Strategic clarity in a segmented industry: Specialty tires intersect heavy industry cycles, raw‑material swings and diverging end-user needs (agriculture, construction/mining, aviation, industrial/port). Each segment’s dynamics require bespoke commercial plays rather than one-size-fits-all approaches.
Specialty Tire Market -
Input-cost and supply-risk management: Natural rubber retained a dominant role in specialty compounding in 2025, accounting for a significant share of revenue in the market. This concentration creates both margin vulnerability and negotiating leverage opportunities for firms that proactively secure supply or innovate on material use.
Specialty Tire Market -
Competitive reconfiguration is underway: Recent strategic moves — most notably a leading OEM’s explicit industry refocus and exit from a large application segment — are already reshaping supplier maps, distribution flows and aftermarket potential. These changes accelerate consolidation and create rapid windows for selective M&A and route-to-market redesign.
-
Commercial timing: As 2026 planning cycles start, manufacturers, distributors and investors must translate medium-term growth projections into capital allocation, R&D roadmaps, and go‑to‑market execution plans that protect margins while capturing premium-service opportunities.
What this research delivers (practical contents you can act on)
Our full Specialty Tire Market study is built to inform decisions across strategy, commercial execution and transactions. Highlights include:
-
Proprietary market model: A granular historical build (2020–2025) and forward projections (2026–2032) by product family and application cluster, plus sensitivity scenarios for commodity and demand shocks. (Note: this preview intentionally omits detailed segment tables — access to full segment-level datasets is available via the full report.)
-
Demand-side intelligence: Buyer archetypes, replacement cycles, and total cost of ownership drivers across primary applications (agriculture, construction/mining, aviation, industrial/port).
-
Supply-chain and raw-material heatmaps: Supplier concentration, logistics bottlenecks, freight exposure and a quantified natural‑rubber dependency analysis to inform hedging and sourcing strategies.
-
Competitive benchmark and playbooks: Profiles of the market’s core competitors with capability matrices, capability gaps, and proven commercial playbooks for premiumization, customization and aftermarket monetization.
-
Technology and product roadmaps: Material substitution tradeoffs, retreading economics, telematics-enabled service offerings and design drivers for higher-load, electrified and autonomous machinery.
-
M&A and partnership scanner: Target screening criteria, valuation premia for high-margin niches, integration risk checklists and sample synergies for tuck-in and bolt-on transactions.
-
Risk and compliance register: Regulatory scenarios, environmental mandates, and quality-control frameworks tailored to specialty applications.
Competitive landscape — signals and strategic implications
Our competitive analysis focuses on incumbent leaders and agile specialists who set technology, service and supply standards. Leading global OEMs pursue differentiated strategies:
-
Premium engineering and specialized portfolios: Legacy premium manufacturers maintain a multiyear edge in aviation and ultra‑large mining OTR product performance and aftermarket trust. Their play is high R&D spend, long life-cycle warranties and global aftermarket service networks.
-
Material and weight-led innovation: Some global players leverage proprietary compounds and lightweighting chemistries to lower fuel and field-operational costs — a visible wedge in specialty agricultural and commercial applications.
-
Custom and engineered supply: Smaller, focused producers compete on rapid customization, shorter lead times and close OEM/contractor partnerships for bespoke off‑road and industrial use-cases.
-
Geographic and manufacturing footprint plays: Domestic manufacturing and localized service offerings are defensive advantages in certain end markets where lead time and service responsiveness trump lowest-cost imports.
Implication for 2026: incumbents must choose between deeper vertical specialization (technology and full-lifecycle services) and defensive scale (cost and distribution reach). Challenger brands should prioritize narrow, high-margin niches where service and customization create stickiness.
Market dynamics shaping 2026 strategic choices
-
Raw-material inflation and sourcing risk: With natural rubber a major component of specialty compounding, price spikes or supply disruption have outsized impact on margins. Firms that combine sourcing partnerships, limited vertical integration and material-science substitution roadmaps will mitigate cost pass-through risks.
-
Regulatory and portfolio reshuffles: The announced strategic refocus by a major competitor is an actionable market event — it alters capacity footprints and creates immediate aftermarket and OEM servicing opportunities for rivals and regional suppliers.
-
Technology-led differentiation: Telematics, retread optimization and advanced compounds enable suppliers to sell total-cost-of-ownership value rather than just product. Service-led business models increase lifetime margin and deepen customer relationships.
-
Aftermarket and retreading economics: As replacement cycles lengthen in some equipment classes, retreading and lifecycle services become both margin enhancers and sustainability differentiators.
-
Capital intensity vs. customization: High-volume OTR lines favor scale players; bespoke industrial and agricultural niches reward engineering agility. Capital allocation must therefore balance modular capacity investments with flexible manufacturing options.
Five strategic moves for 2026
-
Recalibrate portfolios to focus capital on higher‑value segments where technical differentiation drives pricing power. Protect and expand aftermarket services while pruning low-margin commodity exposure.
-
Lock in raw-material supply through blended strategies: preferred supplier agreements, financial hedges, and selective R&D into lower-dependency compound alternatives.
-
Invest in product-service bundles that monetise telematics data and lifecycle optimization — turn a one‑time sale into a recurring revenue stream.
-
Pursue targeted M&A and partnerships where incumbent exits or refocuses create capacity gaps — prioritize assets with aftermarket access, engineering IP or immediate route-to-market benefits.
-
Operationally de‑risk by building regional service hubs and flexible production cells to reduce lead times and improve cost-to-serve for high-value customers.
How PW Consulting can accelerate your 2026 program
We translate the modelled market view into executable plans. Our offer for senior teams includes custom data licensing of the full 2020–2032 model, scenario workshops that stress-test product and M&A strategies, supplier and channel diligence, and implementation blueprints for building service-led margin streams. For transaction teams we provide target screening, synergy quantification and integration playbooks calibrated to specialty‑tire economics.
Accessing the full intelligence
This preview is designed to surface the strategic value and practical uses of our Specialty Tire Market study while protecting the granular segment and regional tables that power operational decisions. If your 2026 plan requires the underlying segment-level estimates, application-by-application models, supplier lists, and company-by-company financial comparators (all excluded from this summary), the full report and accompanying datasets are available for licensed access.
Contact PW Consulting to schedule a briefing or request access to the full dataset and model — our team will walk you through scenario-specific implications and a 90‑day action plan tailored to your role (manufacturer, distributor, investor or OEM partner).
For detailed analysis of this topic, please visit the official page: Specialty Tire Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


