



PW Consulting: Website Builders Market to Expand at 16.58% CAGR, Hit USD 31.03M by 2032

Website Builders Market — 2026 Strategic Preview for Corporate Decision‑Makers
This briefing is a high‑value primer from PW Consulting’s latest Website Builders Market research, designed to equip senior executives, product leaders, investors, and M&A teams with the strategic orientation they need for 2026. It surfaces the structural forces shaping the market, translates headline growth into tactical implications, and outlines the practical analyses included in the full report — while intentionally withholding the granular segmentation tables that buyers and deal teams will want to download from our site.
Website Builders Market
Why this market matters now
Over a compressed growth cycle, website builders have evolved from consumer convenience tools into mission‑critical SaaS infrastructure for commerce, brand experience, and channel expansion. The total market expanded rapidly over the first half of the decade — rising from roughly USD 3 million in 2020 to USD 10.56 million in 2025 — and is projected to continue on a robust trajectory, surpassing USD 31 million by 2032 at a compound annual growth rate of 16.58%. That combination of scale and sustained growth makes this a strategic battleground for platform economics, developer ecosystems, and embedded commerce services.
Website Builders Market
What the growth represents — two simultaneous shifts
-
Platformization of digital experience: Buyers increasingly treat website builders not as isolated page editors but as platforms that must support commerce, subscriptions, integrations, and customer data flows. This drives higher average revenue per user for builders that can attach payments, fulfillment, and analytics.
Website Builders Market -
AI as productivity and product lever: Generative and assistive AI have moved from experimental to table stakes. From AI‑generated templates to prompt‑to‑production pipelines for entire sites and apps, vendors are monetizing AI through premium features, usage credits, and developer tooling.
Market dynamics executives must model in 2026
-
Rising infrastructure and energy costs: New regulation and grid effects (notably legislation governing data center energy reporting and regional transmission cost increases) are crystallizing a new cost reality for cloud and hosting. Expect hosting TCO and energy‑related compliance costs to become visible line items for both vendors and large enterprise customers, influencing procurement and hosting strategies.
-
Margin pressure from bundled services: Builders that expand into payments, payroll, or business finances can capture more value per account but also accept more credit, fraud, and regulatory exposure. The path from modular add‑ons to vertically integrated service provider increases ARPU but requires new capabilities and capital allocation.
-
Concentration of demand and platform differentiation: A handful of suppliers capture a substantial share of high‑value customers, creating winner‑take‑most dynamics in premium segments while leaving opportunity in verticalized and cost‑sensitive niches.
-
Speed of feature commoditization: Core UI editors and template libraries rapidly converge. Differentiation compresses into AI capabilities, workflow automation, extensibility (APIs, headless options), and partner ecosystems.
Competitive landscape — strategic posture of the leading vendors
The competitive map is anchored by a set of platform incumbents and fast‑moving specialists. Each has pursued distinct strategies that reveal the feasible plays for scale, specialization, and defensibility.
-
Squarespace — Positioned as a brand and design centric platform with integrated commerce and expanding financial tooling. Recent product refreshes emphasize intelligent tools for brand scaling and, most recently, a finance utility intended to reduce administrative friction for small business operators. Strategic takeaway: Squarespace is moving from site builder to business platform, which elevates cross‑sell potential but also increases exposure to non‑core regulatory and credit risks.
-
Shopify — Continues to focus on commerce‑first experiences, combining storefront tooling with increasingly sophisticated AI assistance and inventory/fulfillment integrations. Its playbook is ecosystem expansion — payments, logistics partners, and developer extensions — aiming to keep commerce customers inside its stack. Strategic takeaway: Shopify remains the default for merchant‑centric use cases; competitors must out‑specialize or partner to win share in vertical retail niches.
-
Wix — Emphasizes no‑code ease, AI site generation, and a broad set of SMB features (bookings, basic commerce). Its strategy is breadth and accessibility, with monetization through verticalized apps and premium plans. Strategic takeaway: Wix is optimized for scale and price sensitivity, making it a competitive choice for high‑volume, low‑touch customer acquisition.
-
Webflow — Occupies a higher‑end niche with a visual, code‑aware design environment and a strong CMS. Its 2025/26 moves into AI for prompt‑to‑production workflows and simplified team plans indicate a push to capture creative professionals and small agencies that require both design precision and collaboration. Strategic takeaway: Webflow’s premium positioning allows higher monetization, but it must extend developer and platform economics to fully exploit enterprise demand.
-
GoDaddy — Leverages domain and SMB relationships, bundling website tools with domain services and AI agents to simplify small business onboarding. Strategic takeaway: GoDaddy’s advantage is incumbent customer relationships; retaining customers requires continued investment in AI‑enabled onboarding and localized support.
-
Hostinger — Competes on cost and integrated hosting, appealing to value‑conscious customers who prefer an all‑in‑one stack. Strategic takeaway: Hostinger’s success depends on balancing low price points with a credible product roadmap for AI and extensibility to avoid being cornered into a pure commodity play.
Recent vendor moves to watch (signal vs. noise)
-
Product refreshes that combine AI design with business tooling indicate a shift from feature sales to outcome sales — customers buy “launch and monetize” packages, not just editors.
-
Conference and product announcements around “prompt‑to‑production” capabilities mark an inflection where creative workflows can be dramatically compressed, changing the economics of design agencies and in‑house teams.
-
Plan and pricing simplifications, including AI credit models, suggest incumbents are testing ways to meter compute and feature usage without introducing churn through complex SKU proliferation.
What’s in the full PW Consulting report (practical, hands‑on deliverables)
-
Market sizing and forecast model (2026–2032): a transparent methodology, scenario variants, and an interactive forecast workbook that lets clients stress different assumptions (AI adoption, hosting cost inflation, enterprise conversion rates).
-
Demand archetypes and buyer journey maps: segmented profiles for enterprise, SMB, agency, and developer buyers highlighting procurement triggers, TCO sensitivity, and switching frictions.
-
Go‑to‑market playbooks: tactical plans for product, pricing, partner channels, and OEM agreements tailored to vendors seeking share in high‑value segments.
-
Technology and integration playbook: recommended architectures for AI, headless delivery, and multi‑region hosting to balance performance, compliance, and cost.
-
Vendor profiles and competitive heatmaps: strategic positioning, product strengths, monetization levers, and near‑term roadmaps for the top platforms (detailed profiles in the full report).
-
Risk matrix and regulatory sensitivity analysis: impact assessments for energy‑reporting laws, regional transmission cost pass‑throughs, and privacy/compliance regimes.
-
M&A and investment diagnostic: target typologies, valuation multiples benchmarked to growth and ARPU, and a transaction playbook for buyers and PE sponsors.
Actionable recommendations for 2026 decision cycles
-
For platform vendors: prioritize modular add‑ons that convert free users to paid customers within 6–12 months. Monetize AI as a feature bundle with clear outcomes (time to publish, conversion lift) rather than as an abstract capability.
-
For enterprise buyers: insist on transparent hosting TCO and carbon/energy disclosures during procurement. Bundle procurement negotiations with commitments on SLAs tied to edge performance and data locality.
-
For investors and M&A teams: screen targets for defensible developer ecosystems, predictable monetization paths (payments, subscriptions, premium services), and exposure to hosting cost volatility. Prefer targets with sticky integrations into commerce or finance flows.
-
For digital agencies and system integrators: evolve service offerings from build‑only to an outcomes model (growth, conversion, automation), and use AI toolchains to compress delivery time while maintaining premium pricing for strategic capabilities.
What we hide (and why you need the full dataset)
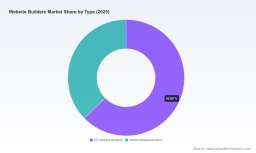
To maintain the “trailer” spirit of this briefing, we have deliberately withheld the granular regional, type, and application split tables, and detailed entity market shares that power our valuation and GTM scenarios. Those segmented datasets — crucial for deal modeling, regional expansion plans, and product prioritization — are available in the full report and the downloadable forecast workbook on our website. The headline growth and strategic implications above are drawn from that underlying work, but the micro‑level numbers are gated because they are the action‑oriented intelligence buyers and investors rely on.
Next steps — how to use this briefing
-
Download the forecast workbook to run sensitivity tests against hosting cost inflation, AI consumption, and varying enterprise adoption curves.
-
Request a tailored session with PW Consulting to map the report’s insights to your product roadmap, M&A pipeline, or procurement strategy.
-
Subscribe to our executive briefings for quarterly updates as vendor roadmaps and regulatory tensions (energy reporting and grid impacts) evolve through 2026 and beyond.
In a market growing at a sustained double‑digit rate, strategic clarity — not data noise — is the competitive advantage. PW Consulting’s Website Builders Market research converts expansive datasets into decision frameworks you can act on in 2026. Visit our site to access the full report and datasets that underpin the analysis summarized here.
For detailed analysis of this topic, please visit the official page: Website Builders Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


