



PW Consulting: Carnauba Wax Market Poised for 4.2% CAGR (2026–2032)

Carnauba Wax Market 2026: Strategic Intelligence Briefing for Decision-Makers
Executive snapshot
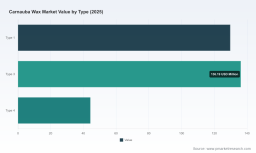
As demand for natural specialty waxes matures into a risk-managed commodity, the global Carnauba Wax market is transitioning from niche raw-material sourcing to strategically governed supply chains. PW Consulting’s forthcoming report (base year 2025, forecast 2026–2032) positions market leaders and buyers to convert volatility into advantage. The market expanded from roughly USD 243 million in 2020 to about USD 310 million in 2025 and, under our central forecast, moves toward roughly USD 414 million by 2032 — a compound annual growth rate of 4.2% through the forecast window. These headline metrics capture steady long-term demand while underscoring short-term price and supply oscillations that merit active management in 2026.
Carnauba Wax Market
Why this research matters for 2026 corporate decisions
-
Policy and trade rebalancing is altering competitive economics. Recent changes in tariff policy and bilateral actions have meaningfully improved export economics for Brazilian producers, reconfiguring supplier selection and total landed-cost calculations for downstream users. That shift creates immediate procurement opportunities — and transitional risk for incumbents that have not updated sourcing strategies.
Carnauba Wax Market -
Supply-side signals are noisy but directional. Brazilian export volumes from key producing states accelerated sharply year-on-year, and price volatility in 2024 spanned a wide band. Those dynamics translate into episodic cost spikes for manufacturers, and they change the calculus for inventory policy, hedging, and long-term sourcing commitments.
Carnauba Wax Market -
Sustainability is now a commercial gate. Leading producers have converted environmental performance into market access — achieving third-party targets and awards well ahead of peers. Buyers that cannot demonstrate responsible sourcing and traceability will face increasing regulatory and customer friction in core end-markets.
Market behaviour in 2026: what the numbers tell us (high level)
The aggregate data show a market that is growing at a mid-single-digit pace, with intermittent dips reflecting cyclical rebalancing. In the near term, expect shorter supply-squeeze episodes driven by raw-material availability and logistical constraints, followed by renewed growth as new trade conditions settle. These macro patterns make 2026 a turning point year: companies that act early to redesign procurement, lock in sustainability credentials, and optimize formulations will capture outsized margin and share gains.
Competitive landscape — strategic positions to watch
Our review of active participants highlights a clear bifurcation in strategic positioning: vertically integrated Brazilian producers focused on ethical sourcing and certification; and specialist refiners and distributors in North America and Europe supplying custom grades, value-added analytics, and formulation support. The leading manufacturers are leveraging certifications, emission-reduction milestones, and circularity programs to secure premium channels and long-term contracts. Distributors and formulators are differentiating through technical service, blended offerings, and regulatory compliance support.
-
Brazilian exporters and refiners — firms with on-the-ground extraction, refining capability, and third-party sustainability credentials are capitalizing on improved export economics and rising international demand. Their strategic advantage is control over raw material sourcing, certification narratives, and scale of refined product lines.
-
North American and European processors/distributors — companies emphasizing custom grades, analytical testing, and technical application support remain indispensable for customers in cosmetics, automotive, pharmaceutical and specialty coatings. Their value proposition is integration into formulations and shortened time-to-market for product innovation.
-
Service and formulation specialists — chemical formulators and additives companies that embed Carnauba into polymer, rubber and coating systems can capture incremental value through co-development, protecting margins against raw-material swings.
Recent developments that change the playbook
-
Trade policy revisions late in 2025 substantially improved export competitiveness for incumbent producing regions. Buyers should re-run landed-cost models to reflect the new tariff landscape and identify arbitrage windows.
-
Top producers have accelerated sustainability credentials: major firms reported significant emissions reductions ahead of plan and received recognition for environmental transparency in early 2026 — an advantage that translates into procurement preference in regulated markets.
-
Observed price dispersion across 2024 underscores the need for granular price-benchmarking and scenario planning; volatility materially changes inventory and contract-design recommendations.
Strategic implications — what companies should do in 2026
-
Reassess total landed cost and sourcing mix: With tariffs reduced and export flows accelerating, organizations should reconstruct cost models across multiple supplier origins and transport modes. Short-term spot purchases may appear cheaper but can increase exposure to price spikes; hybrid strategies (short-term hedges + staggered contract coverage) are often optimal.
-
Prioritise certified supply chains: Certifications and documented emission reductions are increasingly table stakes. Procurement teams must embed sustainability clauses, audit rights, and traceability requirements into contracts to preserve market access and brand claims.
-
De-risk with technical partnerships: For manufacturers dependent on performance consistency (e.g., cosmetics or coatings), partnerships with refiners who provide analytics and custom grades reduce reformulation risk and accelerate innovation.
-
Design scenario-based inventory policy: Given observed volatility ranges, adopt a tiered inventory strategy that blends safety stock for critical grades with supplier options that can be activated under predefined triggers.
-
Screen M&A and JV targets against sustainability and traceability KPIs: Acquisition targets that immediately close capability gaps — e.g., certified extraction, refining scale, or regional distribution — should be prioritized in 2026 deal flows.
What PW Consulting’s full report delivers (practical contents)
- Robust market sizing and validated forecasts (2020–2032), including sensitivity scenarios and a clear articulation of assumptions behind the 4.2% CAGR.
- Price-benchmark dashboards and historical volatility analysis with unit-level benchmarking to inform procurement negotiation and hedging.
- Supply-chain maps and country-risk heatmaps exposing single-point dependencies and logistics chokepoints.
- Sustainability scorecards and supplier due-diligence templates aligned to international standards and procurement decision frameworks.
- Commercial playbooks and procurement clauses for short, medium and long-term sourcing; negotiation levers; and contract templates for certified-supply commitments.
- Competitive company profiles and go-to-market assessments of key players, including strategic SWOTs and partner-fit matrices.
- M&A screening framework with valuation sensitivities tied to certification premiums, margin uplift potential, and integration risk.
- Primary-interview excerpts, methodology appendix, and a downloadable model allowing users to run their own scenarios.
How to use this intelligence in 90–365 day plans
-
0–90 days: Reprice recent tenders incorporating new tariff structures, engage top-tier certified suppliers for pilot contracts, and set a strategic inventory buffer for critical grades.
-
90–180 days: Execute supplier audits focused on traceability and sustainability, develop technical co-development projects with refiners, and formalize hedging or forward purchase programs.
-
180–365 days: Pursue strategic partnerships or targeted M&A to secure upstream capacity or downstream formulation capabilities; embed sustainability KPIs into executive scorecards and procurement governance.
What we deliberately withhold here — and why
This briefing demonstrates the type of actionable insight contained in PW Consulting’s full Carnauba Wax Market report. To preserve the value of our primary research and to ensure clients derive commercial advantage, detailed sub‑segment datapoints (region‑ and application-level splits, supplier market shares by volume, and certain price-by-grade matrices) are not published in this preview. The full dataset and model, which power the precise contract- and M&A-level recommendations, are available via our report portal.
Final note — the strategic opportunity
2026 is a year of structural repositioning for Carnauba Wax value chains: trade realignment, accelerating certification premiums, and sustained end-market demand create windows for competitors to lock in advantage. PW Consulting’s research converts raw market signals into executable strategy — from procurement redesign to M&A screening and product innovation. For organisations that treat this year as an inflection point rather than a continuation of past practice, the upside is measurable and immediate.
To access the full report, model, and supplier playbooks — and to schedule a bespoke briefing aligned to your portfolio — please visit the PW Consulting Carnauba Wax Market page or contact our industry team for a confidential walkthrough.
For detailed analysis of this topic, please visit the official page: Carnauba Wax Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


