



PW Consulting: AV Receiver Market — 5.45% CAGR to USD 232M by 2032

AV Receiver Market — Strategic Outlook for 2026 Decision‑Makers
As companies evaluate product roadmaps, channel investments and M&A opportunities for 2026, the AV receiver market presents a blend of steady growth, product-driven renewal and concentrated competitive dynamics. PW Consulting’s latest market research — grounded on a 2025 base year and a historical review through 2020–2025 — models the market through 2032 and crystallizes implications for executive decision-making. This executive introduction summarizes the high‑value strategic takeaways you need now, while preserving the granular segment-level intelligence found in the full report to reward a direct download.
AV Receiver Market
Market snapshot: measured growth, product refresh cycles, strategic leverage
Our topline modeling shows the AV receiver market expanding at a compound annual growth rate (CAGR) of 5.45% through the forecast window, reflecting a market that is neither hyper‑cyclical nor stagnant but instead driven by recurring product refresh cycles, gradual premiumization and intermittent technology step‑changes. Measured in USD (Million), the market recovered from near-term softness in the early 2020s and reached an estimated USD 160.0 million in 2025. PW Consulting’s baseline projection sees the market climbing to approximately USD 232.0 million by 2032, underscoring meaningful upside for firms that align product, channel and service moves with evolving consumer expectations.
AV Receiver Market
Notably, the 2020–2025 historical run shows both volatility and resilience — a dip followed by recovery — which underscores two practical planning imperatives: maintain portfolio flexibility to absorb short‑cycle shocks, and preserve optionality in premium segments where ASPs (average selling prices) and margin pools are expanding.
AV Receiver Market
Why this research matters for 2026 decisions
- Capital allocation with precision. A 5.45% CAGR implies compounding rather than explosive growth. For CFOs and strategy teams, that means prioritizing investments that accelerate share in higher‑margin, experience‑first product tiers (e.g., immersive audio and multi‑zone systems) rather than chasing broadmarket volume with thin margins.
- Timing product refreshes. The market’s pulse is set by periodic format and connectivity upgrades (HDMI evolutions, immersive audio standards, streaming ecosystems). Our scenario timelines help R&D leaders plan 12–36 month refresh windows to avoid being year‑late on critical HDMI/codec or streaming integrations.
- Channel and go‑to‑market optimization. Brick‑and‑mortar, specialist dealers, eCommerce and bundled subscription models each show distinct economics. Executives can use our modeled channel matrices to decide where to prioritize promotional funding, service bundling and partner incentives in 2026.
- M&A and partnership scouting. With visible concentration in the market’s top tier, targeted acquisitions—capabilities, IP or go‑to‑market reach—can accelerate scale without the full cost of organic growth. Our competitive overlays flag logical consolidation corridors.
What PW Consulting’s full report delivers (high‑value, operationally actionable)
The full study is engineered for commercial teams and executive committees that must convert market intelligence into executable plans. Key deliverables include:
- Forward-looking revenue and margin models (2026–2032) with scenario toggles for technology adoption rates, ASP movement and channel mix shifts.
- Investment heatmaps identifying high‑ROI R&D features (e.g., immersive decoding, advanced room correction, HDMI bandwidth upgrades), prioritized by short and medium-term impact.
- Go‑to‑market playbooks for premium vs entry segments: channel economics, promotional levers, demo/retail experiences, and subscription or services bundling strategies.
- Competitive scorecards and supplier risk matrices to inform procurement and contract renewal strategies, including semiconductor and PCB supplier concentration assessments.
- M&A screening frameworks: candidate profiles, valuation heuristics and integration checklists for capability and distribution deals.
- Commercial toolkits — pricing elasticity curves, SKU rationalization templates, and playbooks for launching regionally tailored promotional campaigns.
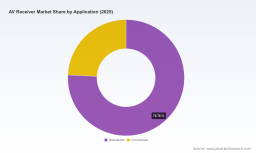
We intentionally present synthesis and strategic implications here, and preserve the detailed regional, type and application split tables, as well as the raw model, behind the report paywall to protect the precision that our clients rely on.
Competitive landscape: incumbents, product vectors and differentiators
The industry exhibits moderate concentration at the top: our market concentration metrics show the three largest players account for a majority share and the top five consolidate a meaningful plurality. That concentration drives distinct competitive dynamics: incumbents defend share through integrated ecosystems and premium feature sets, while smaller specialist brands compete on bespoke audio fidelity and enthusiast credentials.
- Yamaha Corporation (Hamamatsu, Japan) — Yamaha’s Aventage and RX series continue to anchor their strategy: blending premium chassis and processing with ecosystem streaming (MusicCast) and broader 8K/4K HDMI 2.1 support. Their 2026 launches, including new entry-focused RX300A/RX500A units, show a two‑pronged approach: defend high‑margin audiophile buyers while expanding addressable units in mainstream home theater.
- Sony Corporation (Tokyo, Japan) — Sony leverages its content and display heritage to offer receivers integrated with immersive audio and video roadmaps. Their STR series focuses on tight integration with TV and soundbar ecosystems, an advantage in bundled retail placements and living room consolidation trends.
- Harman International (Stamford, CT, USA) — Through Denon and Marantz, Harman emphasizes HEOS streaming, high‑resolution decoding and premium AVR feature sets. The May 2026 Denon AVR-S980H release signals continued investment in upgraded connectivity and accessibility in the mid‑to‑upper shelves.
- Premium Audio Company / Onkyo (Billerica, MA, USA) — Onkyo’s refreshed RZ series and TX family underscore their strengths in advanced processing (Dirac Live, THX certification) and higher channel counts such as 9.2 processing — a play for enthusiast and dedicated cinema build markets.
- Arcam (Cambridge, UK) — Arcam’s HDA range positions the brand on high‑fidelity performance and premium decoding architectures, targeting users for whom audio purity and chassis engineering justify premium pricing.
Recent product activity in May 2026 (new models from Yamaha, Harman/Denon and Onkyo) illustrates how incumbents are refreshing entry and mid tiers simultaneously — a signal that they aim to protect market share across price points rather than ceding ground to disruptors.
Strategic plays companies should consider in 2026
- Prioritize experience‑driving features that customers will pay for. Dolby Atmos, DTS:X, advanced room calibration (Dirac Live), and robust streaming integration are differentiators. Invest selectively in features that lift ASPs and reduce price elasticity in target channels.
- Design SKU rationalization around channel economics. Too many SKUs increase supply chain cost and dilute margins. Use our channel‑level elasticity models to reduce SKUs where eCommerce dominates and expand specialized SKUs where dealer experience matters.
- Bundle services to capture recurring revenue. Extended warranties, calibration services, and premium streaming integrations can convert one‑time buyers into longer‑life customers and stabilize revenue in a market with a moderate CAGR.
- Hedge supply risk with dual‑sourcing and inventory strategies. Connectivity component availability (HDMI controllers, audio DSPs) will shape time‑to‑market. Tactical inventory and supplier relationship protocols reduce product launch risk.
- Use M&A to plug capability gaps. If in‑house audio processing or streaming stacks lag, acquiring targeted IP or a small OEM with cult brand equity can be faster and cheaper than multi‑year internal builds.
Methodology, disclosure and how to obtain the full intelligence
PW Consulting’s report is based on a base year of 2025, a historical dataset spanning 2020–2025 and a forecast period covering 2026–2032. The model outputs are denominated in USD (Million), and the headline CAGR used in our scenarios is 5.45%. Market concentration metrics indicate the top three firms control roughly half the market, with the top five approaching a majority — a dynamic that shapes pricing, distribution and product strategies.
Consistent with the “trailer” approach of this note, we have intentionally withheld granular regional, type and application splits, and the downloadable model behind the full report contains the precise tables, segment‑level forecasts, regional dynamics and sensitivity analyses needed for implementation. The full package also includes executable templates — financial models, GTM playbooks, supplier scorecards and an M&A screening tool — designed to be used in boardroom planning sessions and investor diligence in 2026.
For strategy teams, product leaders and investors preparing plans and capital allocations for 2026, PW Consulting’s AV Receiver Market report is designed to move beyond descriptive analysis toward operationally usable prescriptions. The market is growing modestly but meaningfully; success will depend on selecting the right feature investments, channel strategies and partnership plays to convert that growth into sustainable margin expansion.
Next steps
- Download the full report and financial model to unlock regional and application splits, price and unit forecasts, and the complete competitive benchmarking dataset.
- Book a rapid‑response briefing with PW Consulting’s AV team to map these findings directly onto your 2026 P&L and product roadmap.
- Engage our M&A and commercial teams for targeted screening and integration planning if you are considering consolidation or capability acquisitions.
PW Consulting’s work is purposefully action‑oriented: read this note as the strategic trailer, and let the full report be the operational playbook that turns market insight into measurable outcomes for 2026.
For detailed analysis of this topic, please visit the official page: AV Receiver Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


