



PW Consulting: Self-service Kiosk Market to Reach USD 10.13B by 2032 at 7.68% CAGR

Self‑service Kiosk Market — Strategic Preview for 2026 Decision‑Makers
As organizations finalize budgets and channel strategies for 2026, the self‑service kiosk market is entering a phase where technology, regulation, and cost pressures are colliding to create clear winners and losers. This preview, prepared by PW Consulting’s senior strategy team and industry analysts, synthesizes the macro trajectory and the practical decision points executives must prioritize this year. We show the high‑level evidence you need to evaluate investment timing, vendor choices, and compliance risk — while intentionally withholding the granular segmentation tables and proprietary model outputs to reserve the full playbook for the complete report.
Self-service Kiosk Market
Headline market signal (what the numbers tell you)
The market has moved from an established niche into broad commercial adoption. Measured on a USD billion basis, the global self‑service kiosk market expanded from around 4.2 billion in 2020 to roughly 6.1 billion in 2025. Our model projects continued momentum into the decade: with a compound annual growth rate of 7.68% across the forecast window (2026–2032), the market is projected to exceed 10 billion by the end of the forecast period. This growth is not just incremental hardware replacement — it reflects recurring software, managed services, and transaction value streams accruing to ecosystem participants.
Self-service Kiosk Market
Why this briefing matters for 2026 decisions
- Budget allocation is time‑sensitive: Suppliers with proven TCO frameworks and service models are already shifting from product sales to subscription and outcome‑based contracts. Procurement teams must evaluate multi‑year service commitments rather than one‑off capital buys.
- Regulatory compliance is a gating factor: New accessibility and digital service mandates — including federal and state level actions that take effect in 2026 — are redefining minimum viable kiosk capabilities. Non‑compliant deployments expose organizations to legal and operational interruption risks.
- Labor economics are driving adoption: Across sectors surveyed in our research, organizations consistently rate frontline labor reduction as a top priority; this is reflected in prioritization metrics where nearly all operators rank automation as critical to achieving cost and continuity objectives.
- Privacy and security are strategic differentiators: Emerging requirements to embed privacy‑by‑design and stronger transaction data protections mean software, identity, and payment partners now carry as much strategic weight as enclosure manufacturers.
Dynamics shaping the market in 2026
- Regulatory inflection points: Accessibility rules now require that government and public transaction kiosks meet WCAG standards and full transaction accessibility; health sector enforcement of accessibility rules has also intensified. Separately, new state licensing for digital financial asset kiosks imposes operational licensing and oversight obligations for deployers and operators.
- Compliance eats design: The combination of accessibility, privacy, and financial licensing is forcing product roadmaps to prioritize configurable UI/UX, auditable transaction flows, and certifiable security stacks. These are non‑trivial engineering lifts for legacy kiosk vendors.
- Shift from hardware to outcome selling: Vendors who can bundle hardware, managed services, analytics, and lifecycle replacement plans are winning larger, multi‑year engagements. Buyers should expect to trade higher upfront costs for predictable OPEX and lower in‑service friction.
- Workforce and service model pressures: Labor constraints continue to be a primary push factor for deployments. Operators report automation as a 96% priority for reducing frontline staffing costs — a near‑universal driver across retail, hospitality and public sector use cases.
Interpreting the trajectory: growth quality over quantity
Growth at a near‑8% CAGR reflects both broader adoption and product evolution. Three important qualitative observations emerge from our analysis:
Self-service Kiosk Market
- The market’s revenue mix is diversifying. Recurring revenue from software subscriptions, payments processing, and managed services is growing faster than one‑time hardware sales.
- Interoperability and integration are prerequisites. Buyers increasingly insist on open APIs, standard payment/security certifications, and cloud management capabilities as conditions of purchase.
- Regulatory compliance is imposing discipline on procurement. Accessibility and privacy requirements have elevated compliance checks from a checkbox exercise to a procurement gating process, meaning vendors without documented practices are being filtered out early.
Competitive landscape — the players and what they signal
The market is moderately consolidated: the top three vendors account for nearly half of reported market share, and the top five for close to three‑fifths. That concentration signals a market where scale and integrated capability matter. Below we profile the principal vendors that shape industry direction and vendor selection:
- KIOSK Information Systems (Thornton, Colorado) — A specialist in custom kiosk hardware, software stacks and managed deployments across healthcare, government and commercial use cases. Recent corporate realignment — including a headquarters relocation announced in late 2025 — underscores a strategic focus on scaling managed service operations and secure deployments.
- Olea Kiosks (Cerritos, California) — Known for combining standard and custom enclosures with biometric integrations. In 2026 Olea published guidance emphasizing invisible, frictionless customer experiences and lifecycle cost analytics — signalling vendor maturity in TCO methodologies that purchasers should demand.
- Meridian Kiosks (North Carolina) — Offers integrated kiosk and digital signage solutions for commercial environments, positioning itself as a one‑stop supplier for multi‑format deployments and OOH interaction strategies.
- Advanced Kiosks (USA) — Focuses on rugged and ADA‑compliant designs for government and turnkey projects, which makes them a go‑to for regulated deployments requiring strict compliance documentation.
- REDYREF (United States) — Concentrates on interactive touch solutions for transaction and check‑in flows; a practical choice for high‑volume, service‑oriented environments seeking responsive HMI.
- NCR Corporation (Atlanta, Georgia) — Brings deep payment and POS integration expertise, appealing to large retail and QSR operators that need unified transaction ecosystems.
- Diebold Nixdorf (United States) — A leader where security and regulatory assurance matter — notably in banking and finance — due to its heritage in secure transaction devices.
- Glory Global Solutions (United Kingdom) — Specializes in payment and cash‑handling kiosks, making them relevant for cash‑heavy operations transitioning to hybrid cash/digital models.
- Zebra Technologies (United States) — Supplies rugged hardware and integrated peripherals that underpin kiosk systems in logistics, healthcare and industrial settings.
Recent vendor developments reinforce two strategic patterns: (1) vendors are publishing prescriptive buyer guidance and TCO tools, and (2) vendors with compliance and managed‑service capabilities are winning repeatable, enterprise deals. These patterns should shape vendor selection criteria for 2026 projects.
Practical priorities for buyers in 2026
For organizations planning deployments or scale‑ups this year, our fieldwork and modelling indicate five immediate actions:
- Mandate documented TCO and LCOE: Require vendors to supply a lifecycle cost model, replacement cadence, and remote management SLAs as part of RFP responses. Ask for scenario analyses that include regulatory remediation costs.
- Validate accessibility and privacy certification: Ensure kiosks and software stacks include demonstrable WCAG conformance, auditable logs, and privacy‑by‑design documentation — not just commitments.
- Design for interoperability: Prioritize open APIs, standard payment certification, and modular hardware so you can swap components without re‑architecting your stack.
- Plan for managed services and software updates: Make patching, remote diagnostics, and analytics part of the procurement baseline. Treat service providers as strategic partners rather than suppliers.
- Proof of Value over proof of concept: Run short, revenue‑linked pilots that validate integration, accessibility, and operational metrics (throughput, uptime, transaction error rates) before committing to wide rollouts.
What the full PW Consulting report delivers
The complete market study, anchored on a 2025 base year and projecting through 2032, provides the executable intelligence procurement and strategy teams need to act in 2026. Highlights include:
- Historical market modelling (2020–2025) and a detailed forecast model (2026–2032) with scenario sensitivities that reflect regulatory, technology, and macro labor inputs.
- Vendor scorecards with capability matrices across hardware, software, services, compliance readiness, and ecosystem partnerships.
- A procurement playbook and an operational checklist that map to real‑world procurement cycles, pilot designs, and KPIs used by leading deployers.
- Practical tools: TCO/LCOE templates, accessibility compliance checklists, and a risk register for regulatory and licensing exposures specific to digital finance and public sector deployments.
- Case studies demonstrating cost and operational outcomes from recent enterprise rollouts, and a framework to translate those outcomes into your own business case.
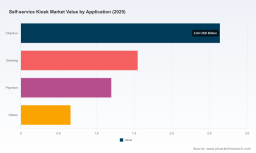
Note: this preview intentionally omits granular regional and application splits and specific segment revenue tables to preserve the integrity of the full analytical model. If your 2026 decisions require those detailed splits, the full dataset and vendor appendices are available through PW Consulting’s report portal.
Conclusion — a 2026 strategic checklist
Investments in kiosks in 2026 are no longer tactical stopgaps; they are structural moves that shape customer experience, labor economics, and regulated service compliance. With the market growing from just over 6 billion in our 2025 base year toward a double‑digit billion market by the end of the forecast, executives must treat kiosk initiatives as integrated technology and compliance programs. Prioritize vendors who can demonstrate documented TCO, accessibility certification, and end‑to‑end service capabilities. Use pilots that measure operational KPIs, not just UX. And expect contracting to shift toward outcome‑linked, service‑oriented commercial models.
PW Consulting stands ready to help translate this market intelligence into procurement specifications, vendor shortlists, and deployment roadmaps that reduce risk and accelerate value capture in 2026. For access to the full market model, detailed segment tables, and downloadable procurement templates, consult the full report.
For detailed analysis of this topic, please visit the official page: Self-service Kiosk Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


