



PW Consulting: Diagnostic ECG Market to Reach USD 14,020M by 2032 at 7.5% CAGR

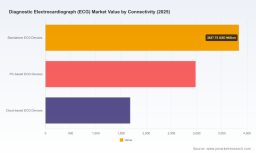
Diagnostic Electrocardiograph (ECG) Market — Strategic Preview for 2026 Decision-Making
As healthcare providers, device manufacturers and investors prepare budgets and product roadmaps for 2026, the Diagnostic Electrocardiograph (ECG) market presents both a growth runway and a set of disruptive inflection points. PW Consulting’s Diagnostic ECG Market study (base year 2025) synthesizes five years of historical dynamics and a seven-year forecast horizon (2026–2032) to deliver actionable insight. In short: the market has expanded materially since 2020 and, at a steady compound annual growth rate (CAGR) of 7.5%, is projected to continue its climb through 2032. This preview outlines why that projection matters to your 2026 decisions, what the full study contains, and the specific strategic moves we recommend while withholding the granular subsegment tableaux that will be available in the full report.
Diagnostic Electrocardiograph (ECG) Market
Executive snapshot
Between 2020 and 2025 the overall diagnostic ECG market recorded consistent expansion. That growth is driven by converging trends: tighter clinical pathways for cardiac disease detection, a wave of regulatory clearances for AI-enabled interpretations, new reimbursement codes for remote monitoring, and rapid product innovation across portable, wearable and cloud-enabled platforms. The market’s mid-single-digit to high-single-digit growth profile creates predictable expansion for incumbents while offering differentiated opportunity windows for agile entrants and software-first players.
Diagnostic Electrocardiograph (ECG) Market
Why this matters for 2026
-
Budget cycles and product development timelines calibrated in 2026 will determine market share through 2028–2030: regulatory lead times and clinical validation take months to years; decisions made in early 2026 that prioritize AI, connectivity and reimbursement-aligned workflows will compound advantage.
Diagnostic Electrocardiograph (ECG) Market -
Reimbursement and regulation are active levers. New reimbursement pathways for extended ECG monitoring and updated regulatory guidance on electrode safety and AI clinical evidence are reshaping procurement criteria for providers.
-
Market concentration is moderate: the top three and top five players together do not dominate the market to the point of insurmountable barrier-to-entry. That structure favors targeted M&A, vertical partnerships, and platform plays rather than winner-takes-all outcomes.
What the PW Diagnostic ECG Market report delivers (practical, decision-ready content)
-
Transparent methodology: market-sizing approach, addressable market assumptions, data sources and confidence intervals so finance teams can stress-test scenarios.
-
Full forecast model (2026–2032) with scenario sensitivity by adoption curves and pricing assumptions — provided in downloadable spreadsheets for immediate use in board and investor presentations.
-
Go-to-market playbooks tailored to manufacturers, medtech startups and SaaS/AI providers, including channel economics, procurement timelines, and hospital purchasing archetypes.
-
Regulatory and reimbursement navigator: matrix of global regulatory touchpoints, clinical evidence expectations, and payer coding impacts that directly affect time-to-revenue.
-
Competitive intelligence dossiers: concise strategic profiles for the leading firms, recent product news, inferred capability maps and tactical options for partnership or competition.
-
M&A and investment thesis: prioritized target lists, valuation benchmarks and integration risk checklists for buyers focused on hardware, embedded software, or cloud/analytics assets.
-
Operational checklists: supply-chain resilience templates, manufacturing scale-up milestones and certification timelines to align engineering and commercial milestones.
Market dynamics and growth drivers
The market’s projected expansion is not uniform; it is driven by a handful of persistent forces. Demographic pressure and prevalence of cardiovascular disease keep clinical volumes elevated. Parallel to that, two structural shifts accelerate unit demand and dollars-per-patient: first, the migration from episodic in-clinic testing to continuous or extended monitoring programs that capture higher lifetime value per patient; second, the software-enabled redefinition of what an ECG device is — hardware increasingly bundled with cloud analytics, AI interpretation, and remote monitoring services.
Technology maturation is also altering the investment calculus. AI-based ECG interpretation has crossed important regulatory milestones and is starting to move from adjunctive to cleared clinical decision support in several markets. Meanwhile, wireless and form-factor innovation reduces deployment friction in outpatient and home-care pathways, expanding addressable use cases.
Regulatory and reimbursement inflection points
-
Regulatory authorities are codifying expectations for electrode materials and AI clinical evidence. Manufacturers must accelerate clinical plans and post-market surveillance to meet tightened requirements while maintaining speed to market.
-
Reimbursement changes for remote/extended monitoring are already changing revenue recognition patterns — programs that capture 30-day monitoring episodes can justify more substantial upfront device and services investments.
-
European device approvals under MDR continue to require robust clinical evidence packages; strategy that succeeds in Europe must combine device performance data with health-economic outcomes.
Competitive landscape: who’s moving, and what it means
The market combines established capital-intensive OEMs with nimble, software-first entrants. Notable players include long-standing device manufacturers with integrated enterprise ECG management platforms, alongside innovators delivering portable, AI-enabled and cable-free solutions. Recent public developments illustrate the competitive vectors you should monitor:
-
AI and expanded diagnostic scope: A leading mobile ECG vendor received regulatory clearance in early 2026 for advanced AI determinations, broadening its clinical indications and strengthening its platform value proposition to ambulatory care providers.
-
Cable-free synthesis and alternative form factors: A cable-free 3D-synthesis provider secured clearance for 12-lead synthesis in late 2025, lowering friction for remote cardiac assessment and challenging wire-bound incumbents.
-
Geographic and channel expansion: An incumbent received CE marking in 2025 for a portable 12-lead device, accelerating European market access and underscoring the payoff of regulatory investment.
-
Workflow-focused launches: New resting ECG models announced in 2026 emphasize simplified workflows and interoperability, aiming to shorten procurement deliberation cycles in hospital cardiology suites.
These moves underscore how value is shifting: winners will combine reliable hardware, validated analytics and enterprise-grade data management — not hardware alone.
Implications for strategic decision-making in 2026
For boards and executive teams, 2026 is the year to make choices that lock in 2028 outcomes. Our study highlights several priority actions:
-
Prioritize clinical validation and regulatory sequencing. If your 2026 roadmap includes AI-enabled features, allocate sufficient budget and timelines for clinical trials and regulatory submissions now — delay costs more than accelerated spend.
-
Reassess commercial models in light of reimbursement shifts. Where extended monitoring codes exist, restructure pricing to capture recurring revenue through service bundles and remote-monitoring subscriptions.
-
Build selective partnerships rather than attempting end-to-end builds. For many firms, integrating proven analytics and cloud platforms via OEM/partner models is faster and less capital-intensive than in-house full-stack development.
-
Defend and extend margins through software and services. Hardware commoditization pressures margins; software, analytics and enterprise management tools offer higher margin expansion levers.
-
Use M&A tactically to fill capability gaps. Given the market’s moderate concentration, bolt-on acquisitions of analytics companies or channel specialists can shift competitive positioning meaningfully without necessitating mega-deals.
-
Strengthen procurement engagement. Buyers are increasingly requiring interoperability, enterprise ECG management and proven clinical outcomes; sales cycles that address CIO/CMIO concerns shorten procurement timelines.
How to use the full PW report for 2026 planning
This article is a strategic preview. The full Diagnostic ECG Market report contains the source tables, segmented forecasts, competitive scorecards and downloadable financial models that operational teams need to convert strategy into 2026 execution plans. Importantly, we intentionally withhold detailed subsegment tables in this preview; those granular split forecasts and regional/application breakouts are available in the report package and linked datasets for subscribers.
-
Immediate next steps for executives: request the model workbook to run your own price/adoption scenarios; use the competitor dossiers to validate partnership targets; and consult our regulatory navigator to align product submission timelines with commercial launches.
-
For investors: the report’s M&A and valuation section provides prioritization logic and benchmark multiples suited to 2026 market conditions.
-
For product teams: leverage our feature-pricing matrix and clinical-evidence checklist to prioritize development sprints that materially affect approval and procurement decisions.
Conclusion — a focused call to action for 2026
The Diagnostic ECG market is growing predictably at a multi-year CAGR of 7.5% and is entering a phase where regulatory clarity, reimbursement evolution and AI-enabled capabilities will separate winners from followers. PW Consulting’s full-market study converts those macro trends into executable decisions: regulatory sequencing, partnership targets, go-to-market adjustments and M&A priorities. If your organization must make strategic resource allocation, product prioritization or M&A decisions in 2026, the intelligence and models in our report are designed to reduce execution risk and accelerate time-to-value.
To access the full segment-level forecasts, downloadable model workbooks and actionable competitive dossiers referenced here, request PW Consulting’s Diagnostic Electrocardiograph (ECG) Market report and supporting data package.
For detailed analysis of this topic, please visit the official page: Diagnostic Electrocardiograph (ECG) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


