



PW Consulting: Automatic Platform Screen Door Market to Reach USD 2,025M by 2032 (8.5% CAGR)

Automatic Platform Screen Door Market: Strategic Outlook for 2026 Decision‑Makers
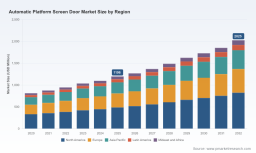
As urban transit systems scale and safety‑critical automation becomes a procurement prerequisite, the Automatic Platform Screen Door (APSD/PSD) market is entering a phase of accelerated consolidation and technology upgrade. PW Consulting’s latest market research frames this transition with a clear commercial lens: by the 2025 base year the global market reached roughly USD 1,196 million, and under a mid‑range adoption trajectory it is projected to approach USD 2,025 million by 2032 — a compound annual growth rate of approximately 8.5% over the 2026–2032 forecast window. For executives planning capital allocation, tender strategy, or product development in 2026, these macro dynamics are the starting line for a set of concrete, high‑impact decisions.
Automatic Platform Screen Door Market
Why this study matters for 2026 strategic choices
-
Timing of capital: transit agencies and operators face a narrow window to align infrastructure upgrades with fleet replacement cycles and safety regulation timelines. Our forecast quantifies the growth envelope and shows where capacity and supplier constraints will surface first — enabling procurement teams to set multi‑year tender calendars, staged rollouts, and contingency budgets.
Automatic Platform Screen Door Market -
Vendor selection and risk: higher automation levels elevate supplier counterparty risk. The market shows meaningful concentration among a handful of global and regional players; our competitive mapping and supplier scorecards transform that visibility into procurement-grade due diligence criteria.
Automatic Platform Screen Door Market -
Product roadmap and differentiation: suppliers and OEMs must prioritize SIL‑certified control systems, modular designs for retrofit, and digital remote diagnostics. The study outlines which technical capabilities will command price premiums and shorten project schedules in the 2026 procurement cycle.
-
Regulatory compliance and safety assurance: new standards and local codes are changing compliance baselines. The report decodes their operational and cost implications so teams can budget for certification, testing, and staged commissioning.
Market trajectory: what the top‑level numbers tell us
The headline market scale and growth rate provide a defensible frame for scenario planning. Between 2020 and the 2025 base year the market demonstrated steady expansion, reflecting increased urban rail investment and intensified focus on passenger safety. From 2026 onward, the 8.5% CAGR embedded in our central forecast reflects a mix of continued greenfield urbanisation, retrofit demand driven by safety regulation, and incremental spending on advanced control architectures and service contracts.
These high‑level figures indicate three practical planning conclusions for 2026:
-
Procurement teams should assume upward pressure on system prices and lead times, prompting earlier tender issuance and multi‑sourcing strategies.
-
OEMs and system integrators can justify investment into modular, certifiable control stacks and remote O&M capabilities, which unlock aftermarket annuities.
-
Investors and strategic buyers should expect a market with moderate concentration and differentiated capabilities — making targeted bolt‑on acquisitions an effective route to capture aftermarket revenue.
Competitive landscape — practical takeaways for 2026
Understanding supplier positioning is essential before issuing tenders or committing to strategic partnerships. Our competitive module synthesises company profiles, recent project footprints, technology differentiators, and procurement behaviour. Examples of the types of players covered include:
-
Established European manufacturers that offer modular barrier systems and train‑door synchronization solutions, with deep experience in metro deployments and standards compliance.
-
Specialist control‑systems vendors that provide safety‑critical SIL3/SIL4 certified controllers and software platforms — increasingly a selection criterion for transit authorities seeking predictable fail‑safe behaviour and digital interoperable interfaces.
-
Regional suppliers that combine cost‑competitive manufacturing with local regulatory know‑how and retrofit capabilities for high‑volume commuter networks.
To translate supplier intelligence into contracting advantage, the report provides a supplier scorecard template that weights technical certification, delivery track record, lifecycle service model, and local compliance experience — a pragmatic tool for 2026 sourcing teams to convert qualitative impressions into defensible supplier shortlists.
Regulatory and safety dynamics shaping 2026 decisions
Three regulatory vectors are reshaping how buyers and suppliers approach PSD projects:
-
New national and regional standards that codify functional and testing requirements for platform barrier systems, introducing compulsory certification milestones that must be budgeted into project timelines.
-
Safety‑critical control standards (SIL levels) that increasingly determine whether a solution is acceptable for heavy‑traffic metro networks; certified control systems are being fielded in pilot and live deployments and will be a de‑facto pre‑qualification in 2026 tenders.
-
Harmonisation of testing and commissioning protocols, which reduces vendor lock‑in risk but raises the bar for documentation and factory acceptance procedures.
For practical procurement governance in 2026, the report maps these regulatory milestones to typical project phases and quantifies the likely schedule impacts of certification cycles and local authority approvals.
Report contents — the operationally focused chapters
PW Consulting’s full study is designed to be operational from Day One of a sourcing cycle. Key deliverables inside the report include:
-
Market sizing and forecast model (transparent assumptions and scenario toggles for low/mid/high adoption), with downloadable model sheets to stress‑test procurement outcomes.
-
Competitive benchmarking and supplier deep‑dive dossiers, including capabilities matrices, recent contract examples, and technology roadmaps.
-
Procurement playbook — RFP language, pre‑qualification checklists, performance bond and warranty templates, and commission/checklist for factory acceptance tests (FAT) and site acceptance tests (SAT).
-
Risk matrix and mitigation pathways for schedule slippage, interface failures with rolling stock, and cybersecurity/remote‑access vulnerabilities.
-
Financial tools — a total cost of ownership (TCO) model, service economics for O&M outsourcing versus insourcing, and sensitivity analyses for key variables (lead time, unit price, service frequency).
-
Regulatory mapping — side‑by‑side comparison of applicable standards and the practical implications for design, testing and reporting activities.
To preserve the value of the research as an actionable intelligence product, we deliberately withhold granular regional and application split tables from this public preview; those segment‑level datasets and interactive dashboards are available only in the full report and model package.
Strategic playbook: five immediate actions for 2026
-
Lock procurement windows now: align tender timelines to rolling stock and signalling upgrade schedules to avoid unnecessary interface rework.
-
Prioritise SIL‑certified controllers in pre‑qualification criteria to avoid costly late‑stage substitutions.
-
Adopt modular procurement: specify modular barrier and gateway components to shorten installation windows and allow phased capital deployment.
-
Negotiate performance‑based service contracts that convert a portion of payment into availability and mean time to repair (MTTR) metrics, creating incentives for suppliers to invest in remote diagnostics.
-
Embed regulatory milestones in contracts with clear acceptance gates tied to certification deliverables to manage commissioning risk.
Market structure and consolidation signals
The market shows moderate concentration among the top players, with the leading suppliers controlling a meaningful share of industry revenues. This structure produces both risks and opportunities: on one hand, fewer suppliers can mean longer lead times and less price competition for large volumes; on the other hand, targeted partnerships or acquisitions can rapidly accelerate capability stacks for entrants and incumbents alike. The report’s M&A playbook helps buyers and investors prioritise targets based on technology gaps, regional access, and aftermarket service potential.
How to use this intelligence in 2026: a decision framework
PW Consulting recommends a three‑stage decision framework to turn market intelligence into executable strategy:
-
Assess current exposure: map installed base, retrofit backlog, and upcoming tenders to identify near‑term demand clusters.
-
Define the technical and commercial “must‑haves” that will be included in 2026 tenders (e.g., SIL level, modularity, digital service interfaces).
-
Run an accelerated supplier evaluation and pilot program to validate solution fit before large‑scale rollouts, using the FAT/SAT and acceptance templates included in our report.
Getting the full intelligence
This briefing highlights the strategic contours of the Automatic Platform Screen Door market and the practical implications for decisions you must take in 2026. It demonstrates the kind of operational depth the full study provides — including downloadable forecast models, supplier dossiers, tender and contract templates, and regional market diagnostics. To access the complete segment breakdowns, interactive dashboards, and the procurement playbook that will convert these insights into executable programmes, please consult the full PW Consulting report and model package.
For transit authorities, OEMs, system integrators, and infrastructure investors preparing for 2026, this study delivers the scenario tools, vendor intelligence, and contract artifacts required to move from strategic intent to operational success while managing schedule, cost and safety risk.
For detailed analysis of this topic, please visit the official page: Automatic Platform Screen Door Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


