



PW Consulting: Wood Furniture Market to Hit USD 449.74 Billion by 2032 at 4.95% CAGR

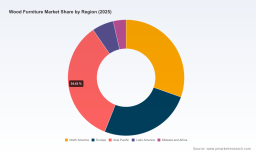
Wood Furniture Market 2026 — Strategic Preview for Executive Decision-Makers
PW Consulting’s latest Wood Furniture Market study (base year 2025, historical period 2020–2025, forecast 2026–2032) is a decision-grade brief built to inform capital allocation, sourcing strategy, portfolio design, and regulatory compliance planning for 2026 and beyond. The global market reached roughly USD 325.0 billion in 2025 and is projected to grow at a compound annual growth rate (CAGR) of approximately 4.95% through the forecast window — producing materially different opportunity maps in 2026 versus those executives relied on in 2020–2022. What follows is a high-fidelity preview of the study’s strategic implications; the full report contains the detailed subsegment tables, regional and application breakdowns, and primary-source appendices that most executives will want before committing to major moves.
Wood Furniture Market
Why this study matters to your 2026 playbook
-
Actionable growth pathways: The study translates headline growth into realistic tactical plays — channel expansions, SKU rationalization, and premiumization vectors that fit different cost and capability profiles.
Wood Furniture Market -
Sourcing & margin protection: With new trade measures and rising input-cost volatility, our models quantify the margin sensitivity to timber, panels, and offshore labor assumptions and identify hedging and near-shoring options.
Wood Furniture Market -
Regulatory readiness: The research includes compliance decision trees (notably for EUDR and recent U.S. tariff measures) enabling procurement and legal teams to map remediation timelines and supplier due-diligence requirements.
-
M&A and partnership screening: A fast-evaluation framework in the report helps corporates and PE sponsors size targets, stress-test synergies, and price add-ons in a market that is consolidated only in pockets.
Market trajectory and what it means for 2026 strategy
The wood furniture market is emerging from a phase of uneven recovery and structural realignment. After a multi-year recovery trajectory from the early 2020s, the industry reached an inflection in 2025. Our baseline forecast indicates continued expansion through 2032, with the market moving from the 2025 baseline toward materially higher absolute volumes and revenues by the end of the forecast window. For executives, the implication is clear: the growth environment supports disciplined investment, but returns will favor firms that manage raw-material exposure, regulatory complexity, and channel economics more tightly than in the last decade.
Practically, this means prioritizing three priorities in 2026: (1) resilient sourcing and inventory strategies to insulate cost of goods sold, (2) differentiated product-market fit to capture premiumization in urban and sustainability-conscious segments, and (3) operational flexibility to shift between direct-to-consumer, retail, and contract channels as demand patterns evolve.
Key macro and regulatory dynamics to plan around
-
Trade barriers and tariffs: Recent U.S. measures have introduced step-changes in import duties for timber, upholstered wooden products, and kitchen cabinets that materially alter landed cost equations for import-heavy manufacturers and retailers. Executives must re-price and re-source to preserve margins or accept compression in lower-value SKUs.
-
Anti-dumping and countervailing duties: Elevated duties on certain Canadian lumber imports have pushed North American lumber cost curves upward — a structural cost headwind for many wood-intensive SKUs.
-
EU due-diligence (EUDR): The European requirement for full traceability and due diligence on timber products materially increases supplier documentation burdens and lengthens procurement lead times for pan-European distribution.
-
Raw-material fundamentals: U.S. softwood production levels remain a critical supply indicator; availability and species mix will determine who can scale solid-wood offerings economically in the near term.
Competitive landscape — who matters and why
The industry remains a mosaic of mass-market manufacturers, office- and contract-specialists, and artisan/high-end producers. Market concentration is moderate; consolidation is visible in some channels but the overall landscape rewards nimble, brand-driven strategies as much as scale.
-
Ashley Furniture Industries — A mass-market incumbent with integrated manufacturing and broad retail distribution. Ashley’s scale in case goods and upholstered assortments makes it a bellwether for pricing dynamics in the mainstream residential channel.
-
HNI Corporation — Strong in office and contract furnishings, with depth in engineered wood components. HNI’s positioning is critical for firms seeking to cross-sell into commercial interiors as office refit cycles normalize.
-
La-Z-Boy Incorporated — Known for upholstered and complementary wood pieces, La-Z-Boy illustrates how brand equity can sustain premium pricing even as raw-material volatility rises.
-
Haworth Inc. — Designer and supplier to office markets, Haworth exemplifies how design-led strategies and service overlays (space planning, long-term contracts) defend margins in contract segments.
-
Vermont Woods Studios , Furnirem , Arista Wood , Whittier Wood , and Stickley — These smaller and specialist brands demonstrate the fertile premium and sustainability-led niches: handcrafted solid-wood, reclaimed wood, and regionally sourced hardwoods remain attractive to consumers willing to pay for provenance and craftsmanship.
Recent developments underscore these strategic dynamics: in March 2026 Furnirem announced a product-line expansion emphasizing adaptable urban formats and storage-integrated features, signaling demand for multifunctional, space-efficient design in dense housing markets. Earlier, Urban Barnwood Furniture’s rebranding to Arista Wood (February 2026) illustrates how provenance and reclaimed-material narratives are being leveraged to expand addressable markets beyond a narrow artisanal cohort. Collectively these moves indicate manufacturers are layering new offers — not just new SKUs — to capture value across price tiers.
What the full PW Consulting report delivers (practical, usable components)
-
Validated market sizing and forecasting methodology — transparent assumptions and sensitivity bands for commodity prices, tariffs, and demand shocks.
-
Scenario planning modules — three actionable revenue/profit scenarios by 2032 under differing trade and sustainability-policy regimes.
-
Supply-chain risk heatmaps — supplier concentration indices, transit-time stress points, and mitigation playbooks for near-shoring, dual-sourcing, and inventory strategies.
-
Pricing and margin optimization tools — SKU-level levers, bundling strategies, and real-world elasticity proxies to inform price tests and promotions.
-
Regulatory compliance checklists — practical steps for EUDR alignment, supplier traceability clauses, and audit-ready documentation templates.
-
M&A and partnership screening matrices — target archetypes, integration cost ranges, and accretion/dilution heuristics tailored to the furniture value chain.
-
Commercial playbooks — go-to-market strategies for direct-to-consumer, omnichannel retail, contract/interiors, and marketplace models with sample KPI dashboards.
How executives should convert insight into action in 2026
-
Immediate (0–90 days): Run a supplier traceability audit prioritized by SKU profitability and regulatory exposure; update landed-cost models to reflect recent tariff escalations; pause low-margin, import-dependent launches pending re-sourcing outcomes.
-
Near term (3–9 months): Execute pilot near-shoring or strategic partnership agreements, test premium reclaimed or sustainably sourced collections in select channels, and deploy a price-realignment for SKUs with the highest timber intensity.
-
Medium term (9–18 months): Pursue bolt-on acquisitions to secure critical timber or panel capacity where scarcity risks are highest; standardize supplier due-diligence and EUDR-compliant documentation across the sourcing network.
-
Strategic (18–36 months): Rebalance portfolio toward higher-margin, differentiated propositions — design-led, sustainability-verified, and service-enhanced offerings — while maintaining flexible manufacturing capacity to respond to tariff or demand shocks.
Why the preview conceals subsegment tables — and where to get them
This article intentionally previews the study’s strategic implications while withholding the granular regional, application, and type-level tables that many organizations require to finalize budgets and acquisition bids. That granular intelligence — including the exhaustive breakdown of demand by channel, region, and product type, supplier maps, and SKU-level margin matrices — is included in the full PW Consulting report and companion data pack. We designed the preview to demonstrate methodology, highlight risks and near-term plays, and to give executives a clear sense of the research’s immediate utility while encouraging direct access to the proprietary datasets needed for transaction-level decisions.
Final note — what to prioritize when you read the full report
-
Start with the sensitivity matrices in the forecast chapter — they show which assumptions move enterprise value the most under plausible 2026 scenarios.
-
Cross-check supplier documentation against the compliance checklist before negotiating new contracts in EU or U.S. channels.
-
Use the M&A screening matrix to triage targets into “capacity,” “brand,” or “capability” plays — each requires a different valuation lens in the current environment.
-
Deploy the pricing optimization framework in your next category review to capture margin uplift without sacrificing velocity.
PW Consulting’s full Wood Furniture Market report is structured to move executives from insight to execution within weeks, not months. For license options, dataset licensing, and tailored advisory engagements that embed our models into your capital and product planning cycles for 2026, consult the report landing page — the detailed subsegment tables and supplier-level appendices you will need to act decisively are available there.
For detailed analysis of this topic, please visit the official page: Wood Furniture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


