



PW Consulting: Prothioconazole Market to Hit USD 1,824.98 Million by 2032 (6.4% CAGR)

Prothioconazole Market — Strategic Outlook for 2026 Decision-Makers
Executive summary
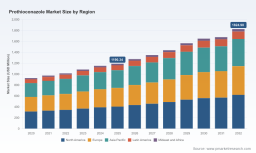
The global prothioconazole market has shifted from a niche fungicide segment into a strategically salient element of crop-protection portfolios. After a steady rise through the early 2020s, market value reached approximately USD 1.19 billion (Million USD) in our base year 2025 and, under our central case, is projected to grow at a compound annual growth rate (CAGR) of 6.4% across 2026–2032 to approach roughly USD 1.82 billion by 2032. Concentration is meaningful — the three-largest players account for about 60% of market share and the top five around 70% — creating structural advantages and competitive pressure simultaneously.
Prothioconazole Market
For corporate leaders preparing budgets, making portfolio decisions, or evaluating M&A and supply-chain strategies for 2026, the intelligence and scenario modelling in this research provide high-conviction signals — from near-term regulatory inflection points to multi-year demand trajectories. This article distills the strategic implications while preserving the granular modelling and segment-level outputs for subscribers who require the full analytical set.
Prothioconazole Market
What the report delivers — a practical toolkit for 2026 planning
- Transparent market-size and trajectory modelling (historical 2020–2025, base year 2025, and forecast 2026–2032) with three scenario paths (baseline, downside regulatory shock, and upside adoption acceleration).
- Regulatory risk heatmap and decision triggers tied to European MRL developments and peer-review timelines — actionable for regulatory affairs and market access teams.
- Supply‑chain resilience mapping and procurement playbooks, including supplier concentration stress tests and mitigation roadmaps for technical concentrate shortages.
- Commercial go-to-market playbooks for formulation owners, generic suppliers, and crop‑specialist distributors — covering pricing, bundling, and channel segmentation strategies.
- Competitor benchmarking and capability matrices that evaluate technical capacity, formulation breadth, and commercial reach for the industry’s leading firms.
- M&A and partnership screening framework with private-market valuation scenarios keyed to prothioconazole-derived cashflows and synergies.
- Farmer-economics assessments and ROI simulations for major crop use-cases to support field trials and seed-customer commercial pilots.
Why this matters for corporate strategy in 2026
Several intersecting forces make prothioconazole a high-priority topic for 2026 strategic planning:
Prothioconazole Market
- Predictable, mid-single-digit market expansion. A CAGR of 6.4% implies a meaningful uplift in absolute market size over a seven-year horizon; this transforms prothioconazole from a steady revenue contributor into a line that can justify targeted investment in formulation innovation, registered label expansion, or dedicated supply arrangements.
- Regulatory dynamics are a gating factor. Recent activity around maximum residue limits (MRLs) and EFSA peer review processes has increased both the upside (new label opportunities) and downside (restrictions or additional data requirements) risks that must be managed through regulatory strategy rather than ad hoc responses.
- Supplier and commercial consolidation. The market’s concentration creates leverage for larger players but also produces supply vulnerabilities for smaller formulators. Long-term contracts, strategic partnerships and backward integration of technical supply chains are now primary levers for securing stable access.
Competitive landscape — concise profiles and tactical implications
Our competitive analysis highlights a small group of influential incumbents and several active regional players. Key positions include:
- Bayer CropScience (Germany) — Core developer and large-scale global producer; positions prothioconazole as foundational DMI chemistry for cereals and soybean disease control under established brands. Implication: Bayer’s ownership of early and broad registrations limits fast-follower upside in certain high-margin use-cases, and any competitive entry must target differentiated formulation or niche crop claims.
- ADAMA Agricultural Solutions (Israel) — Major technical producer and global formulator with multi-purpose plants and a demonstrated ability to supply in-house active ingredient to support global pipelines. Implication: ADAMA’s vertical integration is a competitive hedge against technical shortages; partnerships with regional distributors should focus on agility and tailored labels.
- Albaugh LLC (United States) — Focused provider of high-concentration formulations marketed for turf and ornamentals; leverages low-use-rate positioning. Implication: Premium niche channels exist for differentiated, low-rate products even when large‑acre applications drive volume.
- Sipcam Oxon SpA (Italy) — Technical supplier and formulator active in cereals, pome fruits and cucurbits; recent MRL modification filings indicate an offensive regulatory play. Implication: Regulatory petitions can unlock new crop applications — monitoring and timely response to MRL developments is critical for commercial planners.
- Corteva Agriscience (United States) — Active producer of technical concentrates used in global formulations. Implication: Large agrochem players remain potential partners or competitors in supply and co-development; strategic decisions on whom to partner with should be informed by capacity, geography and commercial scope.
Recent strategic moves underscore the market’s momentum: a June 2025 partnership between Sumitomo Chemical and BASF to co-develop prothioconazole-based products across Asia-Pacific, a June 2025 long-term supply agreement between Syngenta and FMC, and regulatory filings and EFSA activity from mid‑2025 through early 2026. These events materially change supply calculus and shorten the window for first-mover advantage in certain geographies.
Regulatory snapshot and near-term decision triggers
Regulation is both opportunity and risk. Key items tracked in our regulatory module and that should trigger corporate actions in 2026 include:
- MRL modifications: recent applications to raise MRLs for specific fruit and cereal uses have been filed and partially adopted by EFSA; these submissions can unlock commercial expansion if approved but require pre-planned residue data strategies.
- Peer-review outcomes: EFSA’s pesticide peer-review committee discussions (notably in January 2026) on toxicology profiles and metabolites can lead to label changes or new data requirements; companies should have contingency compliance plans and a prioritized data generation roadmap.
- Regional registration timelines: staggered review cycles across jurisdictions mean that a synchronized global launch is rarely feasible; instead, use a prioritized, resource-efficient registration sequence tied to commercial ROI per market.
Actionable recommendations for 2026
For executives allocating capital and people in 2026, we recommend a three-tiered approach:
- Immediate (0–3 months) — Lock down technical supply through binding agreements or optioned capacity; initiate regulatory data-gap assessments in priority markets; run a price-sensitivity test with key distributors to validate value capture assumptions.
- Near term (3–12 months) — Execute one or two targeted registrations that maximize incremental ROI (our full report contains crop-by-crop ROI analytics to select these); negotiate co-development or licencing terms where internal registration capacity is constrained; pilot differentiated formulations in premium channels (e.g., turf/ornamental or seed treatment co-formulates).
- Medium term (12–36 months) — Pursue scale options: M&A of regional formulators to consolidate route-to-market, invest in low-dose formulation R&D to broaden application economics, and implement integrated resistance-management programs to sustain product efficacy and label life.
Why our modelling matters to your boardroom
Translating chemical-level growth into enterprise decisions requires more than top-line projections. The strategic value of this research is threefold:
- It converts a market CAGR and macro trajectory into discrete, executable plays (registration sequencing, procurement hedges, channel economics) calibrated to company scale and appetite for risk.
- It stitches regulatory pathways to commercial outcomes: by linking MRL outcomes and peer-review signals to revenue and margin scenarios, the model surfaces where to invest in data versus where to limit exposure.
- It frames partnership and M&A choices against an objective concentration and capability map — enabling your M&A team to prioritize targets that either shore up supply or expand addressable use-cases.
Access and next steps
This article is a strategic preview designed to orient executives and senior managers. The full Prothioconazole Market report contains the detailed segment tables, country-level forecasts, elasticity matrices, registration-cost estimates, and M&A scorecards that underpin the recommendations above. To obtain the complete dataset, scenario models in spreadsheet form, and a tailored briefing with our senior industry analysts, please visit the report landing page or contact the PW Consulting enterprise intelligence desk.
In an environment where regulation, supply arrangements and concentrated incumbency jointly shape outcomes, 2026 is the year to convert insight into defensible action. Use the intelligence in this research to align boards, prioritize investments, and crystallize partnership strategies that capture the growth implicit in an expanding prothioconazole market.
For detailed analysis of this topic, please visit the official page: Prothioconazole Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


