



PW Consulting: Wellington Boots Market Set for 4.8% CAGR

Wellington Boots Market — Strategic Preview for 2026 Decision-Makers
As Wellington Boots reassert their role across agri-business, industrial applications and a resurgent outdoor culture, corporate leaders face high-stakes choices in sourcing, product architecture and go-to-market design. PW Consulting’s forthcoming Wellington Boots Market study synthesizes market sizing, trade shocks, material transitions and competitive strategy into an operationally-driven playbook tailored for decisions you must make in 2026. Below I summarize the strategic implications, the kinds of prescriptive analysis the full report delivers, and the immediate actions we recommend — while deliberately withholding the granular sub‑segment tables that make the full intelligence actionable on the ground.
Wellington Boots Market
Macro snapshot: why 2026 is a pivot year
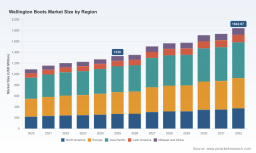
The global Wellington boots market reached approximately USD 1.33 billion in our base year and is projected to grow at a steady mid-single-digit CAGR (4.8%) through the forecast horizon. That trajectory reflects two structural realities that should shape 2026 planning: a resilient underlying demand base across work and leisure applications, and accelerating structural change driven by materials substitution, trade policy, and cost inflation in the upstream supply chain.
Wellington Boots Market
For leadership teams, that combination means opportunity, but also compressed windows for defensive moves. Momentum is sufficient to support investment in product and channel development — provided that investments are precisely targeted against cost and trade risk scenarios that our models quantify in the full study.
Wellington Boots Market
What the PW Consulting study gives you (practical, decision-ready deliverables)
- Transparent market framework and validated sizing: A consistent market definition and reconciliation of historical sales (2020–2025) with a scenario-based forecast (2026–2032), including downside and upside pathways tied to raw material and tariff shocks.
- Cost-to-serve and price elasticity models: SKU-level cost build-ups, margin curves and demand response matrices that let commercial teams test price increases and promotional trade-offs without eroding brand equity.
- Supply‑chain stress-testing: Trade-flow maps, supplier concentration indices, and near-term disruption scenarios (tariff escalations, freight surges, factory shutdowns) with quantified P&L impacts and recommended hedging or insourcing options.
- Material transition playbook: Comparative lifecycle and cost models for rubber, synthetic alternatives and emerging sustainable substrates, plus supplier qualification checklists and pilot-roadmap templates for design and certification.
- Channel and route-to-market playbooks: Segmented distribution tactics for retail, professional (fishing, agriculture, industrial), and direct-to-consumer channels, including assortment rationalization and omnichannel fulfilment design.
- Competitive scorecards and watchlist: Qualitative and quantitative profiles of incumbent and challenger brands, plus an M&A/investment target shortlist with synergy and integration heat maps.
- Regulatory & tariff playbook: Scenario templates to model duty pass-through, re-routing supply chains, and build-versus-buy options for 2026 compliance pressures.
- Executive decision pack: One-page investment cases, 18-month operational plans, and risk-adjusted ROI for capital deployment, facility moves, or strategic alliances.
Competitive dynamics — what incumbents and challengers are doing
The competitive set is diverse: heritage artisanal brands, industrial-focused suppliers, outdoor-lifestyle players, and lower‑cost mass-market manufacturers each pursue different routes to growth. Brands such as Le Chameau and Aigle leverage craft, premium positioning and selective retail partnerships to protect margin. Technical brands like Grundéns, Xtratuf and Dunlop stress performance and chemical/thermal resistance for professional users, while consumer-focused firms such as Bogs and Rockland emphasize waterproofing, comfort and price accessibility. Commercial suppliers like Rubbermaid and Tingley position themselves firmly within facility, safety and institutional channels.
Recent product and channel moves underline two themes. First, premiumization and collaboration strategies remain a viable way to protect ASPs (Le Chameau’s retail collaborations are a case in point). Second, professional-grade innovation continues to be a live battleground: recent product launches tested in demanding real-world conditions (e.g., fishing fleets, commercial fisheries and industrial sites) are being used as credibility levers in core markets.
Trade, tariffs and cost pressure: tactical levers for 2026
Trade policy developments in 2025–2026 are reshaping sourcing calculus. Targeted ad valorem duties and revised HTS classifications have created material incentives to revisit production footprints and routing strategies. Simultaneously, upstream cost escalation — raw materials and freight — forced many manufacturers to increase list prices materially in 2025 to preserve margins.
For 2026 planning, the critical question is not whether to act but how quickly and in what sequence. Our report models the P&L sensitivity to tariffs and suggests three pragmatic responses: (1) immediate short-run margin protection via selective price-pass and promotional reshaping; (2) mid-term tactical re-routing and nearshoring pilots for high-margin product lines; and (3) longer-term supplier diversification and vertical integration where capital payback is compelling.
Consumer & product trends to capitalize on
Across Europe and North America, product development has bifurcated into two dominant themes: premium craftsmanship and sustainability-led innovation. Eco-conscious materials and circular design features are no longer niche; they now shape product pipelines and retailer assortment decisions. At the same time, functional performance — slip resistance, chemical protection, thermal insulation — remains non-negotiable in professional segments, creating a premium-sustainable-performance sweet spot for brands that can execute.
In practice, this means R&D and sourcing teams should prioritize materials that deliver comparable performance to legacy rubber while improving environmental credentials, and operations teams must verify cost parity scenarios against full lifecycle impacts — a capability our material transition module operationalizes.
Strategic playbook for 2026 — prioritized moves
- Immediate (0–6 months): Run tariff-impact P&L simulations on your top 20 SKUs; implement targeted price restructures and adjust promotional cadence to protect gross margins while maintaining volume in critical channels.
- Near term (6–18 months): Launch two supply‑chain pilots: a nearshoring proof-of-concept for premium ranges, and a dual‑sourcing plan for mass-market SKUs to mitigate single-origin tariff exposure.
- Product & R&D (12–24 months): Operationalize the sustainable-materials pipeline with supplier qualification and a 12-month lab-to-retail pilot; align marketing messaging for differentiation in retail assortments.
- M&A and commercial partnerships (12–36 months): Evaluate bolt-on acquisitions to secure proprietary compounds or channel access; pursue selective retail partnerships and co-branded product lines to accelerate margin-accretive growth.
- Risk & compliance: Institutionalize tariff-watching frameworks and duty-optimization workflows to maintain agility as HTS classifications and enforcement evolve.
Why the full PW Consulting study is materially different from public summaries
Public commentary highlights high-level trends. Our report delivers layered decision support: deterministic and probabilistic forecast scenarios, SKU-level margin impact matrices, supplier scorecards with audit-ready KPIs, and ready-to-follow implementation templates for procurement, product and commercial teams. Crucially, we do not simply report the data: we translate it into prioritized, measurable actions with quantified ROI and timelines — the exact inputs your CFO and COO need to approve capital and operating plans for 2026.
To respect the “trailer” principle, I’ve deliberately excluded the granular regional, material and application breakdowns from this preview. Those segment-level matrices, along with interactive dashboards and downloadable financial models that allow you to stress-test price, tariff and demand assumptions, are available in the full report and are the core of the practical value we deliver.
How to use this intelligence for board-level conversations
Bring the following three items to your 2026 planning table, each supported by the full PW Consulting dataset:
- Risk-adjusted sourcing plan: a schedule of tactical, mid and long-term moves that balances cost, lead-time and trade exposure.
- Product portfolio investment map: prioritized SKUs for premium sustainable upgrades vs. cost-led optimization for mass channels.
- Commercial action agenda: channel-specific pricing and promotional templates aligned to the new cost base and consumer acceptance tests.
Executing against these items will transform uncertainty into controlled optionality and give leadership teams defensible, measurable pathways to protect margin while participating in the market’s growth.
Next steps
If your team is preparing 2026 budgets, supply-chain reconfiguration, or an M&A mandate in this category, PW Consulting’s Wellington Boots Market study is designed as a working document — not a passive read. The full study contains the data tables, scenario models and executable playbooks summarized here. Contact PW Consulting to access the complete report, interactive dashboards and a tailored briefing that maps the analysis directly to your portfolio and operating model.
In short: the market fundamentals support continued investment, but the 2026 decision window rewards precision. Use strategy, not speed alone, to convert market growth into sustainable profitable expansion.
For detailed analysis of this topic, please visit the official page: Wellington Boots Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


