



PW Consulting: Flooring Underlayment Market Poised for 4.8% CAGR (2026–2032)

Flooring Underlayment Market — 2026 Strategic Brief
Executive snapshot
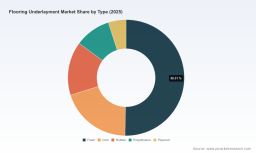
As PW Consulting’s lead industry analyst, I present a focused, decision-oriented preview of our full Flooring Underlayment Market study to guide executive planning for 2026. The market has expanded steadily from the start of the decade and, driven by resilient end‑market demand, sustainability trends, and technical innovation in acoustic and moisture-management solutions, continues on a mid-single-digit growth trajectory. Using 2025 as our base year and projecting through 2032, the study finds a compound annual growth rate (CAGR) of 4.8%, with total global revenues moving from roughly USD 1,529.7 million in 2020 to approximately USD 1,935.6 million in 2025 and a forecast approaching USD 2,698.1 million by 2032 (USD Million basis).
Flooring Underlayment Market
Why this matters for 2026 corporate decisions
-
Procurement and raw‑material hedging: With polyethylene‑foam still the dominant formulation and crude‑linked feedstocks governing cost swings, procurement teams need forward-looking exposure analysis and multi‑sourcing strategies to avoid margin erosion.
Flooring Underlayment Market -
Product roadmaps and warranties: Resilient flooring OEMs and underlayment suppliers must balance acoustic/moisture performance against strict installation constraints (notably maximum thickness limits that affect warranty compliance). Design choices made in 2026 will influence warranty acceptance and aftermarket claims for years.
Flooring Underlayment Market -
Channel and installer economics: Labor and installation complexity—especially for moisture mitigation and precision floating systems—are shifting value to installers with higher skill sets. Manufacturers must crystallize go‑to‑market and installer incentive models now to win share.
-
M&A and capacity plays: Moderate concentration at the top of the market creates attractive consolidation opportunities. Our market concentration analysis shows top‑three players capture roughly 42.5% of global revenues, while the top five account for about 58.2%—a structure that creates pockets of scale advantage but leaves niches for focused specialists.
Market trajectory and core macro drivers
The market’s historical progression (2020–2025) to a 2025 base of about USD 1.94 billion underscores steady replacement cycles in residential and commercial flooring, growth in LVP/LVT adoption, and rising specification demand for acoustic comfort in multi‑family and mixed‑use developments. Looking ahead (2026–2032), our forecast shows continued expansion to roughly USD 2.70 billion by 2032 on a 4.8% CAGR, driven by three converging forces:
-
Product substitution toward high‑performance, thinner underlayments that meet warranty and acoustic standards for new generation locking floors.
-
Sustainability and circularity: demand for recycled rubber, cork blends and post‑consumer content is materializing into commercial specifications, supporting premium positioning and margin differentiation.
-
Geographic demand mix: market growth is uneven but persistent across regions as urbanization, remodeling cycles, and commercial construction rebound in key corridors.
Supply‑side dynamics and risk map
Our dynamics chapter synthesizes the factors that will drive supply‑chain choices in 2026:
-
Raw‑material exposure: Polyethylene foam production remains sensitive to crude oil price cycles and refinery capacity. Price volatility is the primary short‑term risk to foam‑dominant producers’ margins.
-
Tariffs and transport surcharges: Rising import costs for foam, rubber and cork components are altering the landed cost calculus. Manufacturers with regional manufacturing or bonded inventory strategies are positioned to capture near‑term share.
-
Post‑disruption normalization: Recycled rubber and natural cork supplies have stabilized since 2023, enabling reinvestment in capacity. However, quality and grading requirements for high‑performance underlayments mean entrants must demonstrate consistent material specs.
-
Regulatory and warranty constraints: Many resilient flooring manufacturers cap underlayment thickness (notably to preserve locking‑joint integrity). This technical boundary constrains product design and creates a premium for high‑performance thin systems.
-
Labor and installation complexity: New moisture mitigation protocols and installer‑focused innovations increase labor intensity. Project economics now demand clearer installer training, bundled warranties, and performance verification tools.
Competitive landscape — what the market leaders and innovators are doing
The market exhibits a mix of established scale players, private‑label specialists, and regional innovators. Key profiles and tactical moves to watch include:
-
MP Global Products (Norfolk, NE): A leader in acoustic fiber underlayments, emphasizing noise reduction, moisture protection and recycled inputs. Their recent promotional push spotlights eco‑credentials alongside performance—an approach that helps defend premium positioning in retrofit and new‑build segments.
-
Leggett & Platt Flooring Products (USA): The largest U.S. manufacturer across cushion and hard‑surface underlayments, with deep channel relationships and a broad formulation slate. Their scale gives them leverage on feedstock procurement and private‑label contracts.
-
Pak‑Lite, Inc. (USA): The dominant private‑label supplier for floating floor underlayments in North America, known for customized acoustic and IIC/STC performance ratings—a specialist model that appeals to big‑box and installer networks seeking private‑label differentiation.
-
Wise Flooring Products and FloorMuffler (USA): Domestic manufacturers focused on recyclable, American‑made underlayments and a portfolio approach spanning foam, rubber and recycled fiber—positions that address both sustainability mandates and local sourcing preferences.
-
Cyg Tefa (Vietnam) and Hubei Xiangyuan (China): Regional exporters supplying advanced IXPE/XPE and multi‑type underlayments for fast‑growing LVP and laminate supply chains. Their presence matters for cost‑sensitive OEMs and distributors seeking competitive cross‑border sourcing.
-
RSP Industries and other specialist acoustic providers: Niche players that capture specification work in high‑end commercial and hospitality projects.
Notable recent developments indicate product evolution and premiumization: Floordi’s May 2026 launch of a premium acoustic underlayment (F‑Shield) targets improved stability and moisture protection for modern floor systems; MP Global’s 2026 promotions stress recycled content and acoustic performance; and Cyg Tefa’s 2025‑2026 showcases have increased interest in IXPE solutions. Each move signals intensifying competition on performance, sustainability and installer friendliness rather than just price.
Strategic playbook for 2026 — six actions for executives
-
Revisit raw‑material strategy: Build multi‑tier supply agreements for polymer feedstocks and establish formula alternatives (e.g., recycled blends) to limit single‑supply exposure.
-
Prioritize thin, high‑performance development: Invest in R&D for lower‑thickness products that meet warranty constraints while delivering acoustic and moisture benefits.
-
Lock in installer economics: Develop certified installer programs, packaged warranties and performance verification tools to reduce field failures and speed adoption.
-
Regionalize footprint: Evaluate near‑market production or bonded inventory for high‑volume corridors to neutralize transport surcharges and tariff risks.
-
Use M&A to fill capability gaps: Target acquisitions that provide formulation IP (acoustic or moisture), private‑label scale, or regional distribution networks rather than chasing top‑line growth alone.
-
Make sustainability a commercial advantage: Translate recycled content and end‑of‑life narratives into tangible spec points for architects, developers and procurement teams.
What the full PW Consulting report delivers (practical, executable content)
Our full study—built on a 2025 base, five years of historical data (2020–2025), and a 2026–2032 forecast—contains the operational intelligence needed to act in 2026:
-
Market sizing and outlook by year (USD Million), with sensitivity scenarios tied to raw‑material price swings and tariff paths.
-
Segment taxonomy and supplier scorecards across product types, applications and regions—scored on procurement risk, technical performance and commercial reach (note: detailed segment tables and vendor ranks are available in the full report).
-
TPR‑style playbooks for procurement, product development and channel economics, with executable checklists and vendor negotiation frameworks.
-
Value‑chain cost models showing landed cost drivers (materials, logistics, tariffs, labor) and margin simulations under alternate sourcing scenarios.
-
Competitive heat‑maps and M&A screening frameworks with target profiles tailored to scale, technical IP and geographic footprint.
-
Regulatory and warranty compliance appendix—key installation tolerances, specification language and recommended quality‑assurance protocols for OEMs and installers.
Conclusion and next step
The flooring underlayment market in 2026 is a space of pragmatic innovation: product performance and installer economics are now as important as unit price. For executives planning capex, sourcing, or M&A this year, the strategic choices you make—about material exposure, product thin‑filing, regional footprint, and installer enablement—will determine who captures upside as the market expands toward our 2032 forecast.
PW Consulting’s full report contains the granular segment tables, supplier matrices, and scenario models that operationalize these recommendations. To access the detailed data and proprietary vendor scoring that underpin the strategic playbook, please visit our report page and download the comprehensive analysis.
For detailed analysis of this topic, please visit the official page: Flooring Underlayment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


