



PW Consulting: Railcar Leasing Market to Reach USD 247.5M by 2032, 5.5% CAGR (2026–2032)

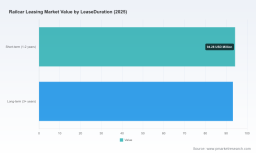
Railcar Leasing Market 2026: Strategic Imperatives and What PW Consulting’s Study Unlocks
The railcar leasing market is entering a phase of strategic consolidation and reconfiguration. Our new Railcar Leasing Market study, anchored on a 2025 base year and projecting through 2032, quantifies a steady recovery and expansion: the global market rose from an estimated USD 158.0 Million in 2020 to USD 187.5 Million in 2025, and under our base assumptions is forecast to reach approximately USD 247.5 Million by 2032 — representing a compound annual growth rate (CAGR) of roughly 5.5% over the forecast window. These headline metrics frame a market that is large enough to attract private capital and strategic entrants, yet fragmented enough to reward differentiated operating models and disciplined capital allocation.
Railcar Leasing Market
Why this report matters to 2026 decision-makers
-
Capital allocation under new regulatory constraints: With fresh safety and content-sourcing rules taking effect in late-2025 and tightening further in 2028, lessors, manufacturers and financiers must reassess procurement policies and supplier panels to avoid stranded orders and cost overruns.
Railcar Leasing Market -
M&A and portfolio plays: The market’s moderate concentration (our concentration metrics show the top three players account for roughly 28.5% of industry volumes and the top five for about 35.0%) signals room for bolt-on transactions and strategic fleet consolidation — but only if acquirers understand lifecycle economics and lease-duration mix across geographies.
Railcar Leasing Market -
Operational resilience and lifecycle economics: Operators are being asked to do more with existing fleets via refurbishment, retrofits for new regulatory standards, and digital asset management. Our study shows where investments in maintenance and telematics yield the highest returns versus ordering new-builds.
-
New market entrants and integrated models: Recent strategic moves demonstrate a pivot toward integrated offerings that combine manufacturing, leasing, financing and lifecycle services — a model that changes unit economics and customer retention dynamics.
What the PW Consulting report gives you — practical, decision-ready deliverables
-
Verified market sizing and trend matrices: Year-by-year market sizing from 2020–2025, and a detailed forecast to 2032 under alternative macro and policy scenarios — enabling robust revenue planning and sensitivity testing for board-level decisions.
-
Scenario playbooks: Three forward-looking scenarios (base, supply-constrained, and accelerated-decarbonization) translated into fleet demand, ordering timing, and capex/opex implications to 2032.
-
Lease-duration economics: Actionable templates and models comparing short-term versus long-term lease economics, residual-value risk, and break-even points by vehicle class and region (note: the full segmentation tables and underlying unit values are available in the full report).
-
Regulatory compliance matrix: A practical roadmap for aligning procurement, manufacturing and certification activities with recent Freight Car Safety Standards and evolving transparency requirements, including compliance timelines and likely cost vectors.
-
Fleet optimization toolkit: A plug-and-play model for optimizing fleet mix, utilization rates, and maintenance schedules — calibrated to real-world utilization and failure-rate inputs collected from operators and lessors.
-
M&A and partnership playbook: Due diligence checklists, valuation adjusments for regulatory risk, integration templates, and a prioritized list of capability targets for buyers seeking scale or vertical integration.
-
Commercial contracting templates: Draft lease and service-level agreement provisions reflecting updated transparency and competition expectations in mature markets, with negotiation guidance by counterparty type.
-
Vendor and supplier risk matrix: A practical supplier-scorecard structure that maps content-sourcing risk from geopolitical and state-owned sources to contractual levers and dual-sourcing requirements.
Competitive landscape — who to watch and strategic implications
-
Large-scale lessors with scale and service depth are recalibrating growth strategies. For example, GATX’s recent North American fleet acquisition materially increases its operational scale and alters leasing supply dynamics; the transaction underscores the strategic value of scale in absorbing demand volatility and negotiating lifecycle service contracts.
-
Integrated players with manufacturing linkages are creating differentiated value propositions. A strategic alliance and equity stake recently formed to create India’s first global railcar leasing platform demonstrates how combining manufacturing, financing and lifecycle management can accelerate market entry and reduce time-to-revenue for new fleets.
-
European full-service operators are strengthening multimodal and digital capabilities. Providers focused on locomotives, electric traction and tailored service packages are positioning to capture opportunities driven by modal shift and rail electrification agendas across continental markets.
-
Independent and pan-regional lessors remain important buyers of modern freight wagons and intermodal equipment, capitalizing on niche power by offering flexible contracts and local maintenance networks; for strategic investors these companies can be attractive targets for bolt-on tech and sustainability upgrades.
Regulatory dynamics that will shape capital plans in 2026
-
Content sourcing limits and manufacturing compliance: New U.S. Freight Car Safety Standards impose content-origin limits for freight cars manufactured after December 19, 2025, with stricter thresholds slated for 2028. Practically, this creates immediate procurement challenges for lessors and OEMs that rely on global supply chains and increases the value of diversified or local supplier pools.
-
Transparency and market remedies: Regulatory reviews in key markets continue to prioritize transparency in leasing terms and competition remedies. Lessors and rolling stock leasing market participants need contemporaneous governance and reporting standards to avoid remediation actions and reputational costs.
-
Implication for financing and insurance: Regulatory uncertainty elevates residual-value risk and complicates asset-backed financing structures. Lenders will require scenario testing and covenant flexibility; insurers will adjust premiums for content-origin and compliance cascade risks.
Decision playbook — recommended moves for 2026
-
For lessors: accelerate investments in asset digitization and predictive maintenance to lift utilization and reduce lifecycle costs; selectively pursue M&A or portfolio acquisitions that provide geographic diversification and scale efficiencies.
-
For manufacturers: reconfigure supply chains to meet content-origin rules, prioritize modular designs that simplify compliance-driven retrofits, and offer bundled leasing-manufacturing-finance options to capture more of the value chain.
-
For financiers and investors: stress-test portfolios against regulatory tightening and supply-chain shocks; prefer transactions with embedded service revenues and transparent end-of-lease disposition channels.
-
For rail operators and shippers: renegotiate lease terms to incorporate flexibility for regulatory-driven retrofits and adopt performance-linked payments to align incentives for uptime and emissions reductions.
How to use this study
-
Board-level strategy: use the market sizing and scenario forecasts to validate capital expenditure profiles and acquisition targets through 2032.
-
Commercial teams: apply the contracting templates and competitor intelligence to sharpen proposals and win-share tactics in RFP processes.
-
Risk and compliance: adopt the regulatory matrix and supplier-scorecard to remediate sourcing risk and certify manufacturing partners against new content-origin rules.
-
Investment teams: use our valuation adjustments and due-diligence checklists to price deals that reflect regulatory and residual-value uncertainties.
Our study intentionally demonstrates analytical rigor without publishing every subsegment table in this summary. Detailed regional and application breakdowns, lease-duration splits, unit-level economics, and the full set of scenario models are included in the full report — along with interactive spreadsheets you can use to run bespoke sensitivity analyses for your portfolio. If your 2026 planning cycle hinges on fleet sizing, lease-tenor strategies, or sourcing decisions, this report provides the practical intelligence, models, and playbooks to convert insight into action.
Contact PW Consulting to access the full Railcar Leasing Market report and the accompanying tools that institutionalize these insights into board-ready recommendations and executable operational plans.
For detailed analysis of this topic, please visit the official page: Railcar Leasing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


