



PW Consulting: Dental Intraoral X-ray Sensors Market to Hit USD 473M by 2032 (8.6% CAGR)

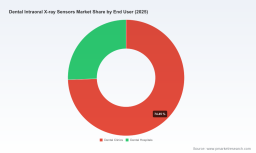
Dental Intraoral X‑ray Sensors Market — Strategic Briefing for 2026 Decision‑Making
Executive snapshot
Between 2020 and 2025 the global dental intraoral X‑ray sensors market more than doubled in scale, expanding from an estimated USD 142 million in 2020 to roughly USD 265 million by the 2025 base year. Our analysis projects ongoing momentum through the next planning horizon (2026–2032), with the market tracking at a compound annual growth rate of approximately 8.6% and an expected market size approaching USD 473 million by 2032. These headline metrics frame a market that is matureizing rapidly: adoption is shifting from point replacements to systemic digital upgrades across clinics and hospitals, while product innovation (notably higher resolution chips, wireless architectures and embedded AI) is changing competitive dynamics and buyer economics.
Dental Intraoral X-ray Sensors Market
Why this study matters for 2026 strategic planning
- Timing matters: 2026 is the inflection year where many OEMs transition from incremental hardware refreshes to platform plays — software, AI, and interoperability will determine value capture.
- Capital allocation: Board-level investment choices (M&A vs. organic R&D) require validated market sizing, adoption curves and concentration metrics to quantify upside and downside risk.
- Commercial strategy: Procurement cycles in dental clinics and hospitals are extending as buyers demand full-stack solutions (sensor + software + service); pricing and channel models must adapt accordingly.
- Regulatory & reimbursement environment: Compliance, clinical evidence and CPT/insurance positioning materially affect go‑to‑market timing and required spend for market entry.
Market trajectory and what drives it
The market’s historical expansion (2020–2025) reflects three concurrent shifts: transition from film to digital, rising procedure volumes in aging populations, and increased capital spending on dental clinic modernization. Moving into the 2026–2032 forecast period, growth will be sustained by technological enablers (higher pixel density, lower dose, wireless sensors, and software-defined imaging), ecosystem interoperability (sensor–PACS–practice management integration), and workflow automation (AI‑assisted diagnostics and reporting).
Dental Intraoral X-ray Sensors Market
For corporate planners, the most actionable takeaways are: (1) product differentiation is increasingly software-driven; (2) clinical validation and regulatory clearance timelines materially affect commercialization cadence; and (3) channel economics and service models (subscription, SaaS for imaging workstations, consumables and maintenance) will determine long‑term margin profiles.
Dental Intraoral X-ray Sensors Market
Regulatory, reimbursement and clinical dynamics
- Regulation: Devices in this category are governed under Class II medical device pathways and FDA 510(k) requirements; biocompatibility standards (e.g., ISO 10993‑1) apply to intraoral-facing materials. Regulatory lead times and post‑market surveillance obligations influence launch cadence and cost.
- Reimbursement: In many markets intraoral imaging is bundled with dental radiographic services and is commonly processed under established CPT codes when applicable. Understanding local reimbursement practice affects purchase ROI models for buyers and influences sales velocity.
- Clinical outcomes: Digital sensors not only improve diagnostic fidelity but, when implemented correctly, reduce patient radiation exposure compared with film-based workflows — a measurable clinical advantage that supports procurement decisions.
Competitive landscape — who shapes the market
The market exhibits moderate concentration: the top three vendors account for a meaningful share of the industry, and the top five consolidate over half of revenue across channels. This concentration creates a landscape where incumbent OEMs retain leverage through installed-base relationships and integrated suites, while challengers compete on niche innovations, price performance or wireless convenience.
Key industry players to watch (representative, not exhaustive):
- Dentsply Sirona — long-established OEM known for high‑resolution Schick sensors and integrated dental platforms.
- DEXIS (Dental Imaging Technologies Corporation) — recognized for durable intraoral sensors and evolving software ecosystems, increasingly embedding AI into imaging workflows.
- Planmeca Oy — vendor with a strong design focus on image quality and user ergonomics across digital imaging products.
- Vatech — notable for high‑resolution sensor lines and aggressive global distribution.
- Carestream Dental — leverages its radiography portfolio to sell integrated imaging solutions into dental practices and hospital dental units.
- Owandy Radiology, Freedom Technologies Group, Acteon, Qpix Solutions, XpectVision and others — a mix of regional champions and technology-focused entrants pushing wireless, zero‑profile and cost‑effective alternatives.
Recent vendor moves illustrate strategic direction: DEXIS expanded AI functionality within its imaging platform (early 2026) and has been active in wireless/imaging device introductions through 2025; Owandy released a next‑generation sensor in mid‑2025 that emphasizes speed and reliability; and Qpix secured regulatory clearance in late 2025, removing a common market entry barrier for new digital sensor suppliers. These developments signal two concurrent trends — incumbents expanding software/IP moats, and smaller players pursuing differentiated hardware or regulatory milestones to unlock distribution.
Where winners will be decided in 2026
- Platform vs. commodity: Vendors that can offer software-enabled clinical value (AI triage, automated measurement, integration with practice management) will command premium positioning versus hardware-only suppliers.
- Go‑to‑market sophistication: Integrated sales models (equipment + imaging software subscriptions + training/service) accelerate adoption and increase lifetime customer value; distributors still matter in certain geographies but digital channels are growing.
- Regulatory execution: Speed and thoroughness in 510(k) clearances and biocompatibility documentation create first‑mover advantage for new form factors (wireless or zero‑profile sensors).
- Clinical evidence: Prospective clinical validation and peer‑reviewed outcomes that demonstrate diagnostic equivalence or superiority and dose reduction will shorten procurement cycles for conservative buyers.
- Service economics: Warranty, remote diagnostics, and subscription models reduce buyer friction — vendors with robust service infrastructure will see stickier revenue streams.
Practical contents of the PW Consulting study — what you will find inside
The full report synthesizes market sizing (historical 2020–2025 and forecast 2026–2032), demand drivers, adoption barriers, technology roadmaps, regulatory pathway analysis and payer dynamics. It combines quantitative forecasts with qualitative fieldwork: supplier interviews, clinic procurement intelligence, and real‑world case studies of deployment and ROI.
Operational deliverables include:
- Actionable segmentation frameworks and adoption curves for different end‑user profiles (clinic, hospital and specialty practices).
- Detailed vendor benchmarking across product performance, interoperability, regulatory status and go‑to‑market models.
- Scenario analyses that stress-test strategies under alternate reimbursement and regulatory timelines.
- Priority playbooks for market entry, alliance formation and M&A screening (including integration checklist and typical synergies).
Strategic recommendations for corporate leaders in 2026
For OEMs and investors preparing 2026 decisions, we condense our view into six strategic moves:
- Pivot to software-defined differentiation: Invest selectively in imaging analytics and clinician workflow integration rather than relying solely on marginal hardware improvements.
- Secure regulatory momentum: Accelerate 510(k) and biocompatibility efforts to shorten commercialization timelines for novel sensor formats.
- Optimize channel economics: Develop hybrid commercial models — direct enterprise sales for large hospital systems and channel partnerships for clinic networks.
- Pursue targeted M&A: Acquire niche players that bring wireless, low‑dose technologies or market access in underpenetrated geographies; prioritize assets that fill product or software gaps.
- Clinical & payer engagement: Invest in evidence generation that demonstrates dose reduction and diagnostic equivalence to strengthen reimbursement positioning and procurement justification.
- Operational resilience: De‑risk supply chains for critical image sensor components and plan inventory strategies to manage spikes in demand during upgrade cycles.
What the report deliberately withholds — and why
To maintain an actionable edge for subscribers, the public briefing intentionally omits granular regional and application split figures, vendor share tables by region, and transaction‑level pricing schedules. Those granular insights are available in the full report and include regional adoption curves, application‑level demand projections, channel margin models and vendor share analytics that buyers and investors use to build financial models and go‑to‑market plans.
Next steps — how to use this briefing in board and planning forums
- Use headline growth and concentration metrics to stress test investment theses in 2026 budgeting rounds.
- Prioritize regulatory timelines in product roadmaps and ensure cross‑functional resourcing (R&D, regulatory, clinical affairs) aligns with go‑to‑market windows.
- Frame M&A screening criteria around software capability, clinical evidence and installed‑base access rather than only on hardware features.
- Engage with payers and large dental groups early to pilot reimbursement‑sensitive propositions that demonstrate faster payback periods for buyers.
PW Consulting’s full Dental Intraoral X‑ray Sensors Market report (base year 2025, forecast 2026–2032) provides the underlying datasets, regional and application segmentation, vendor share matrices and implementation playbooks required to convert the strategic direction above into executable programs. For teams preparing capital allocation, product roadmap or market entry decisions in 2026, the report turns market momentum into prioritized operational actions.
For detailed analysis of this topic, please visit the official page: Dental Intraoral X-ray Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


