



PW Consulting: Sodium Dichromate Market to reach USD 2,176.14M by 2032 (5.2% CAGR)

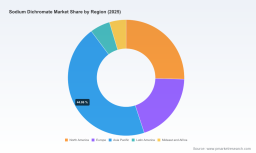
Sodium Dichromate Market — Strategic Outlook for 2026 Decision-Making
Executive snapshot
PW Consulting’s Sodium Dichromate Market briefing synthesizes five years of audited history (2020–2025, base year 2025) and a seven‑year forecast horizon (2026–2032) to give decision‑makers evidence‑based vantage points for 2026 strategy. The market has grown from approximately USD 1,217 million in 2020 to roughly USD 1,524 million in 2025 and is projected to expand to just over USD 2,176 million by 2032, reflecting a compound annual growth rate (CAGR) of about 5.2% across the 2026–2032 forecast period. These headline metrics mask important structural shifts — regulatory pressure, feedstock concentration, evolving end‑use demand and regional capacity dynamics — that will determine winners and losers in the coming 18 months.
Sodium Dichromate Market
Why this research matters for 2026 decisions
- Regulatory inflection point: Sodium dichromate (a hexavalent chromium compound) faces elevated regulatory scrutiny in major markets. Recent regulatory actions and proposals — including formal REACH restriction initiatives and inclusion on EU candidate lists — create asymmetric downside risk for suppliers and downstream users that do not proactively adapt compliance, product and sourcing strategies.
- Supply‑chain fragility: Production is tied to chromite ore feedstock and concentrated manufacturing footprints. Changes in ore availability, export controls or localized capacity additions can create price and availability swings that ripple through metal finishing, pigment and preservation value chains.
- Commercial leverage windows: The market’s structure (top suppliers account for roughly a third of volume) provides tactical opportunities for mid‑sized and large participants to secure advantaged positions through offtake contracts, targeted capacity investment, or regional trade strategies.
- Strategic timing: With a steady multi‑year growth runway implied by the 5.2% CAGR, 2026 is a pivotal year for crystallizing capital allocation choices — whether to invest in capacity, pivot toward alternative chemistries, or accelerate M&A to capture scale and compliance capability.
Headline market dynamics (what is moving the needle)
- End‑use demand is resilient but evolving. Traditional outlets such as metal finishing and pigments continue to underpin volume, while niche industrial applications and specialty synthesis provide pockets of higher‑margin demand.
- Regulatory tightening across the EU and other advanced markets introduces compliance costs and potential market re‑routing. On April 29, 2025 the European Chemicals Agency signalled intent to propose a restriction under REACH on hexavalent chromium substances, and chromium VI materials remain subject to authorization and candidate‑list treatments. These developments increase the probability of market segmentation between jurisdictions with strict restrictions and those with more permissive regimes.
- Feedstock economics matter. Chromite ore availability and pricing dynamics remain central to producer margins. The material dependency elevates the value of integrated feedstock access and vertical coordination in supplier selection and contract design.
- Capacity and supply geography are shifting. Asian producers continue to expand export‑oriented capacity while some incumbent producers in other regions pursue process modernization and quality differentiation to defend share.
- Market concentration is moderate. The three largest suppliers collectively account for approximately one‑third of the market, which creates both competitive pressure and opportunity for coalition strategies, particularly in sourcing and compliance investments.
Competitive landscape — how the leading players are positioning
- Vishnu Chemicals Limited (Hyderabad, India) — A primary manufacturer with market‑grade product purity and packaging options that target both industrial and export customers. Notable for recent capacity expansions designed to assure global supply continuity. Strategic view: plays the volume and reliability card while pursuing incremental downstream penetration.
- Nippon Chemical Industrial Co., Ltd. (Japan) — Focused on high‑purity product offerings for demanding metal treatment and aerospace applications. Competitive advantage rests on stringent quality control, premium positioning, and established Asian distribution channels. Strategic view: defends high‑end segments where switching costs and quality requirements are greatest.
- Hubei Zhenhua Chemical Co., Ltd. (China) — Operates as an agile supplier in a price‑sensitive segment of the market, benefitting from local feedstock access and scale manufacturing. Strategic view: competes on cost and rapid order fulfilment, making it a go‑to for bulk industrial buyers.
- Yinhe Group (China Yuanhe Chemical Industry Group) — An integrated producer with export orientation and investment in modern production practices. Strategic view: leverages vertical integration to shield margins from feedstock volatility and to pursue stable long‑term export contracts.
- Soda Sanayii A.S. (Turkey) — Emphasizes production efficiency and product purity for regional markets. Strategic view: well positioned to serve nearby industrial clusters and to exploit regional trade flows as regulatory regimes diverge.
Collectively these players illustrate two competing strategic archetypes: technology/quality differentiation (to capture higher‑margin, compliance‑sensitive demand) and cost/scale optimization (to serve volume industrial channels). The market’s moderate concentration means that strategic moves by any of the major suppliers can materially influence pricing and availability in targeted end markets.
Sodium Dichromate Market
What the full report delivers (practical, usable content)
- Verified market sizing and trend tables (2020–2025 historic audit, 2026–2032 forecast) with scenario variants sensitive to regulatory outcomes and feedstock shocks.
- Granular segmentation by region and application (note: detailed splits are available only in the full report to protect competitive intelligence; this executive preview omits granular percentages by design).
- Supply‑chain map linking chromite feedstock sources, conversion hubs, and downstream industrial clusters; supplier capability and capacity trackers updated to base‑year 2025.
- Regulatory impact models that quantify potential demand displacement under REACH restriction and authorization pathways across policy timelines.
- Company scorecards covering production footprint, purity range, packaging, recent investments and strategic posture for the top manufacturers.
- Commercial playbooks — procurement contracting templates, hedging and inventory strategies, and product substitution decision matrices for R&D and procurement teams.
- Investment and M&A screening filters that highlight targets and acquirers aligned with either vertical integration or technology differentiation strategies.
Recommended 2026 actions for executives and procurement leads
- Adopt a three‑track regulatory strategy: comply (immediate), hedge (short term) and innovate (medium term). Prioritize audits, authorization readiness, and substitution R&D where feasible.
- Pursue supplier diversification across geographies and feedstock sources. Where possible, secure multi‑year offtake agreements with capacity reservation clauses to mitigate supply shocks.
- Invest selectively in alternative chemistries and internal recycling capabilities to reduce dependence on hexavalent chromium streams — particularly for product lines exposed to European end‑users.
- Use the 2026 window to execute defensive M&A or strategic partnerships that quickly add compliance capabilities, higher‑purity product lines, or feedstock integration.
- Institute real‑time regulatory monitoring and scenario planning in procurement and corporate risk functions. Prepare pricing models that transparently allocate incremental compliance costs across customers.
- Optimize working capital via dynamic inventory strategies: increase buffer stocks for critical SKUs if exposure to restricted markets remains high, and deploy just‑in‑time procurement for less sensitive product variants.
- Engage proactively with standards bodies, customer coalitions and regulators to shape practical implementation timelines and to seek transitional provisions where feasible.
How to use this research inside your organisation
- Board & C‑suite: calibrate capital allocation against the 5.2% CAGR baseline and regulatory downside scenarios included in the report.
- Corporate development: leverage the target filters and company scorecards to prioritize acquisitions that close compliance or feedstock gaps.
- Procurement & supply chain: implement the supplier scorecards and hedging playbooks to reduce single‑point feedstock risk and secure margin protection.
- R&D & product teams: use the substitution decision matrix and cost‑benefit models to accelerate development of trivalent chromium‑based or non‑chromium alternatives for exposed product lines.
- Regulatory & EHS: adopt the report’s regulatory timeline scenarios and use the compliance impact quantification to budget for authorization and end‑of‑use remediation costs.
Conclusion — the strategic imperative for 2026
The sodium dichromate market is not a simple volume story; it is a nexus of regulatory trajectories, feedstock economics and targeted industrial demand. The base‑year reality (USD ~1,524 million in 2025) and our forecast to 2032 imply steady growth, but 2026 will be decisive in translating that growth into durable competitive advantage. Firms that combine pragmatic compliance planning, supply diversification and selective investment in higher‑value product offerings will navigate the coming regulatory and commercial shifts most successfully.
Sodium Dichromate Market
PW Consulting’s full Sodium Dichromate Market study provides the granular tables, segmentation detail, regulatory scenario outputs and supplier scorecards necessary to operationalize the recommendations above. For access to the complete dataset and the actionable appendices that underwrite these strategic recommendations, please consult the full report on our website.
For detailed analysis of this topic, please visit the official page: Sodium Dichromate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


