



PW Consulting: Sulphur Recovery Market set for 2.51% CAGR through 2032 as Asia Pacific tops 54.19%

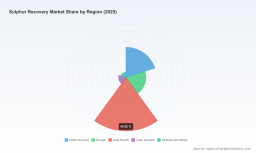
Sulphur Recovery Market — 2026 Strategic Briefing
As PW Consulting’s lead industry analyst, this briefing synthesizes the strategic implications of our Sulphur Recovery Market research for corporate decision-making in 2026. The study combines a rigorous historical audit (2020–2025), a re‑based 2025 market view and an actionable forecast through 2032. Our findings show a market transitioning from recovery‑centered capital projects toward service, optimization and regulatory‑driven retrofit spending — a shift that should reshape vendor strategies, procurement tactics and capital allocation over the next 18 months.
Sulphur Recovery Market
Executive snapshot: market scale, trajectory and structure
Key macro indicators distilled from the research: the market expanded meaningfully during the early 2020s, with a visible upcycle through 2024. After methodological re‑baselining in 2025, the market is estimated at approximately USD 118 million (base year 2025). Our forecast through 2032 anticipates a steady but moderate recovery, with the market tracking to roughly USD 140 million by 2032 at a compound annual growth rate of about 2.51% from the 2026 starting point.
Sulphur Recovery Market
Two structural features stand out for strategy teams: first, concentration — the top three suppliers capture a substantial majority of market share (CR3 ~65%), and the top five approach near‑dominant levels (CR5 ~85%). Second, the market is increasingly defined by lifecycle services (optimization, aftermarket spares, turnkey tail‑gas upgrades) rather than pure greenfield SRU sales alone. These realities should inform 2026 choices on partnerships, M&A appetite and commercial models.
Sulphur Recovery Market
Why 2026 is a decision inflection point
- Regulatory compression: New and tightening emissions standards (domestic air quality regulations and expanding ECA/IMO limits) are narrowing compliance windows and elevating the value of high‑efficiency tail‑gas treating solutions.
- Operational maturity: Numerous refineries and gas processing assets that expanded capacity earlier this decade now require modernization — creating sizeable opportunity for retrofits and digital optimization services.
- Capital discipline: Prevailing macroeconomic caution is shifting buyer preference toward modular, high‑ROI upgrades and service contracts rather than large lump‑sum CAPEX projects.
These combined forces mean that 2026 is the year organizations need to choose whether to compete on technology, on integrated service models, or on regional execution excellence. Each path has distinct implications for procurement, alliances and risk exposure.
Market dynamics and value pools (what to watch)
- Compliance‑driven retrofit demand: Emission limits and permitting timelines are the most immediate drivers of capital and service spend. Expect procurement cycles to accelerate where plants face near‑term permitting renewals or ECA compliance deadlines.
- Aftermarket & servicing growth: As installed SRU fleets age, spend shifts from new builds to optimization, catalyst supply, maintenance and revamps — these annuity streams have higher margin potential and lower sales cycle friction.
- Technology bifurcation: Traditional Claus process platforms remain a central backbone, but demand for advanced tail‑gas treatment and low‑temperature oxidation solutions is rising where operators must hit ultra‑low emission targets.
- Modularization and regional execution: Prefabricated and modular SRU solutions shorten schedules and reduce on‑site risk — attractive in markets with constrained skilled labor or compressed timelines.
Competitive landscape — positioning and playbooks
The market is populated by a mix of licensors, EPC integrators and specialized service houses. Our competitive analysis emphasizes capability clusters rather than a simple ranked list, enabling buyers to map vendors to specific strategic needs.
- Licensors with legacy process depth: Established licensors provide proven Claus and related technologies, offering reliability and known performance envelopes — a low‑technology‑risk choice for large, integrated refineries.
- EPCs and integrators: Large engineering firms couple licensing with project execution and financing structuring; they are preferred when scale and schedule integration across complex refinery revamps are critical.
- Specialists and aftermarket plays: Niche providers focus on optimization, TGTU retrofits, catalyst services and sour water systems — these firms are the primary beneficiaries as the market shifts to life‑cycle services.
- Regional and modular suppliers: Firms offering modular SRUs and regionally tailored delivery models win where speed-to‑market and local content are procurement priorities.
Selected recent commercial moves illustrate these dynamics: a major EPC won an FEED contract for a gas cap project including dedicated sulphur recovery scope; a technology integrator secured contracts to upgrade gas plant recovery efficiencies to near 99.9%; and a refinery invested in a new SRU as part of a broader modernization push. These are not isolated transactions but signals of where allocation of engineering and capital resources is headed.
Technology landscape — practical implications for buyers
- Claus remains the backbone: Operators seeking lowest‑risk pathways continue to rely on established Claus variants for core recovery.
- Advanced tail‑gas options: For sites with tight emission targets, investing in high‑efficiency tail‑gas treatment or LOX (low‑temperature oxidation) can be non‑negotiable; the trade‑off is higher integration complexity and service dependency.
- Integration with hydrogen and sulphur handling: Designs that optimize heat integration, hydrogen recovery and sulphur degassing deliver lifecycle OPEX benefits — a key selection criterion in 2026 procurement decisions.
Regulatory & feedstock drivers — risk vectors for 2026
Compliance frameworks remain a principal demand driver. U.S. federal and state rules define permitting parameters for SRUs, and expanding maritime fuel sulphur controls continue to shape upstream gas processing and refining economics. In parallel, feedstock variability — notably fluctuating H2S concentrations — materially affects technology selection and lifecycle cost models.
For decision‑makers, this translates into three practical imperatives: (1) model sensitivity to feedstock composition in every economic case, (2) validate vendor emissions performance under commissioning conditions, and (3) incorporate regulatory timelines into procurement SOWs to avoid schedule‑driven cost penalties.
What the full PW Consulting report delivers (practical, actionable contents)
Our report is purpose‑built for executives, strategy teams and procurement leads planning 2026 initiatives. It contains:
- Historical reconciliation (2020–2025) and an explicit explanation for the 2025 re‑baselining so stakeholders can reconcile internal forecasts with public comparables;
- Forward scenarios through 2032 with base, upside and downside cases built from plant‑level drivers, regulatory timelines and capex schedules;
- Vendor maps and a capability matrix that cross‑walks licensors, EPCs and specialist service providers against technical, execution and commercial strengths;
- Commercial playbooks for procurement, including bid templates, evaluation scorecards, and contract clauses to protect against feedstock volatility and emissions non‑compliance;
- CAPEX/OPEX models, sensitivity tables and break‑even analyses to evaluate retrofit vs new‑build choices;
- Due diligence checklists for M&A and JV opportunities focused on technology debt, spare‑parts exposure and service backlog quality;
- Case studies and lessons learned from recent projects, highlighting common execution risks and mitigation tactics.
To honor the “preview” intent of this briefing, the report intentionally retains proprietary granular splits (regional and application level breakdowns, and detailed vendor share tables) within the full deliverable — these are available to subscribers and clients who access the complete dataset.
Strategic recommendations for 2026
- Prioritize compliance windows: Where permitting or ECA deadlines are within a 24–36 month horizon, favor modular or EPC‑backed solutions with proven emissions performance rather than lowest‑cost licensors alone.
- Lean into service models: Companies seeking margin expansion should accelerate offerings in catalyst supply, TGTU retrofits and remote optimization — these generate predictable annuity revenue and shorten sales cycles.
- De‑risk through partnerships: Consider technology licensing + regional execution partnerships to blend process certainty with local delivery capability and cost control.
- Stress test assumptions: All project economics should be stress‑tested against H2S composition swings, evolving emissions rules and potential schedule slippage driven by permitting.
- Use procurement to create advantage: Tender structures that split scope into technology licensing, balance‑of‑plant EPC and a separate service agreement permit competitive pricing with long‑term service guarantees.
Conclusion — how this research informs 2026 choices
The Sulphur Recovery sector is no longer solely a market of stand‑alone catalyst and process licensors. By 2026, value is accruing to firms that couple technology with lifecycle services, execution agility and regulatory know‑how. The market will grow modestly through 2032, but the real opportunities are being created in retrofit, tail‑gas upgrading and aftermarket services — areas with accelerated decision cycles and higher gross margins.
PW Consulting’s full Sulphur Recovery Market research provides the calibrated datasets, vendor benchmarking and executable playbooks you need to make those 2026 choices with confidence. For the full report, proprietary segment breakdowns and downloadable financial models, visit PW Consulting’s Sulphur Recovery Market page or contact our research team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Sulphur Recovery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


