



PW Consulting: Sunglasses Market Set for 6.5% CAGR Through 2032

Sunglasses Market Outlook 2026: Strategic Imperatives for Corporate Leaders
Executive snapshot
As PW Consulting’s senior industry team, we present a concise, high-confidence orientation for corporate leaders operating in—or considering entry into—the global sunglasses market. Our full Sunglasses Market research (base year 2025; historical window 2020–2025; forecast 2026–2032) combines granular commercial intelligence, proprietary scenario modelling and pragmatic playbooks designed to inform high-stakes 2026 decisions.
Sunglasses Market
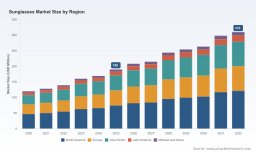
At the macro level, the industry has shown resilient expansion, growing from a modest base at the start of the decade to an estimated market size of USD 190 million in 2025, and we project that momentum to continue: by 2026 the market moves above the USD 200 million threshold and, applying a 6.5% compound annual growth rate through 2032, the market approaches the low hundreds of millions by the end of the forecast horizon. This trajectory reflects a mix of premiumization, technical lens innovation, and widening consumer use-cases beyond traditional fashion demand.
Sunglasses Market
Why this report matters for 2026 decisions
- Actionable trade-offs for capital allocation. Whether your board is weighing R&D investment in photochromic or polarized lens technology, planning M&A to scale distribution, or debating manufacturing nearshoring—this study maps the expected returns to each pathway under three realistic macro-scenarios.
- Supply-chain resilience planning. With recently introduced duties and material tariffs reshaping input costs and supplier footprints, our supply-chain stress tests show which sourcing plays preserve gross margins and which amplify risk.
- Go-to-market optimisation. We translate channel economics—digital direct-to-consumer, wholesale licensing, and specialty retail—into prioritized actions for 12–24 month execution plans.
- Sustainability and regulation as value creators. Faster adopters of recycled-frame content and low-carbon optics demonstrate measurable shelf advantage; our routing helps convert sustainability commitments into near-term P&L improvements.
Market dynamics — what is changing and why it matters
- Premiumization vs. democratization. High-end licensing and performance-led brands continue to expand perceived value, while a wave of affordable, performance-oriented entrants pressures price bands. The result is a bifurcated market where margin pools and unit growth do not always coincide.
- Lens and material innovation. Lens differentiation remains a core engine of value—advanced polarized, mirror coatings and photochromic treatments are shifting purchase criteria from aesthetic-only to functional utility. Concurrently, frames made with high recycled-content blends are transitioning from ESG “nice-to-have” to commercial differentiator.
- Regulatory and tariff shocks. A cluster of tariff actions implemented in 2025 introduced material cost volatility: targeted duties on Chinese-origin components and broader levies on inputs such as steel and aluminum have caused multi-market repricing pressure. Additive tariffs affecting North American cross-border inputs further complicate nearshore vs. offshore trade-offs. Our scenario modules quantify the margin sensitivity and breakpoints associated with each policy vector.
- Distribution and omnichannel acceleration. Retail behaviors continue evolving post-pandemic: omnichannel retailers and brand-owned DTC operations capture higher lifetime value, while specialty optical networks remain important for prescription-based and premium performance lenses. The ideal channel mix is company-specific; our report prescribes precise channel optimization pathways by archetype.
- Consolidation and competitive intensity. Industry concentration is material: the top three players account for a meaningful majority of market value, with the top five capturing roughly four-fifths of industry revenues. This structure drives strategic outcomes—pricing discipline at scale, accelerated licensing activity, and high barriers for national-scale entrants—while leaving exploitable niches for nimble innovators.
Competitive landscape — what the major players are doing
Our competitive audit covers the full spectrum from global conglomerates to niche specialists. Below are high-level strategic positions for the core participants analysed in the study:
Sunglasses Market
- EssilorLuxottica (France) — A scale leader that leverages a diverse luxury and performance portfolio (Ray-Ban, Oakley, Costa, Oliver Peoples) and broad lens manufacturing capabilities. Their strategy remains centered on premium brand management, vertical integration of lenses and frames, and visibility at major industry events to signal future technology priorities.
- Kering Eyewear (Italy) — Positioned around high-fashion licensing and adventure-oriented collections, Kering’s approach blends luxury brand prestige with selective polarized-lens innovation. Recent global campaigns emphasize lifestyle storytelling to drive aspirational attachment.
- Safilo Group (Italy) — A traditional frame manufacturer shifting toward portfolio scale through targeted acquisitions and expanded licensing. Recent deal activity aims to broaden access to performance and lifestyle subcategories.
- De Rigo Vision (Italy) — An early mover on sustainability, experimenting with high recycled-content frames and performance-driven collections. Their eco-frames achieved measurable retail unit mix shifts in peak seasons, demonstrating how sustainability can convert into commercial traction.
- Marcolin (Italy) — A licence-focused manufacturer that couples fashion credentials with production agility; Marcolin’s model prioritises brand partnerships to access distinct consumer segments.
- Maui Jim (United States) — A specialist in polarized, performance lenses targeted at fishing and outdoor lifestyles; proprietary lens tech delivers a defensible position in outdoor and sport segments.
- goodr (United States) — A digitally native challenger built on affordability, fun branding and active performance features; they exemplify how focused product-market fit can scale via DTC channels.
- Bajio Sunglasses (United States) — A premium polarized specialist focused on water-sport and fishing audiences, leveraging product authenticity and niche distribution to maintain margin density.
We supplement these strategic profiles with a chronological tracker of recent developments—global campaigns, acquisition announcements and exhibition visibility—so executives can anticipate where competitive pressure will intensify in 2026 and beyond.
Practical contents of the full report (what you will get)
To preserve commercial value, this introduction highlights the report’s practical modules without publishing the underlying segment-level data. The full report contains:
- Proprietary demand-scenario models that combine consumer-behaviour shifts, tariff scenarios and technology adoption curves to generate P&L-sensitive forecasts for 2026–2032.
- Channel economics playbooks with actionable KPIs for DTC, wholesale, specialty optical and omnichannel partnerships—complete with SKU rationalization templates and margin-optimisation levers.
- Supply-chain relocation and sourcing decision matrices, stress-testing combinations of duty schedules, freight shifts and nearshore manufacturing options.
- Sustainability transition blueprints that quantify incremental CAPEX and time-to-payback for recycled-content frames, low-carbon logistics and circular take-back programmes.
- Go-to-market and M&A scorecards: target archetype matrices, valuation frameworks and integration risk checklists designed for rapid investment committee review.
- Competitive threat simulations and tactical response playbooks, including pricing defence strategies and co-branding/licensing optimisation guides.
Strategic implications and recommended actions for 2026
- Reassess sourcing in light of tariffs. If your cost base relies on components affected by recent duties, 2026 is a tipping point: either absorb, reprice or restructure. Our margin-sensitivity outputs pinpoint which SKUs to preserve and which to reengineer.
- Prioritize high-conversion sustainability interventions. Not all ESG investments generate equivalent commercial returns. We identify the “first-mover” sustainability changes (materials, packaging, certification) that produce immediate retail uplift and defensible premium pricing.
- Match channel strategy to brand archetype. For premium/licensed brands, invest in branded experiences and selective wholesale; for performance and active categories, accelerate DTC + community marketing. Tactical merchandising and inventory rotations vary materially—our playbooks assign execution sequencing by archetype.
- Use M&A to shore up missing capabilities, not volume. Given the concentrated market, small-scale bolt-ons that add proprietary lens tech, specialty distribution or sustainability credentials often deliver better returns than purely volumetric roll-ups.
- Protect margin through product architecture. Modularizing lens and frame SKUs reduces exposure to input cost swings while enabling premiumization via add-on services (prescription lenses, coatings, extended warranties).
Concluding perspective
The sunglasses market in 2026 is simultaneously a mature brand-driven arena and a frontier of technical and sustainability-led disruption. The sector’s growth profile—solid headline expansion supported by a 6.5% CAGR over our forecast window—creates both opportunities and pitfalls. Scale advantages and concentration mean incumbent actions will shape market structure, but nimble, well-capitalised challengers can win through focused product differentiation, channel discipline and operational rewiring to mitigate tariff headwinds.
PW Consulting’s full Sunglasses Market research provides the data, scenarios, and playbooks executives need to translate this outlook into decisive 2026 strategies. For segment-level breakdowns, SKU-level elasticity figures, and our proprietary scenario outputs, access the complete study on our report landing page.
For detailed analysis of this topic, please visit the official page: Sunglasses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


