



PW Consulting: Automated Biochemical Analyzers Market at USD 3,145.49M in 2025; CAGR 5.51%

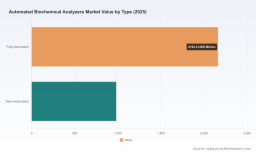
Automated Biochemical Analyzers Market — Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise strategic briefing designed to orient executive teams, corporate development groups, and product leaders preparing decisions in 2026. The automated biochemical analyzers market is in a steady expansion phase: our base-year model (2025) pegs the global market at USD 3,145.49 Million (USD Million), up from USD 2,426.75 Million in 2020. Under central assumptions the market grows at a compound annual growth rate (CAGR) of 5.51%, with projected market revenue of approximately USD 3,407.66 Million in 2026 and an extended forecast reaching USD 4,525.81 Million by 2032. These headline figures underpin the strategic implications summarized below — a clear signal that market momentum supports both organic investment and targeted inorganic plays, but requires disciplined segmentation and risk management to capture sustainable returns.
Automated Biochemical Analyzers Market
Why this research matters for 2026 decisions
- Timing: 2026 is the inflection year for several regulatory and procurement shifts that materially affect instrument adoption cycles, service revenue potential, and reimbursement dynamics.
- Capital allocation: With steady mid-single-digit CAGR, boards must choose between deploying CAPEX into platform upgrades versus expanding consumables/service channels that compound recurring revenue.
- M&A and partnership selection: The market’s moderate concentration (CR3 ≈ 25.6%, CR5 ≈ 34.2%) indicates opportunity spaces for bolt-on acquisitions and distribution partnerships, particularly in under-penetrated geographies and niche clinical workflows.
- Execution risk: Device classification, software lifecycle obligations, and government procurement schedules mean go-to-market plans must be synchronized with regulatory filings and post-market surveillance investments.
Market trajectory and strategic signals
The market’s growth profile—from USD 2,426.75M in 2020 to USD 3,145.49M in 2025, progressing to an expected USD 3,407.66M in 2026—reflects a blend of reliable demand for routine clinical chemistry and immunoassay capacity, rising throughput needs in reference laboratories, and gradual modernization of hospital labs in growth markets. Technology consolidation around integrated platforms (chemistry + immunoassay) is a defining trend: customers increasingly favor systems that reduce manual touchpoints and offer consolidated reagent and service economics.
Automated Biochemical Analyzers Market
Key demand drivers to weigh in strategic plans:
Automated Biochemical Analyzers Market
- Demographic and epidemiological tailwinds (aging populations and chronic disease testing demand) that sustain baseline volume growth.
- Laboratory consolidation and centralization which increase preference for high-throughput, fully automated platforms in larger health systems, while decentralization trends support compact systems for point-of-care networks and community hospitals.
- Service and consumables economics: as instrument sales slow relative to installed base value, recurring consumables and service contracts become central to lifetime value calculations.
- Regulatory and software risk: increased scrutiny on device software and post-market controls requires investment in compliance and cyber/hardware lifecycle practices.
Competitive landscape — profiles and recent strategic moves
The competitive field combines global OEMs with strong installed-bases and vertically integrated reagent strategies, established mid-sized players targeting cost-performance trade-offs, and agile regional vendors focusing on price-sensitive markets and fast local support.
- Roche Diagnostics (Indianapolis, IN, USA): A portfolio approach centered on integrated cobas solutions for chemistry and immunoassay; continues to leverage brand trust and global service infrastructure. 2026 regulatory activity included FDA clearance for key analytical units in its integrated solution, which strengthens its position for US institutional procurement cycles.
- Abbott Laboratories (Abbott Park, IL, USA): Offers Alinity series as an integrated automation play, emphasizing throughput and workflow integration for large labs. Their commercial muscle in consumables remains a differentiator.
- Siemens Healthineers (Munich, Germany): Positions Atellica as a high-throughput, modular option for centralized labs, with an emphasis on interoperability within hospital information systems.
- Beckman Coulter (Brea, CA, USA): Known for scalable chemistry platforms; 2025 saw both a regulatory setback (recall linked to software design on a variant of its DxC series) and subsequent regulatory clearances for upgraded units—underscoring the criticality of software lifecycle and remediation programs.
- QuidelOrtho (San Diego, CA, USA): Focused on integrated VITROS platforms and expanding reach through innovative programs (e.g., a Certified Analyzer Program launched to broaden availability in rural/community hospitals).
- Mindray, YHLO Biotech and other China-based OEMs: Aggressive product introductions and cost-positioning target emerging markets and price-sensitive segments, with recent launches showcased at trade events for their mid-to-high throughput models.
- Regional players (Agappe, Eurolyser, Meril, YSI Life Sciences): Continue to defend niches with compact systems, rapid service response, and local regulatory familiarity.
Collectively, vendor strategies reveal three competing playbooks: (1) platform incumbency with integrated reagent lock-ins; (2) service-led growth where instrument economics support durable service margins; and (3) volume-based expansion by cost-competitive vendors targeting emerging markets and smaller facilities. Each approach entails different capital and execution risks.
Regulatory, reimbursement and procurement dynamics that matter
Regulation and reimbursement are not background noise; they are active forces shaping device demand and total cost of ownership. Automated biochemical analyzers are generally classified as Class II devices and often subject to 510(k) premarket pathways or equivalent approvals; this affects time-to-market and clinical validation investments. Notable industry events in recent cycles include a device recall tied to software issues on a major vendor’s platform and multiple FDA clearances for upgraded analytical modules — both highlighting the dual nature of regulatory events as risks and opportunities.
On reimbursement and procurement: instrumented clinical chemistry testing is covered under established CPT codes, which stabilizes unit reimbursement for clinical payors. In parallel, government procurement frameworks (for instance, federal supply schedule programs) are increasingly relevant for vendors pursuing public tenders and VA-equivalent business. These levers must be built into pricing models and tender strategies.
What PW Consulting’s full report delivers (practical, operational modules)
- Executive dashboard: topline market sizing, growth scenarios, and strategic implications tailored to C-suite decision points.
- Proprietary forecast engine (2026–2032): base, upside, and downside scenarios with sensitivity to volume growth, ASP evolution, and service attach rates.
- Go-to-market playbooks: segmentation of buyer personas, procurement pathways, tender-winning tactics, and field-service scaling models.
- Vendor intelligence: deep profiles of leading OEMs, recent product and regulatory developments, partnership matrices, and competitive threat mapping.
- Revenue architecture models: instrument vs consumables vs service revenue curves, payback period analyses, and financing structures for managed-equipment services.
- Regulatory and compliance roadmap: device classification guidance, software assurance requirements, and post-market surveillance best practices.
- M&A and inorganic growth toolkit: screening criteria, valuation yardsticks for bolt-ons, and integration checklists focused on consumable synergies and service network expansion.
- Operational annexes: procurement templates, draft service contract terms, and a validated Excel model for scenario planning.
Note: this briefing intentionally omits the granular split tables and some subsegment-level metrics in order to preserve the “trailer” effect — the full report contains the exhaustive segmentation matrices, region-by-region demand drivers, application-level volumes and price analytics required for execution. Access to those tables is available through PW Consulting’s distribution channels.
How to use this intelligence in 2026 — five actionable moves
- Prioritize post-market software investment now: regulatory events in 2024–2026 highlight that software design and maintenance are decisive for both market access and liability management.
- Rebalance CAPEX vs recurring revenue: use the forecast engine to stress-test scenarios where instrument sales slow and service/consumable attach rates must bridge revenue growth.
- Pursue selective partnerships to enter low-cost regions: partner models reduce up-front investment while capturing recurring revenues from reagents and service.
- Use procurement intelligence to win tenders: align product configurations, warranty terms, and installation timelines with public schedule obligations and hospital procurement cycles.
- Screen M&A targets for consumable synergies: acquisitions that increase consumable market share or service density often deliver higher long-term value than instrument-centric deals.
Conclusion — positioning for sustainable advantage
The automated biochemical analyzers market offers predictable growth and structural revenue opportunities. However, realizing attractive returns in 2026 requires executives to blend traditional strengths (product performance, service networks) with disciplined investments in compliance, software lifecycle management, and consumable monetization strategies. The market’s moderate concentration leaves room for focused competition and consolidation — but success depends on executional detail, which is where rigorous segmentation, procurement intelligence, and scenario-driven valuation matter most.
For teams preparing capital plans, M&A pipelines, or product roadmaps this year, PW Consulting’s full Automated Biochemical Analyzers Market report provides the granular segmentation, vendor-level datasets, and executable playbooks needed to convert market growth into sustainable competitive advantage. The summary data above highlights the opportunity — the full report supplies the maps to navigate it.
For detailed analysis of this topic, please visit the official page: Automated Biochemical Analyzers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


