



Sanitary Napkin Market Set to Expand at 6.98% CAGR — PW Consulting Insight

Sanitary Napkin for Feminine Care Market — Strategic Briefing for 2026 Decisions
PW Consulting presents a forward-looking executive introduction to our comprehensive Sanitary Napkin for Feminine Care Market study. This briefing articulates the strategic value of the underlying research for corporate leaders planning investments, portfolio shifts, M&A, regulatory preparedness, and operational design across 2026. It highlights the macro trajectory, competitive dynamics, regulatory inflection points, and the types of operationally useful deliverables contained in the full report — while intentionally withholding granular segment allocations to preserve the report’s role as the primary source for tactical execution.
Sanitary Napkin for Feminine Care Market
Market at a Glance: Growth Trajectory and Structural Snapshot
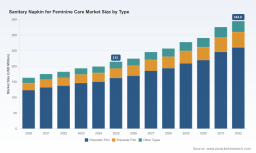
The sanitary napkin market has exhibited steady expansion through the early 2020s. Using 2025 as the base year, our model places the global market at approximately USD 215.0 Million in 2025. From that base, the market is projected to grow at a compound annual growth rate (CAGR) of 6.98% over the 2026–2032 forecast window, reaching roughly USD 344.8 Million by 2032.
Sanitary Napkin for Feminine Care Market
Two implications are immediate for executives: first, demand fundamentals remain robust enough to support new product investment and capacity expansion; second, the pace of growth reinforces the importance of timing — early entrants on improved-product platforms or optimized supply chains can capture disproportionate value as the market scales.
Sanitary Napkin for Feminine Care Market
Why this study matters for 2026 strategic decisions
-
Investment prioritization. With an almost 7% CAGR, capital allocation choices around manufacturing, R&D, and go-to-market need to be quantified relative to alternative uses. Our report supplies scenario-tested ROI models and stress-tests assumptions under different adoption curves and cost-inflation scenarios, enabling CFOs and corporate development teams to rank and pace investments.
-
Portfolio strategy and product roadmap. The market’s evolution favors players who can differentiate on comfort, safety, and sustainability. Product teams can use the report’s consumer insights and performance benchmarking to set innovation roadmaps that align with measurable consumer value drivers rather than anecdotal trends.
-
Supply chain and manufacturing decisions. Raw-material sourcing, contract-manufacturing choices, and facility footprint decisions are now subject to tighter regulatory scrutiny and rising quality expectations. The study maps supply chain choke points and supplier archetypes so procurement and operations can design resilient and compliant flows.
-
Regulatory and quality readiness. With changing medical-device classifications and quality standards, regulatory teams must move from reactive to strategic. Our analysis quantifies potential compliance costs and timelines under recent regulatory updates, enabling legal and QA leaders to build compliant rollout plans that minimize time-to-market disruption.
What the full report delivers — practical, executable content
-
Robust market sizing and forecast models. Historical tracking (2020–2025) and forward scenarios (2026–2032) built from bottom-up and top-down methods, stress-tested across price, volume, and substitution scenarios.
-
Segmentation frameworks (by product, material platform, and application). We provide a validated taxonomy, adoption curves and sensitivity analysis for each segment to guide targeted product development and channel strategies — the full report contains the granular split tables and unit-volume assumptions behind each segment forecast.
-
Competitive benchmarking and capability matrices. Detailed profiles and strategic positioning maps for incumbent brands and OEM/ODM players, including manufacturing footprints, private-label exposure, and innovation pipelines.
-
Commercial playbooks. Customer archetypes, pricing elasticity curves, promotional lift estimates, and recommended channel mixes for national brands, private-label, and direct-to-consumer models.
-
Regulatory impact analysis and compliance pathways. Practical checklists and a phased roadmap for aligning product development and QMS with the newest medical-device and quality-standard expectations.
-
Acquisition and partnership screening tools. Deal-scorecards and integration risk matrices to support M&A due diligence or strategic partnerships, enabling rapid identification of targets that close capability gaps.
Competitive landscape — who matters and why
The market’s competitive structure is moderately fragmented. The top three participants account for roughly 25% of market share, while the top five together concentrate just over a quarter, indicating meaningful opportunity for regional champions and downstream consolidation. This concentration profile suggests that scale matters for distribution and R&D economics, yet differentiated entrants can still carve defensible positions.
Key companies addressed in our study include major multinational brand owners, regional champions, and specialized OEM/ODM manufacturers. The following company summaries encapsulate strategic posture and the capabilities that matter to 2026 decision-making:
-
Kimberly‑Clark Corporation (Irving, TX) — a global consumer hygiene behemoth with a portfolio approach that leverages brand equity, partnerships for social impact, and scale manufacturing. Recent moves underscore a stronger emphasis on global community health partnerships and distribution durability.
-
Unicharm Corporation (Ehime, Japan) — focused on advanced R&D in feminine care with regional leadership in several Asian markets. Strategic alliances with peers increase channel breadth and cross‑brand technology sharing.
-
Kao Corporation (Tokyo, Japan) — invests heavily in product-technology differentiation, recently launching enhancements that improve user comfort and breathability. Kao’s approach demonstrates the margin potential of premium features supported by consumer communication.
-
Hengan International Group (Jiangxi, China) — a regional powerhouse with strong manufacturing scale and multiple consumer brands, well-positioned to serve both mass and value segments through portfolio segmentation.
-
Family Cares Group (Fujian, China) — an increasingly relevant manufacturer with certified quality systems and registered establishments that facilitate exports and entry into regulated markets.
-
Premier Care Industries (Winnipeg, Canada) — an established contract manufacturer offering private-label and national-equivalent product lines, critical for retailers and international brands pursuing low-risk market tests.
-
Ontex Group NV (Aalst, Belgium) — a manufacturer and brand owner focused on flexible go-to-market models, including private-label partnerships and geographic diversification.
-
Haoyue Personal Care (Hangzhou, China) — an OEM/ODM specialist that is representative of modern contract-manufacturing capabilities in the region, providing rapid product development and scale services to both domestic and export clients.
Regulatory, standards and quality dynamics shaping 2026
Regulation is a material strategic force in this market. Recent and near-term developments that executives must account for include:
-
In October 2025, the U.S. Food and Drug Administration issued draft guidance that classifies sanitary napkins as Class II medical devices and lays out expectations for performance testing and labeling. This raises the bar for product validation and claims substantiation in the U.S. market.
-
Effective February 2, 2026, the FDA’s Quality Management System Regulation (QMSR) incorporated ISO 13485:2016 concepts into 21 CFR Part 820. Manufacturers and contract partners must reconcile existing QMS practices with these updated requirements to certify market readiness.
-
On the standards front, the ISO/TC 338 committee is developing global standards for single-use menstrual pads, with completion expected in late 2026. This will harmonize test methods and safety expectations across major markets and affect both product design and labelling.
Strategic priorities and recommended next moves for 2026
-
Immediate compliance triage. Companies selling into regulated markets should prioritize gap assessments against ISO 13485-aligned QMS and plan for performance testing aligned to recent FDA guidance. The cost and lead time to adapt should be budgeted as an operational priority for 2026.
-
Product differentiation that scales. Invest in one or two innovation platforms (comfort, absorption performance, sustainability) and validate through small-batch rollouts or private-label partnerships before national launches.
-
Supply‑chain resilience and nearshoring options. Re-evaluate supplier portfolios and contract-manufacturing relationships to reduce single-source exposure and ensure rapid regulatory documentation flow between manufacturer and brand.
-
M&A and partnership scouting. Use the report’s deal-scorecard to screen targets that add regulatory-ready manufacturing, differentiated materials capability, or faster access to high-growth channels.
-
Consumer-centric evidence strategies. As regulatory expectations rise for performance claims, align clinical/consumer testing plans with product claims and labeling to de-risk marketing spend.
How to use the full report
The full PW Consulting report is designed as an operational toolkit for leadership teams: finance, R&D, regulatory, supply-chain, commercial, and M&A. If you are prioritizing capital deployment, launching a new product line, negotiating private-label contracts, or aligning quality management to new regulatory norms, the report provides the quantitative detail and executable playbooks to move from strategy to implementation.
Note: this briefing emphasizes high-level dynamics and actionable themes. To access detailed segment share tables, region-by-application models, supplier-specific cost curves, and the proprietary valuation templates we used to test scenarios, please consult the full study.
Next step
For teams ready to translate growth opportunity into a prioritized 90–180 day plan for 2026, PW Consulting offers a tailored deep-dive workshop that maps the report’s findings to your balance-sheet, regulatory posture, and go-to-market capabilities. Contact our advisory team to schedule a briefing and obtain the full dataset and model license.
For detailed analysis of this topic, please visit the official page: Sanitary Napkin for Feminine Care Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


