



PW Consulting: TCB Bonder Market Poised for 18.31% CAGR to 2032

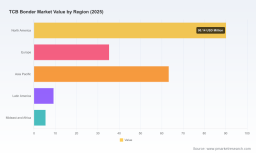
TCB Bonder Market: A 2026 Strategic Preview for Corporate Decision‑Makers
As PW Consulting’s senior strategy advisor and lead industry analyst, I present a concise, decision‑oriented preview of our TCB (thermo‑compression) bonder market research — designed to inform capital allocation, sourcing strategy, and product roadmaps in 2026. The market has expanded rapidly in recent years and remains one of the highest‑growth segments in advanced assembly equipment. Our analysis synthesizes a robust historical baseline (2020–2025), scenario‑based forecasts through 2032, and a pragmatic, execution‑focused toolkit you can operationalize this year. This preview demonstrates the depth of our work while deliberately withholding the granular regional and application splits to encourage direct engagement with the full report for actionable datasets and supplier scorecards.
TCB Bonder Market
Why this study is strategically valuable in 2026
-
Market clarity for capital planning: The TCB bonder market is growing from a modest base into a multi‑hundred‑million USD industry. Between 2020 and 2025 the market more than doubled and our forecast shows sustained expansion through 2032 at a compounded annual growth rate (CAGR) of approximately 18.3%. That pace materially changes capex timing, recovery horizons, and supplier investment decisions.
TCB Bonder Market -
Technology inflection and competitive advantage: Thermo‑compression bonding is converging with other advanced interconnect techniques (hybrid bonding, ultra‑fine pitch flip‑chip) and is now a critical enabler for HBM, CoWoS, and heterogeneous integration strategies. Knowing which platform architectures and automation features will scale in high‑volume environments is essential for equipment buyers and semiconductor integrators.
TCB Bonder Market -
Risk‑adjusted supplier selection: Market concentration metrics indicate a moderately concentrated supplier ecosystem (top‑3 and top‑5 concentration indicators are included in the report). Combined with supplier roadmaps and reliability datasets, this allows procurement teams to design robust multi‑vendor sourcing strategies with contingency capacity and quality controls.
-
Regulatory and premium‑segment considerations: Certain end‑markets — notably medical device manufacturing — impose regulatory and traceability requirements that translate to higher system specifications and pricing. Understanding the operational and certification burdens of these niches is crucial when evaluating ROI for medical‑grade systems.
What the full report delivers (practical, action‑oriented content)
-
Comprehensive market sizing and forecast model (2020–2032) in USD Million, with scenario sensitivity and upside cases for accelerated AI/compute adoption.
-
Technology deep dives — platform architectures, thermal and pressure control regimes, cycle‑time tradeoffs, and precision placement tolerances — with implications for yield, throughput, and process stability.
-
Procurement and CAPEX playbook — TCO models, depreciation timelines, spare‑parts planning, installation footprints, and operator skill profiles required to achieve targeted yields.
-
Supplier scorecards and RFP templates — objective leading indicators for vendor selection (uptime, service coverage, qualification timelines, upgrade paths), plus red‑flag checklists for vendor claims.
-
Buyer’s validation plan — factory acceptance testing (FAT) checklists, sample qualification protocols, and inline metrology integration guides to accelerate ramp.
-
Regulatory compliance annex — requirements and recommended evidence packages for medical‑grade production (facility class requirements, lot traceability, documentation milestones) and associated cost implications.
-
M&A and strategic partnership playbook — valuation drivers, integration risks, and partnership archetypes for equipment manufacturers, materials suppliers, and high‑volume assemblers.
Market dynamics and growth drivers—what is really moving the needle
-
Advanced packaging demand: The push for higher interconnect density and lower latency across AI accelerators and high‑performance compute is the primary demand engine. Thermo‑compression bonders are well positioned where heat‑and‑pressure control are required for robust metal‑to‑metal interconnects at fine pitches.
-
Process scaling and automation: Lower cycle times and sub‑micron placement accuracy are becoming table stakes for high‑volume fabs and OSATs. Systems that combine precise thermal control with fast, repeatable mechanics shorten qualification windows and reduce per‑unit cost at scale.
-
Premium niches requiring traceability: Medical and certain aerospace applications impose facility, documentation, and traceability standards that favor suppliers who can support Class II/III device production and full material lot traceability. These requirements justify premium system pricing and longer supplier qualification cycles.
-
Supply‑chain resilience and concentrated vendor landscape: The supplier landscape demonstrates moderate concentration at the top. This creates opportunities for strategic partnerships but also raises the importance of supply continuity planning and multi‑sourcing in procurement strategies.
Competitive landscape — companies to benchmark and why
-
Kulicke & Soffa Industries, Inc. (Willow Grove, PA, USA — https://www.kns.com/): Strength lies in high‑precision thermo‑compression platforms (APAMA™ PLUS series) that emphasize precise heat‑and‑pressure control for ultra‑fine pitch interconnects. Their positioning is attractive to customers prioritizing process control and integration with existing assembly lines.
-
ASMPT Amicra (Singapore — https://www.asmpt.com/): Known for die attach systems optimized for high throughput, their NOVA Pro line delivers tight placement tolerances and cycle‑time performance aimed at high‑volume TCB production. They are a logical choice where throughput and scalability trump niche regulatory requirements.
-
BE Semiconductor Industries (BESI) (Duiven, Netherlands — https://www.besi.com/): A leader with established deployments for flip‑chip and die bonding at scale, BESI’s systems are often evaluated for advanced packaging roadmaps such as CoWoS and HBM integration. They score well on proven field reliability and process maturity.
-
Toray Engineering (Japan — https://www.toray-eng.com/): Offers bonders that support a wide set of bonding modalities (TCB, DAF, hybrid). Their capability to handle larger panel sizes positions them for novel applications beyond traditional wafer sizes and for players experimenting with large‑panel integration.
-
Palomar Technologies (Carlsbad, CA, USA — https://www.palomartechnologies.com/): Focused on ultra‑precise applications where process documentation and small‑lot quality are paramount (medical devices, photonics). Their platforms prioritize accuracy and process traceability over raw throughput.
Strategic implications for vendors, OEMs and investors
-
For equipment vendors: Prioritize modular architectures that enable both high‑throughput lines and medical‑grade traceability. Invest in service networks and predictive maintenance to differentiate in a market where uptime is a high‑order concern.
-
For OEMs and OSATs: Time capex to forecasted demand inflection points — misaligned investments can lead to underutilized assets or lost qualification windows. Use our scenario models to stress‑test capacity under varying AI and medical adoption curves.
-
For strategic investors and M&A teams: Look for targets that fill capability gaps (e.g., automation software, inline metrology, or medical‑grade traceability features) rather than purely adding volume. Integration risk is lower when acquisition targets provide complementary capabilities aligned to client roadmaps.
Actionable next steps for 2026 planning
-
Run a supplier qualification pilot: Shortlist two suppliers with different value propositions (throughput vs. traceability) and run 90‑day pilot lines to validate cycle time, yield, and service responsiveness under real production loads.
-
Integrate regulatory readiness into procurement: If pursuing medical or similarly regulated markets, require vendor evidence of facility qualification support and end‑to‑end lot traceability as part of the RFP.
-
Adopt a staged capex approach: Stage purchases to align with demonstrated demand inflection points rather than forecasting alone; maintain options for retrofit/upgrades to avoid technology obsolescence.
-
Build cross‑functional scorecards: Combine technical performance, commercial terms, and service readiness into a single decision matrix to reduce bias in vendor selection.
Our full TCB Bonder Market report contains the granular datasets, regional and application splits, detailed supplier scorecards, and downloadable financial models necessary to execute on the actions above. It also includes the full methodology, raw assumptions, and scenario tables that underlie the headline CAGR and multi‑year revenue forecast summarized here.
To access the complete study — including the withheld regional/application breakdowns and vendor market shares required for procurement RFPs, M&A diligence, and board‑level presentations — visit the PW Consulting publication page or contact our research team directly. The right data, combined with pragmatic execution playbooks, will be the difference between leading the 2026 TCB transition and merely responding to it.
For detailed analysis of this topic, please visit the official page: TCB Bonder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


