



PW Consulting: POCT Market Set to Grow at 8.5% CAGR Through 2032

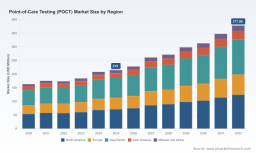
Point-of-Care Testing (POCT) Market: Strategic Briefing for 2026 Decision-Makers
Executive summary
The Point-of-Care Testing (POCT) market is moving from episodic disruption into structural expansion. Our industry model—anchored on a 2025 base year—shows the market recovering and accelerating after pandemic-driven volatility: rising from an observed level in 2020 to a reported market size of USD 215.0 million in 2025, and tracking to a materially larger market through our 2026–2032 forecast horizon at a compound annual growth rate (CAGR) of 8.5%. This trajectory masks important inflection points that will determine winners and losers in 2026 and beyond.
Point-of-Care Testing (POCT) Market
As PW Consulting’s lead analysis for the POCT study, this briefing highlights the research’s strategic value for corporate leaders, investors, and policy teams preparing plans for 2026. The goal is to demonstrate the report’s depth—market architecture, competitive positioning, regulatory inflection analysis, and executable commercial playbooks—while preserving selective data granularity to motivate direct access to the full report for transaction- and deployment-level decisions.
Point-of-Care Testing (POCT) Market
Why 2026 is a pivotal planning year
-
Regulatory re-baselining: Full implementation of CLIA regulatory updates in early 2025 tightened proficiency testing and elevated performance expectations for POCT analytes. These rules materially raise the bar for simple-to-use claims and CLIA-waiver pathways, making 2026 the first full planning year when operating models, QA frameworks, and reimbursement applications must align with the new regime.
Point-of-Care Testing (POCT) Market -
Technology consolidation and product refresh: Incumbents and fast-scaling challengers are converging on modular, multi-marker platforms that blur the lines between point-of-care convenience and laboratory-grade performance. Recent regulatory actions and strategic moves—such as FDA clearance events and platform consolidation activity—are pushing the market toward larger integrated systems and bundled consumable economics.
-
Channel evolution and care-site decentralization: The shift toward home and near-patient diagnostics continues, but not uniformly. Hospitals, physician offices, and home self-testing channels each have unique operational, procurement, and reimbursement dynamics that require distinct commercialization tactics in 2026.
What the PW Consulting POCT report delivers (practical, action-oriented)
-
Robust market-sizing and scenario architecture: Transparent methodology covering historical (2020–2025) reconciliation and three forecast scenarios (conservative, base, aggressive) for 2026–2032, with sensitivity to adoption, reimbursement, and regulatory pathways.
-
Commercial playbooks: Channel-specific GTM strategies (hospital procurement, outpatient clinics, and direct-to-consumer launches), pricing and bundling heuristics, supplier negotiation templates, and sample P&L impacts for installation, service, and consumables models.
-
Technology and product roadmaps: Comparative technology maturity curves for molecular, immunoassay, blood-gas/cardiac, and glucose-monitoring approaches; guidance on platform modularity, consumable dependency, and upgrade paths to maximize lifetime customer value.
-
Regulatory and reimbursement playbooks: Step-by-step CLIA alignment checklists, clinical validation design recommendations given tighter proficiency windows, and payer engagement strategies prioritized by value drivers for 2026 coverage decisions.
-
Competitive due diligence toolkits: Supplier scorecards, integration risk matrices, and acquisition screening criteria to support M&A or partnership diligence without reliance on vendor-disclosed market shares.
-
Customizable decision-support models: Build-your-own dashboards for scenario-testing CAPEX, consumable attach rates, and channel mix—designed to produce board-ready ROI projections for 2026 investment approvals.
Competitive landscape: who matters and why
The POCT competitive landscape is shaped by a mix of large diagnostics incumbents, diversified life-science OEMs, and rapid-response platform players. Market concentration metrics indicate a moderate-to-high level of consolidation at the top, with a small group of leaders commanding a substantial share of global value—creating both barriers and partnership opportunities.
-
Abbott Laboratories: A broad POCT portfolio anchored by compact, high-precision platforms spanning cardiac, metabolic and rapid molecular testing. Strengths: deep installed base, clinical validation scale, and consumable economics—critical for sustaining recurring revenue in mature channels.
-
F. Hoffmann‑La Roche Ltd: Focused on rapid molecular multiplexes enabling clinic-level multi-target testing. Strategic advantage: leveraging laboratory credentials to accelerate CLIA-eligible multi-analyte panels into point-of-care sites.
-
Siemens Healthineers: Strengths in integrated solutions for blood-gas, cardiac care, and high-throughput near-patient testing. Their trajectory is to push lab capabilities closer to the bedside through automation and connectivity.
-
Danaher Corporation: Platform-centric approach with molecular and immunoassay capabilities, emphasizing integrated workflows and assay breadth—an attractive profile for large healthcare systems seeking vendor consolidation.
-
QuidelOrtho and BD: Focused on agile immunoassay and rapid molecular offerings with strong channel partnerships to accelerate distribution in outpatient and urgent-care networks. Active M&A and product rationalization moves are reshaping their near-term competitive posture.
-
bioMérieux and Thermo Fisher Scientific: Differentiated by infection-diagnostics depth and laboratory-to-point-of-care translation expertise—positions that matter as multiplex infectious-disease testing expands into non-traditional settings.
Recent market events sharpen the competitive calculus. A notable CLIA-waiver clearance for a multiplex STI panel and FDA 510(k) transitions for point-of-care COVID-19 diagnostics have immediate implications for platform claims, reimbursement conversations, and procurement timelines. Strategic acquisitions and product discontinuations by several players signal portfolio pruning and refocus on high-growth POCT segments.
Key market dynamics shaping strategy in 2026
-
Performance vs. simplicity trade-off: Providers demand lab-grade accuracy but effective workflows and low operator burden. Winning products reconcile these needs through automation and simplified QA without sacrificing clinical confidence.
-
Consumables-first economics: Recurring revenue from cartridges, reagents, and calibration systems drives valuation multiples. Strategic pricing and contract models for consumables are as important as instrument sales.
-
Interoperability and data services: Connectivity, EMR integration, and result analytics are differentiators for large health-system deals; bundled SaaS and outcome reporting will be negotiation levers in 2026.
-
Regulatory and proficiency pressures: Tighter CLIA windows and proficiency expectations increase validation costs and elongate time-to-market for new assays, favoring vendors with larger R&D and regulatory infrastructures.
Strategic implications and recommended actions for 2026
-
For platform incumbents: Prioritize consumable stewardship and lifecycle upgrade pathways, accelerate CLIA alignment workstreams, and move to subscription or outcome-linked contracts where possible to lock in recurring revenue.
-
For fast-follow entrants: Focus on niche, under-served use cases with clear clinical utility and lower regulatory barriers; partner with established distribution networks to shorten commercialization timelines for 2026.
-
For healthcare systems: Re-evaluate procurement frameworks to include interoperability, QA management costs, and total cost of ownership over multiple years—avoid one-time instrument price comparisons.
-
For investors and M&A teams: Look for targets with proprietary consumable economics, protected clinical claims, and demonstrated connectivity adoption—these attributes materially affect exit multiples in the sector.
Scenario framing for board-level decisions
Our report models three plausibly differentiated outcomes for 2026–2032 tied to adoption, reimbursement, and regulatory shocks. The base case—supported by the historical trajectory and our CAGR assumptions—anticipates steady expansion. Upside scenarios depend on expedited reimbursement for multi-analyte panels and rapid adoption of decentralized care pathways; downside scenarios reflect stricter CLIA enforcement or reimbursement stagnation. Decision-makers should stress-test capex and partnership plans against all three outcomes before committing resources in 2026.
How PW Consulting supports execution
-
Custom market-entry and channel scaling plans for 2026, including pilot designs, clinical validation protocols, and staged rollouts to balance speed and risk.
-
M&A and partnership advisory: target screening, commercial and regulatory due diligence, and post-merger integration planning focused on consumable synergies and channel consolidation.
-
Regulatory coaching and validation program design aligned to the new CLIA expectations—reducing time-to-CLIA-viable claims while controlling validation spend.
-
Commercial negotiation and contracting playbooks tuned to 2026 reimbursement realities and hospital procurement cycles.
Concluding note: the value of an actionable, data-driven POCT playbook
POCT is no longer a niche adjunct to central laboratories; it is a strategic lever to reconfigure diagnostic pathways, reduce time-to-treatment, and unlock new revenue frameworks across care settings. Our POCT market study combines granular historical reconciliation (2020–2025), a modeled baseline for 2026 planning, and scenario-based forecasts to 2032—providing the strategic inputs necessary to prioritize investments, redesign go-to-market approaches, and negotiate partnerships with confidence.
To access the complete dataset, segmentation-level outputs, and the executable templates that translate these insights into approved 2026 budgets and go-to-market plans, consult the full PW Consulting POCT report on our website. The report contains the exact sub-segment and regional breakdowns required for transaction-level decisions—reserved for subscribers and licensed clients.
For detailed analysis of this topic, please visit the official page: Point-of-Care Testing (POCT) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


