



PW Consulting: L-Carnitine Market to Hit USD 307.8M by 2032 at 5.2% CAGR

L-Carnitine Market 2026 Outlook: Strategic Imperatives for Decision-Makers
As PW Consulting’s lead industry analyst, I present an executive preview of our L-Carnitine Market study designed to orient corporate boards, strategy teams, and investors preparing for decisive actions in 2026. This preview synthesizes macro dynamics, regulatory shocks, supply-chain realities, and competitive positioning into a set of practical implications—while intentionally reserving the full, granular segmentation and proprietary models for subscribers to the complete report.
L-Carnitine Market
Market Snapshot: Trajectory and Structural Characteristics
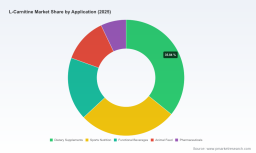
After a period of steady expansion through the early 2020s, the L-Carnitine market reached an estimated USD 216.4 Million in our 2025 base year. Our forecast model—constructed on historical performance, demand drivers across human nutrition, sports nutrition, functional beverages, pharmaceuticals and animal feed, and expected regulatory shifts—projects a mid-single-digit trajectory through the forecast window. Specifically, the market is expected to grow at a compound annual growth rate (CAGR) of 5.2% beginning in 2026, reaching approximately USD 307.8 Million by 2032.
L-Carnitine Market
Two structural features define the market’s strategic landscape. First, despite clear pockets of higher-value demand (e.g., pharmaceutical-grade and clinical nutrition applications), the overall market concentration remains modest: the three largest players account for roughly a quarter of total sales, while the top five account for just under a third. This fragmentation creates both opportunity and risk: scale advantages exist, but nimble and quality-focused incumbents can still capture premium niches.
L-Carnitine Market
Why This Matters for 2026 Decisions
- Capital allocation and capacity planning: With a predictable, mid-single-digit growth profile, capital investments must be justified by margin accretion or strategic market share gains rather than by sheer volume growth. Investors and C-suite leaders should prioritize capacity enhancements that deliver cost efficiency (fermentation yields, downstream purification) and regulatory compliance rather than broad-based expansion.
- Regulatory readiness as a competitive moat: Recent regulatory activity has tightened the compliance baseline, elevating the value of documented safety verification and residue controls. Companies lacking robust compliance infrastructure risk market access constraints in key jurisdictions and pricing pressure from buyers requiring certified suppliers.
- Supply-chain resilience: L-Carnitine synthesis is resource- and process-intensive. Raw material cost volatility and process sensitivity mean that firms with secured feedstock contracts, diversified synthesis routes (chemical vs. fermentation), and flexible COGS models will outperform peers during market stress.
Regulatory and Industry Shocks—Implications and Strategic Responses
Three regulatory and market events crystallize the current risk set. The renewal of scientific opinion for certain feed additive authorizations has preserved critical market channels for compliant suppliers. Meanwhile, new maximum residue level regulations enacted in early 2026 increase the compliance burden on exporters and elevate verification costs. Finally, continued FDA recognition of L-Carnitine’s therapeutic uses in specific indications underscores an enduring clinical market that demands pharmaceutical-grade production and documentation.
Strategic responses for 2026 should center on: (a) prioritizing regulatory certification initiatives that unblock high-margin channels, (b) investing in traceability and analytical capability to meet tightened residue and safety standards, and (c) re-evaluating supplier contracts in light of potential customs or market access frictions. These moves protect revenue and open opportunities for premium positioning.
Competitive Landscape: Who Matters and Why
The competitive map is populated by established global suppliers and specialized regional producers. Key players include Lonza Ltd. (Carnipure® brand), seasoned European API and feed manufacturers, prominent Chinese volumes suppliers, and fine-chemical distributors that serve research and specialty applications. Each archetype implies distinct strategic postures:
- Global integrated manufacturers (example: Lonza Ltd.): These firms leverage brand-recognized quality, global regulatory footprints, and backward integration. Their strategic focus in 2026 will be to protect feed additive authorizations, strengthen supply agreements with large nutraceutical and pharmaceutical customers, and monetize premium grades.
- Regional API and feed specialists (examples include several established European and Chinese manufacturers): Cost and proximity advantages enable competitiveness on price and service. Their success will hinge on adapting to new residue limits and investing selectively in certification to retain export access.
- Fine-chemical and reagent suppliers (research-focused distributors): These players capture R&D and specialty demand. Their growth is correlated with innovation in nutraceutical formulations and laboratory usage patterns rather than mass-market feed demand.
For strategists, the competitive implication is clear: scale matters for cost leadership and access to regulated channels, but differentiated quality credentials and customer intimacy enable margin capture in premium segments. A hybrid approach—combining manufacturing alliances with targeted investments in compliance and quality—often delivers the best risk-adjusted returns.
Operational Playbook: What the Full Report Delivers
Our complete L-Carnitine Market study is structured as an operational toolkit for 2026 decision-making. Highlights include:
- Proprietary demand models by application and type, allowing scenario analysis across regulatory, price, and adoption pathways.
- Risk-mapped supplier scorecards that evaluate process routes, quality certifications, and export readiness—designed for sourcing teams assessing new partners or potential acquisitions.
- Regulatory impact matrices to quantify time-to-market and compliance cost implications of recent and pending rules in major trading blocs.
- Commercial playbooks for premiumization, channel segmentation, and co-development partnerships with downstream formulators.
- M&A screening templates that filter targets by strategic fit, compliance posture, and scale synergies.
These deliverables are actionable, not just descriptive: they are calibrated to support 90–180 day program planning for procurement, regulatory affairs, and corporate development teams entering 2026.
Key Strategic Recommendations for 2026
- Prioritize compliance investments that unlock high-value channels. The cost of certification is an investment in market access and price premium—treat certification spend like a near-term CapEx with multi-year payback assumptions.
- Diversify synthesis routes and feedstock contracts. Firms should stress-test their operations against raw-material price shocks and consider dual-process capabilities (fermentation plus chemical pathways) to preserve margin under price swings.
- Target selectively for M&A or JV activity. Given market fragmentation, bolt-on acquisitions that add compliance credentials, niche product lines, or regional market access can be highly accretive without requiring disruptive scale plays.
- Embed regulatory scenario planning into commercial forecasts. Update sales projections to reflect plausible shifts in residue limits and authorization windows; align inventory and pricing policies to mitigate margin whipsaw effects.
What We Are Watching—Leading Indicators for the Next 12 Months
- Regulatory pronouncements and enforcement guidance from major authorities; these can shift certification timelines and compliance costs materially.
- Raw-material spot and contract price trends tied to fermentation inputs and chemical precursors; persistent volatility will favor integrated players and those with hedging strategies.
- Product launches in clinical nutrition and specialty pharma that expand demand for pharmaceutical-grade supplies.
- Commercial consolidation moves and supplier alliances that could alter distribution economics and bargaining power across the value chain.
Conclusion: How PW Consulting Helps Executives Convert Insight Into Action
For boards and strategy teams preparing budgets and M&A pipelines in 2026, the L-Carnitine market offers steady growth but with concentrated regulatory and supply risks. Our full report equips decision-makers with the granular segmentation, scenario models, supplier scorecards, and playbooks required to convert market insight into defensible, high-conviction actions. It is tailored to support investment committees, procurement leaders, and corporate development teams looking to prioritize initiatives that enhance margin, secure access to regulated channels, and manage supply volatility.
To access the full dataset, segmentation tables, and proprietary models referenced in this preview, please consult the PW Consulting L-Carnitine Market report landing page. The detailed annexes contain the regional and application-level splits, shipment and pricing forecasts, and downloadable supplier dossiers that underpin the strategic recommendations summarized here.
For detailed analysis of this topic, please visit the official page: L-Carnitine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


