



PW Consulting: Ribbon Fiber Cable Market to Reach USD 4.74B by 2032 — 8.9% CAGR (2026–2032)

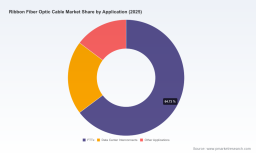
Ribbon Fiber Optic Cable Market — Strategic Intelligence Briefing for 2026 Decision-Makers
Executive snapshot
The Ribbon Fiber Optic Cable market is entering a phase of strategic acceleration. After steady expansion through the early 2020s, the market reached an estimated USD 2.58 Billion in the base year (2025) and is projected to grow to approximately USD 4.74 Billion by 2032. PW Consulting’s forecast models, calibrated to a 2026–2032 horizon, indicate a compound annual growth rate (CAGR) of roughly 8.9% across that period. The near-term projection for 2026 shows continued expansion from the 2025 base, reflecting a confluence of demand drivers and technology maturation that will shape procurement, manufacturing, and network design decisions this year.
Ribbon Fiber Optic Cable Market
Why this matters for boardrooms and strategy teams in 2026
Ribbon fiber technologies — including rollable ribbon, intermittently bonded ribbon (IBR), and high-fiber-count ribbon constructs — are no longer experimental elements reserved for hyperscale players. They are instrumental to three convergent industry trends that executives must account for in 2026 planning cycles:
Ribbon Fiber Optic Cable Market
- Density-driven cost economics: Higher-count ribbon solutions materially reduce conduit and pathway overheads, compressing outside-plant (OSP) footprint and lowering per-fiber installation costs when deployments are executed at scale.
- Operational velocity: Rollable and gel-free ribbon designs accelerate splicing and connectorization in dense environments, translating into time-to-service improvements that matter in competitive broadband and data center bids.
- Policy and sourcing dynamics: Growing emphasis on digital-inclusion funding and data-sovereignty requirements is shifting procurement toward more localized production and assembly footprints — a core consideration for capitalization and supplier selection strategies.
Key market dynamics shaping 2026 decisions
- Supply-chain pressure and material-cost shocks. Bend-insensitive G.657A2 fiber pricing climbed sharply into early 2026, creating immediate cost implications for procurement and margin models. Tactical hedges and long-lead sourcing agreements are already being used to manage exposure.
- Regulatory adaptations. Trade and procurement rules in major markets have pushed several operators and OEMs to relocate final assembly closer to end-markets to comply with domestic-content policies. Tariff impacts have been attenuated by these shifts, but compliance and certification timelines are now material inputs for rollout schedules.
- Technology and interoperability convergence. Innovations such as rollable ribbon and Spider Web Ribbon designs have unlocked extreme-density solutions; however, interoperability (closures, splicing machines, and patching architectures) remains a gating factor for rapid adoption at scale.
- Consolidation pressure without monopoly risk. Market concentration metrics show meaningful scale among top vendors while leaving substantial headroom for specialty players and regional champions — a dynamic that sustains competitive tension and strategic opportunity.
What the full PW Consulting study delivers (practical, action-oriented content)
The full report is structured as a decision-support toolkit for commercial, procurement, and engineering leaders. Highlights include:
Ribbon Fiber Optic Cable Market
- Repeatable deployment economics — cost-to-deploy models (OSP and data-center scenarios) that allow users to stress-test outcomes under material-price and labor scenarios.
- Supply-chain heatmaps — capacity and lead-time overlays for fiber preform, coating, ribbon assembly, and cable finishing across manufacturing nodes.
- Technology playbook — technology readiness assessments, interoperability checklists, and deployment recipes for rollable ribbon, intermittently bonded ribbon, and spider-web ribbon architectures.
- Vendor-agnostic procurement templates — RFx language, long-term contract clauses, and inventory buffers tuned for 2026 market conditions.
- Competitive archetypes and M&A playbooks — value-creation pathways for acquirers, including bolt-on targets, integration risks, and expected synergies.
- Regulatory scenario analysis — line items that quantify the commercial impact of domestic-content rules, tariffs, and funding-program strings for major markets.
Note: To preserve the value of our primary-analysis work and as part of this “preview” briefing, detailed segment-level breakouts and region/application-specific revenue tables are available only in the full publication.
Competitive landscape — who matters and why
The market is populated by a mix of global platform firms, national champions, and specialized innovators. A brief, non-exhaustive synthesis of strategic positions:
- Corning Incorporated — commercial leadership in ultra-high-density ribbon with gel-free and RocketRibbon® solutions oriented at high-density data centers and OSP projects. Their designs emphasize smaller outer diameters and reduced installation time, a clear operational value-proposition for large-scale builds.
- Prysmian Group — differentiated by FlexRibbon® IBR technology that optimizes fiber density for microduct and rollable formats. Prysmian’s product positioning targets flexible handling and flame-rated options favored in constrained urban ducts.
- Furukawa Electric — aggressive high-density rollable ribbon designs that target underground and hyperscale transport corridors. Their emphasis on minimal diameters addresses both space and cost constraints.
- Fujikura Ltd. — pushing scale with massive-fiber-count constructs (notably Spider Web Ribbon and wrapping-tube architectures), and recently recognized by industry awards for hyperscale applicability — an important signal to hyperscalers and integrators.
- Sterlite Technologies and YOFC — players combining high-count ribbon options with regional manufacturing footprints, serving duct-heavy FTTH and enterprise rollouts with competitive delivery models.
- Nexans, CommScope, Optical Cable Corporation, Belden — complementary positions across patching, enterprise, tactical and industrial segments, each emphasizing integration with connectivity ecosystems.
Market concentration indicators point to a top-three share that suggests meaningful scale advantages for leading platform players while leaving near‑term opportunity for specialized vendors and systems integrators. This structure encourages both partnership-led strategies and selective consolidation.
Recent industry moves with strategic signal
- Interoperability partnerships (example: compatibility programs pairing closures with rollable ribbon products) indicate that the market is moving from proprietary prototypes toward ecosystem-compatible solutions — a positive signal for operators seeking risk mitigation in deployments.
- Recognition of ultra-high-count architectures in industry awards underscores the readiness of these technologies for hyperscale applications — influencing procurement specifications and vendor shortlists.
Immediate strategic recommendations for 2026
Based on our integrated demand-supply, technology-readiness, and regulatory scenario engines, PW Consulting recommends executive teams prioritize the following actions in 2026:
- Secure staged procurement agreements for bend-insensitive fiber and ribbon assemblies with indexed pricing to guard against material-price volatility.
- Invest in or partner for regional assembly to comply with domestic-content rules and reduce logistics lead times for funded broadband programs.
- Standardize interoperability requirements across internal engineering, procurement, and field operations to accelerate vendor qualification and reduce integration risk.
- Run rapid pilot deployments of rollable/high-density ribbon in targeted corridors to validate splicing, handling, and serviceability assumptions before broader rollouts.
- Consider tactical M&A to acquire rollable-ribbon IP or specialized manufacturing capacity that can be integrated with broader cable portfolios to capture incremental share.
- Embed scenario-based pricing and rollout contingency plans into commercial bids to protect margins in the face of further material-cost escalation.
Risks and mitigations
- Material-price inflation — mitigate by multiple-sourcing, index-linked supply contracts, and hedging where feasible.
- Standards fragmentation — engage in industry consortia and interoperability pilots; prefer vendors demonstrating cross-closure and tool compatibility.
- Regulatory shifts and funding timing — align project timelines to funding windows and design procurement flexibility into contracts to absorb policy changes.
- Overcapacity risk — stagger capacity expansion and use tolling/contract manufacturing to avoid stranded assets if demand timing slips.
How PW Consulting’s full study supports executable 2026 plans
The complete report converts the strategic narrative above into operational deliverables: an interactive model that lets you stress-test capex and opex under multiple market conditions; vendor scorecards with supplier capabilities, certifications and risk profiles; field-proven installation playbooks; and a procurement toolkit tailored to regulatory constraints in major buying jurisdictions. Our primary research inputs include interviews with manufacturers, network operators, and systems integrators, plus proprietary costing and capacity datasets that underlie the forecast.
For executives making resource allocation and go-to-market choices in 2026, this market is no longer a niche engineering problem — it is a strategic supply-chain and product-portfolio battleground. PW Consulting’s Ribbon Fiber Optic Cable Market study is designed to convert those engineering choices into defensible commercial outcomes.
Next steps
To access the full dataset, segment-level revenue tables, company scorecards, and the decision-support model, please consult the full PW Consulting publication. The detailed breakouts and downloadable tools are reserved for subscribers and project clients to preserve the integrity of the analysis and to enable actionable, differentiated strategies.
For detailed analysis of this topic, please visit the official page: Ribbon Fiber Optic Cable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


