



PW Consulting: Greenhouse Soil Market — Greenhouse segment at USD 1,482.48M (2025)

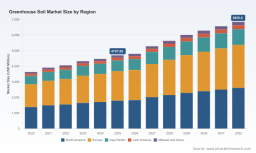
Greenhouse Soil Market 2026: Strategic Preview for Executive Decision-Makers
As the greenhouse sector tightens its focus on productivity, sustainability and supply-chain resilience, the greenhouse soil market is quietly reshaping the economics of protected-culture horticulture. PW Consulting’s Greenhouse Soil Market study — with a 2025 base and a 2026–2032 forecast horizon — synthesizes the signals senior leaders need to align portfolios, capital plans and go-to-market strategies for 2026. At a high level: the market reached approximately USD 4,707 million in 2025 and is projected to expand to roughly USD 6,857 million by 2032, reflecting a mid-single-digit compound annual growth rate (CAGR) of about 5.5% through the forecast window.
Greenhouse Soil Market
Why 2026 Is a Strategic Inflection Point
-
Regulatory acceleration: Recent policy moves in key markets (including comprehensive peat restrictions and progressive peat-reduction mandates) are compressing timelines for reformulation and supplier qualification. For many growers and suppliers, 2026 will be the year to operationalize alternative-substrate strategies rather than pilot them.
Greenhouse Soil Market -
Cost and input pressure: Rising fuel, transport and upstream raw-material costs since 2023 have changed the calculus of sourcing and mix formulation. Buyers who lock optimized logistics and hedge supplier concentration now will gain enduring margin advantages.
Greenhouse Soil Market -
Capitalization window: With multiple large incumbents and influential regional specialists maintaining fragmented market positions (CR3 ~25%, CR5 ~28%), the market remains attractive for targeted consolidation, bolt-on acquisitions and distributor partnerships through 2026–2028.
Macro Signals and What They Mean for 2026 Planning
-
Demand durability: Historic growth from 2020 to 2025 demonstrates steady, structural expansion in greenhouse-related substrates. That trajectory underpins near-term capacity investments and justifies continued R&D spend on high-performing alternative substrates.
-
Sustainability as commercial imperative: Policy drivers (peat bans, peat-reduction mandates and peatland protections) plus incentive programs for climate-smart agriculture are elevating sustainability from compliance cost to commercial differentiator. Expect 2026 procurement RFQs to include carbon and biodiversity performance clauses.
-
Product differentiation: As commoditization pressures mount, value will accrue to mixes delivering repeatable crop outcomes (e.g., water retention, root-zone oxygenation) and to suppliers offering integrated services — formulation, trials and grower advisory.
Competitive Landscape: Strategic Postures to Watch
The market topology blends global incumbents, large regional manufacturers and a host of niche organic and high-performance formulators. Notable players include Scotts Miracle-Gro Company (Marysville, Ohio), Sun Gro Horticulture (Vancouver), Klasmann-Deilmann (Geeste, Germany), Premier Tech (Rivière‑du‑Loup), FoxFarm, Michigan Peat Company, Espoma, Good Earth Horticulture, Florentaise and ASB Greenworld. These firms represent a mix of scale advantages, legacy peat portfolios and growing investments in alternative substrates.
-
Incumbent defense and portfolio pivoting: Large players are investing in blended portfolios that mix peat alternatives (wood fiber, coir, composts) with legacy materials while protecting key distribution channels.
-
Regional specialists and technical depth: Companies with localized manufacturing and tailored blends for climate and crop niches are monetizing trust with commercial growers by shortening qualification cycles and offering co-development services.
-
Channel and distribution moves: Recent distributor agreements and product launches indicate active channel engineering. For example, a 2025 master distribution agreement expanded availability of greenhouse substrates in the U.S., while late-2025 product introductions fused advanced fibre substrates with Canadian sphagnum peat to address performance and sustainability demands.
Operational and Commercial Playbook for 2026
Senior leaders should prioritize a set of pragmatic actions that balance short-term continuity with medium-term transformation.
-
Secure multi-tiered sourcing: Diversify raw-material sources across geography and substrate type to manage regulatory risk and feedstock scarcity. Executives should model inventory and transport scenarios to identify critical nodes where capacity or policy disruption would materially affect supply.
-
Commercialize sustainability claims with measurement: Move beyond marketing claims by embedding measurable metrics (carbon life-cycle, peat-content, biodiversity impact) into product specifications. These data points will be table stakes in 2026 procurement discussions and grant/supply programs tied to climate funding.
-
Invest in formulation and co-development: Allocate R&D and field-trial budgets towards mixes that replicate peat performance using alternatives. Co-development agreements with large greenhouse operators or co-ops can accelerate adoption and reduce grower switching costs.
-
Revisit channel economics and margins: With consolidation opportunities among distributors and increased direct-to-grower channels, reassess partner economics and invest selectively in digital commerce and logistics partnerships that reduce time-to-shelf.
-
Capture incentives: In markets where climate and agricultural programs provide funding for soil-carbon practices and sustainable inputs, align product roadmaps to qualify for subsidies and to unlock farm-level incentives that can accelerate sales.
Risk Scenarios and Contingent Responses
-
Policy shock scenario: Accelerated peat bans in additional jurisdictions would force abrupt reformulation and capacity shifts. Firms should maintain rapid-response teams to requalify mixes and preserve permit and certification timelines.
-
Logistics premium scenario: If transport and fuel costs spike further, localized manufacturing and just-in-time formulations will outperform long-distance supply models. Consider forward contracts for key inputs and near-market blending hubs.
-
Premium-demand scenario: A surge in indoor and urban horticulture could reallocate share towards premium, high-performance substrates. Plan to scale niche product lines without cannibalizing mainstream portfolio economics.
Research Scope: What the Full Report Provides
PW Consulting’s full study delivers the granular market intelligence your strategy team needs to operationalize the insights above. The report contains:
-
Detailed historical and forecast market sizing (base year 2025; 2026–2032 forecast) with demand drivers and sensitivity testing.
-
Comprehensive segmentation by product type, application and geographic region with volume and value models — enabling product-level margin and pricing simulations.
-
Supplier benchmarking, channel structure mapping and a searchable company matrix covering strategic profiles of the market’s leading producers and innovators.
-
Primary-sourced intelligence from grower trials, distributor interviews and procurement RFPs to ground-truth formulation performance and qualification timelines.
-
Scenario planning tools and actionable 12–18 month decision roadmaps for executives in procurement, product management and corporate development.
Note: This preview intentionally highlights strategic conclusions and is compatible with the “trailer” approach — the full report contains the granular regional, application and type splits, price models, and company-level revenue detail required to build financial or M&A models.
Implications for M&A, Partnerships and R&D in 2026
-
M&A targets: Look for bolt-on acquisitions with proprietary formulations, localized production footprints or customer lists in high-growth end-markets. The fragmented concentration metrics indicate persistent opportunities to consolidate channel control without encountering systemic regulatory barriers.
-
Strategic partnerships: Distribution alliances and co-development pacts will accelerate route-to-market for alternative substrates. Distributor network plays — including exclusive and hybrid distribution models — will continue to reshape competitive dynamics.
-
R&D prioritization: Allocate resources to performance parity and cost parity projects: water-use efficiency, nutrient-release profiles, and root-health engineering. Trials with anchor growers that include agronomic KPIs will shorten adoption cycles.
Final Takeaway: Move from Compliance to Commercial Advantage
For executives making 2026 decisions, the greenhouse soil market presents a classic transition opportunity: regulatory and input-cost pressures are forcing change, but they also create value for firms that convert sustainability and supply resilience into verifiable performance advantages. PW Consulting’s analysis shows the market expanding at approximately 5.5% CAGR through 2032 — a base case that rewards smart investment in formulation, near-market manufacturing, and channel architecture.
To convert these strategic themes into executable plans, download the full Greenhouse Soil Market report for the detailed segmentation models, supplier scorecards and scenario-ready financials that your strategy, procurement and R&D teams will require.
For detailed analysis of this topic, please visit the official page: Greenhouse Soil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


