



PW Consulting: AIN Market to Hit USD 239.11 Million by 2032 at 5.5% CAGR

Aluminum Nitride (AlN) Market — Strategic Preview for 2026 Decision-Making
By PW Consulting — Senior Strategy Advisor & Chief Industry Analyst
Aluminum Nitride (AIN) Market
Executive snapshot
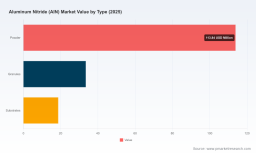
The Aluminum Nitride (AlN) market is entering a phase of steady, structurally driven expansion. After a recovery period across 2020–2025, the market size reached approximately USD 166.02 Million in our base year (2025) and is forecast to grow at a compound annual growth rate (CAGR) of about 5.5% through 2032, reaching roughly USD 239.11 Million. That trajectory reflects a maturing but technically demanding value chain where thermal-management imperatives, semiconductor device transitions, and supply-side constraints together set the rules of competition.
Aluminum Nitride (AIN) Market
Why this study matters for 2026 strategic decisions
-
Timing: 2026 will be the first full year companies execute post‑COVID, geopolitically adjusted strategies. Decisions taken this year about sourcing, capacity, and product roadmaps will determine value capture across the 2026–2032 window.
Aluminum Nitride (AIN) Market -
Capital allocation: With market growth predictable yet specialized, capital must be targeted to capability gaps (single-crystal substrates, advanced heat-spreader manufacturing, proprietary composite formulations) rather than generalized expansion.
-
Risk management: Raw-material bottlenecks and export licensing regimes are active variables that can rapidly reconfigure supply networks — a dedicated compliance and procurement playbook is now table stakes.
What the full report delivers — operational content you can act on
Our research is designed as an operator’s toolkit, not a theoretical overview. The deliverables include:
-
Robust market-sizing and scenario modeling calibrated to 2020–2025 historicals and 2026–2032 forecasts, including sensitivity to raw‑material pricing and capacity ramp assumptions.
-
Competitive landscape with quantified concentration metrics, capability maps, and go-to-market positioning for incumbents and challengers.
-
Detailed supplier and downstream maps (from powders and granules to machined substrates and packaged solutions), including bottleneck identification and mitigation playbooks.
-
Regulatory and export-control matrix tailored for procurement, R&D, and sales teams — practical checklists for EAR classifications and licensing pathways affecting military or dual‑use applications.
-
Commercial playbooks: procurement hedging strategies, vertical-integration decision frameworks, partnership/JV models, and M&A screening criteria prioritizing technological defensibility and supply security.
-
Technical roadmaps and product-development KPIs for prioritizing investments in single‑crystal versus sintered AlN, improvements in thermal conductivity, and manufacturability enhancements.
-
Price & margin modelling templates and contract structures (long-term off-take, indexation clauses linked to high‑purity aluminum inputs, and allocation mechanics for constrained supply periods).
Market structure and competitive dynamics — what to watch
The market is characterized by a concentration profile that favors a limited set of specialized manufacturers and technology owners. Our analysis shows a significant portion of industry revenue is captured by the top-tier leaders, and the top five firms command an even larger share. This concentration creates predictable opportunities and risks:
-
Opportunities for incumbents: premium pricing for high‑reliability substrates and single‑crystal products, where technological barriers and long qualification cycles raise switching costs for buyers.
-
Opportunities for challengers: niche specialization (e.g., rapid prototype machining, custom formulations for extreme thermal applications, or regional supply hubs) can disinterplace broad, less agile suppliers.
-
Systemic risk: when supply is concentrated, raw-material shocks or regulatory controls (including export licensing) have outsized market impact — creating windows for opportunistic entrants and consolidation.
Company positioning — practical takeaways
Selected firm-level implications based on corporate capabilities and recent activity:
-
CoorsTek — well positioned for custom-engineered ceramics and application-specific formulations. Best practice for incumbents: leverage application engineering services to lock in design wins with OEMs that face high qualification barriers.
-
CeramTec — product branding and established thermal management offerings make it a default supplier for conservative OEMs. Strategy focus: incremental innovation in heat-sink integration and modular substrates to protect margin.
-
KYOCERA — broad packaging and substrate portfolio with global reach. Path to value: integrate system-level design services with local compliance expertise to mitigate export-control frictions for multinational customers.
-
Crystal IS and HexaTech — leaders in single-crystal substrate development; recent moves into pilot and commercial-scale production signal a structural shift toward larger-diameter wafers and higher-volume device qualification. Buyers and investors should treat their capacity expansions as inflection points for downstream device roadmaps.
-
Tokuyama, Precision Ceramics, Accumet — supply‑chain specialists with strengths spanning powder purity, machining, and material supply. Tactical recommendation: secure long-term supply or strategic minority investments to stabilize inputs and protect roadmaps.
Recent developments and their strategic implications
-
Crystal IS’s pilot production for larger-diameter AlN substrates (announced April 2026) accelerates the commercialization timetable for high-volume UVC and power-device applications. Companies reliant on legacy substrate sizes must evaluate qualification roadmaps and potential re‑qualification costs.
-
HexaTech’s launches through 2025–2026 (optimized nitrogen-face substrates and a commercial 76.2 mm product) reduce time-to-market for power/RF manufacturers seeking single-crystal performance at scale. OEMs should quantify performance uplift versus requalification overhead.
-
KYOCERA’s expanded product guidance (April 2026) reduces buyer uncertainty by clarifying package-level options and qualification resources — a signal that suppliers are shifting from component vendors to co-engineering partners.
Supply-side realities and regulatory noise
Two structural dynamics require immediate attention in 2026 planning:
-
Raw-material constraints: the limited global availability of high‑purity inputs constrains potential market share expansion. Price volatility in high-purity aluminum and nitrogen compounds — driven by supply disruptions and concentrated upstream suppliers — will materially affect margins unless companies hedge or secure integrated supply.
-
Export and licensing regimes: AlN substrates are increasingly subject to export controls and licensing in major jurisdictions. US and Japanese export licensing requirements, and classifications under EAR for certain end uses, complicate cross-border sales and should inform both channel strategy and customer contracting.
Recommended 2026 playbook — five practical moves
-
Secure supply through layered contracts: combine long-term off-take agreements with spot volume to balance price and flexibility. Include raw‑material indexation and force‑majeure clauses keyed to regulatory shifts.
-
Invest selectively in qualification programs: prioritize substrates and formats that align with your end-market roadmap (power electronics, microelectronics, or niche high-reliability uses). Qualification investment is a durable moat in a market with high switching costs.
-
Build compliance and export-control capabilities: equip commercial and legal teams to handle EAR and equivalent frameworks, and map sales channels against licensing risk profiles before committing capacity.
-
Pursue capability alliances: consider JV structures or minority equity stakes in upstream suppliers (powder/granule producers or single-crystal specialists) to secure throughput without full-scale capital exposure.
-
Differentiate through systems integration: move beyond component sales toward co-engineered thermal-management solutions and packaging services that raise customer switching costs and provide higher margin capture.
How PW Consulting can help in 2026
Our full AlN market study provides the granular, segment-level data and supplier tables that commercial, procurement, and M&A teams require to operationalize the strategies outlined above. The public preview you are reading intentionally omits the precise regional and application splits and the raw segmentation tables — that intelligence is reserved for subscribers and clients, because it is the defensible insight teams use to execute deals, hedge procurement, and scope product investments.
If your organization is planning capital deployments, sourcing redesign, or M&A in 2026, the combination of our scenario models, supplier scorecards, and regulatory compliance matrix will reduce execution risk and improve time-to-value.
Closing — what to act on now
For 2026, treat the AlN market as a technically specialized growth opportunity with asymmetric risk: modest but predictable market expansion (5.5% CAGR to 2032) and concentrated supplier power. The immediate actions that separate winners from laggards are straightforward — secure supply, prioritize qualification, and embed regulatory compliance into commercial plays. For teams ready to move from strategy to execution, our full report contains the segment-level forecasts, contractual templates, and supplier due‑diligence that translate strategy into measurable outcomes.
Access to the complete dataset and the practitioner playbooks is available through PW Consulting’s market portal and advisory services. The market is small by revenue but large in strategic consequence — execute with precision in 2026 to capture outsized benefits through 2032.
For detailed analysis of this topic, please visit the official page: Aluminum Nitride (AIN) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


