



PW Consulting: RTLS in Sports to grow at 26.4% CAGR

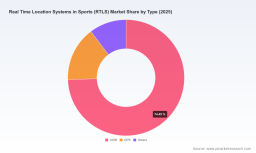
Real Time Location Systems in Sports — Strategic Preview for 2026
As PW Consulting’s lead industry analyst, I present a focused, decision-oriented preview of our full Real Time Location Systems in Sports (RTLS) market study. This introduction is designed as a strategic “trailer”: it surfaces the research’s high-value insights, methodology rigor, and actionable implications for 2026 planning — while intentionally withholding granular segmentation tables and proprietary benchmarks that are available in the complete report.
Real Time Location Systems in Sports (RTLS) Market
Why RTLS in Sports is a 2026 Boardroom Priority
-
RTLS has evolved from niche performance tools into a strategic operations and revenue-enablement layer for teams, venues, broadcasters and equipment manufacturers. Organizations planning budgets and roadmaps for 2026 will need to treat RTLS as cross-functional infrastructure — one that touches coaching, health & safety, fan experience, stadium operations and sponsorship monetization.
Real Time Location Systems in Sports (RTLS) Market -
The macro trajectory is undeniable. After a period of steady adoption through the early 2020s, the RTLS-in-sports market has accelerated sharply: the market expanded markedly between 2020 and 2025 and, with a compound annual growth rate of 26.4% projected into the forecast window, is on track to multiply several-fold over the coming half-decade. That growth profile transforms RTLS from an incremental analytics tool into a strategic platform worth board-level attention.
Real Time Location Systems in Sports (RTLS) Market -
For 2026, companies must decide whether to build, buy, or partner around RTLS capabilities. Those decisions will determine competitive positioning in performance services, venue operations, and new fan-facing propositions (e.g., real-time AR experiences, precision advertising, and sponsored analytics products).
Market Trajectory and What it Means for Strategic Planning
Using 2025 as the base year, our historical review (2020–2025) and forecast (2026–2032) show a clear inflection: the market grows from single-digit millions in the early 2020s to a materially larger, enterprise-grade market by the early 2030s. This is driven by rising adoption across professional and semi-professional teams, the professionalization of venue operations, the economics of broadcast and sponsorship data, and improving cost-performance of positioning technologies.
What this trajectory implies for 2026 decision-makers:
-
Prioritize platform interoperability. The pace of vendor innovation and the emergence of hybrid-fit architectures mean that proprietary, closed systems risk rapid obsolescence. Investments in open APIs, middleware, and integration standards will protect future option value.
-
Reassess procurement frameworks. Traditional capex procurement for single-technology vendor solutions is being challenged by outcome-based contracting, SaaS analytics pricing, and bundled hardware-as-a-service offers. Procurement teams should design RFIs that compare lifecycle TCO and service SLAs, not just unit hardware cost.
-
Embed privacy and risk controls up-front. As athlete and spectator tracking expands, privacy, data governance, and stadium-level cybersecurity must be designed into deployments to avoid reputational and regulatory costs.
Technology Paths and Strategic Trade-Offs
RTLS now spans several technical families — ultra-wideband (UWB), Bluetooth Angle-of-Arrival (AoA/BLE), GPS-augmented systems, and hybrid integrations combining short-range precision with wide-area location. Each offers trade-offs across precision, infrastructure cost, ease of integration, and deployment scale.
-
Precision-first architectures (e.g., UWB) are compelling for athlete biomechanics, indoor play diagnostics, and training labs where sub-meter accuracy drives measurable performance gains. For teams, the decision to adopt precision hardware must be paired with a data pipeline that turns positional telemetry into coaching actions and athlete welfare insights.
-
Cost-optimized and high-volume applications (e.g., BLE AoA) have emerged as practical solutions for crowd navigation, staff coordination, and sponsorship-triggered location services. These platforms reduce barrier-to-entry for venue-wide initiatives but require robust calibration and analytics layers to reach the data quality needed for competitive scouting and broadcast augmentation.
-
Hybrid approaches — combining wide-area GPS with indoor positioning and edge analytics — present a pragmatic middle path for multi-venue operators, touring sports, and events that need consistent cross-site telemetry without reengineering each venue.
Competitive Landscape: Strategic Positions and Near-Term Moves
The market is consolidating around a mix of specialist vendors and integrators. Overall concentration metrics indicate that top-tier players hold a meaningful share of the market while space remains for focused innovators and system integrators. For 2026, competitive dynamics will be defined by partnerships, platform openness, and industry-specific services rather than pure hardware price competition.
-
Catapult Sports (Australia) — Strong in athlete monitoring with integrated indoor/outdoor solutions. Their strategic advantage is deep domain expertise with professional teams and a product roadmap that marries tracking hardware to performance analytics and athlete load management. For 2026, Catapult will likely emphasize enterprise analytics subscriptions and tighter broadcast integrations.
-
Quuppa Oy (Finland) — A leader in Bluetooth AoA positioning for venues and events. Recent developments in early 2026 (announced compatibility between specific beacons and Quuppa’s Intelligent Locating System, plus the Precision Label Tag initiative) signal a push to scale low-cost, high-volume deployments. For stakeholders, this means BLE-based high-density solutions are becoming viable for stadium-wide use cases, lowering the threshold for operations and fan-experience projects.
-
Blueiot (China) — Focused on Bluetooth AoA RTLS for stadium navigation and crowd management. Their value proposition centers on cost-efficient deployments in large venues and event operations. Strategic partnerships will be critical for global expansion.
-
Eliko (Finland), WISER (USA), Sewio Networks (Denmark), and Litum (USA) — These vendors represent the diversity of approaches: UWB precision (Eliko, WISER), multi-technology flexibility (Sewio), and hybrid UWB/BLE/LoRaWAN platforms (Litum). Each has carved out vertical plays — from in-field performance analytics to stadium operations and asset tracking. Expect increased verticalization of product suites and more channel-focused business models in 2026.
Market Structure and Strategic Implications
The RTLS-in-sports market exhibits moderate concentration: the three largest players account for a sizeable portion of market revenue, and the top five capture an even larger share. This structure produces both risks and opportunities for 2026 planning:
-
Entrants and niche specialists can achieve rapid traction by focusing on a single, high-value use case (e.g., training analytics or sponsor-branded in-stadium experiences) and by offering easy integration with incumbent team systems.
-
Large vendors will continue to win enterprise contracts that bundle analytics, service, and hardware across club networks or venue portfolios. For corporate buyers, this means negotiating on platform openness and future-proofing analytics portability.
Actionable Deliverables in the Full Report
The full PW Consulting study goes far beyond headline forecasts. It equips commercial, technical, and investment decision-makers with practical tools to act in 2026:
-
Multi-scenario financial forecasts and sensitivity analyses that translate market growth into addressable opportunity for enterprise tiers and vendor classes.
-
Deployment blueprints for three common buyer archetypes (professional team, venue operator, event integrator) that include recommended technology stacks, staged rollout plans, and estimated implementation timelines.
-
Vendor assessment frameworks and decision matrices that benchmark providers across precision, latency, integration maturity, commercial model, and partner ecosystems. Note: the full vendor scorecards and detailed segmented tables are omitted from this preview to preserve the report’s proprietary intelligence.
-
Use-case ROI calculators that convert tracking accuracy and telemetry frequency into measurable coaching, medical, and commercial outcomes — enabling procurement and finance to model return on investment for 2026 budgets.
-
M&A and partnership playbook highlighting strategic targets, valuation vectors, and integration pitfalls relevant to acquirers seeking to accelerate capability through inorganic growth.
Risks, Regulatory Considerations and Operational Pitfalls
Rapid growth carries attendant risks that buyers and investors must account for in 2026:
-
Data governance and consent management: athlete and fan data is sensitive. Systems must be designed to comply with evolving privacy expectations and local regulations.
-
Operational scaling: stadium-wide rollouts are operationally different from lab-scale deployments. Underestimating calibration, maintenance and staff training leads to poor data quality and wasted spend.
-
Vendor lock-in: proprietary data formats and closed analytics can impair future product choices. Contractual protections and interoperability requirements should be non-negotiable in 2026 procurement.
How to Use This Research in 2026 Decision Cycles
-
Strategy teams: map RTLS capabilities to strategic objectives (performance, safety, revenue) and use our scenario forecasts to stress-test investment cases across growth and adoption scenarios.
-
Procurement: issue modular RFPs that separate hardware, connectivity, and analytics, and require lifecycle TCO and SLAs. Use the vendor matrices in the full report to shortlist partners.
-
CTOs and Systems Integrators: prioritize open APIs, cloud-edge pipelines, and device management. Build playbooks for cross-venue deployments to capture touring sports and franchise networks.
-
Investors and acquirers: use our concentration and forecast analyses to identify consolidation targets and evaluate revenue multipliers tied to platform and services revenue growth.
Conclusion — The 2026 inflection point is here. RTLS in sports is moving from experimental to foundational. The strategic choices organizations make this year — around platform architecture, commercial model, and partner selection — will determine who captures the performance, operational and commercial upside over the next decade.
To access the full dataset, detailed segmentation, vendor scorecards, and deployment playbooks that underpin these strategic conclusions, please consult the PW Consulting full Real Time Location Systems in Sports market report.
For detailed analysis of this topic, please visit the official page: Real Time Location Systems in Sports (RTLS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


