



PW Consulting: Smart Water Meters Market Poised for 9.6% CAGR (2026–2032)

Smart Water Meters Market: Strategic Preview for 2026 Decision-Makers
Executive summary
As utilities and water-stressed regions accelerate digitalization, smart water meters are shifting from niche efficiency projects to foundational infrastructure investments. PW Consulting’s forthcoming market study — based on a 2025 base year and covering historical performance from 2020–2025 with a 2026–2032 forecast horizon — quantifies this transition: the market is projected to expand at a compound annual growth rate (CAGR) of 9.6% through 2032. After a recalibration in the base year, our modeling shows renewed growth beginning in 2026 and an expected near-doubling of the market by the end of the forecast period.
Smart Water Meters Market
Why this matters for 2026 strategic decisions
-
Timing capital deployment: Utilities, integrators and meter manufacturers must align 2026 procurement cycles with multi-year AMI/AMI+ rollout plans to capture upside from accelerated replacement programs and federal/grant funding windows.
Smart Water Meters Market -
Technology choice and future-proofing: Connectivity standards (LoRaWAN, cellular, RF, 5G-ready designs) and edge analytics architectures will determine upgrade costs and interoperability risks for the next 10+ years.
Smart Water Meters Market -
Vendor selection beyond price: Lifecycle total cost of ownership (installation, network fees, data management, cybersecurity and replacement cadence) overtakes unit price as the primary commercial differentiator.
-
Operational transformation: Labor cost savings from eliminating routine drive-by reads and enabling proactive leak detection change utility staffing models and capex/opex allocation.
-
Regulatory and funding windows: Programs like the EU and national grant initiatives materially de-risk investment for municipalities — timing applications and vendor partnerships will be a decisive factor in 2026 initiatives.
Market trajectory: the headline numbers (what we disclose here)
PW Consulting’s headline view uses 2025 as the base year. After a normalization that year, the market is forecast to grow at a 9.6% CAGR across 2026–2032, driven by a mix of mandated replacements, voluntary efficiency programmes, and the economics of remote monitoring. Our top-line projection indicates a recovery and steady expansion beginning in 2026, culminating in significantly higher annual market value by 2032 versus the recent base year. For executives planning procurement windows, that implies expanding available vendor capacity, intensifying competition for large municipal programs, and the need for scalable integration approaches.
What the PW Consulting report delivers (practical, actionable elements)
-
Decision-ready scenario modelling: three investment scenarios (conservative, baseline, accelerated) that translate macro adoption drivers, grant timing and replacement cycles into procurement volumes and budgetary implications for 2026–2028.
-
Vendor evaluation framework: a practical scorecard that weights technical compatibility, network strategy, analytics maturity, TCO, warranty and supply-chain resilience — calibrated for utilities, EPCs and large commercial end-users.
-
Integration playbook: step-by-step guidance for integrating smart meter data into existing SCADA and billing systems, plus recommended API and data governance patterns to reduce time-to-value.
-
Procurement templates: RFP language, acceptance test scripts and inspection checklists that reduce risk in field rollouts and protect against interoperability pitfalls.
-
Risk register and mitigation: prioritized project risks (from cybersecurity to component obsolescence) with recommended contractual protections and monitoring KPIs.
Competitive landscape — how incumbent and challenger strategies are shaping the market
The smart water meter market is characterized by a mix of specialized meter manufacturers, AMI platform providers and large systems integrators. Rather than a winner-take-all dynamic, competition is playing out across three vectors: metering hardware accuracy and energy profile; communication stacks and network partnerships; and analytics/platform capabilities that translate meter reads into operational decisions.
-
Badger Meter (Milwaukee, USA) — Strengths: deep pedigree in ultrasonic and mechanical meters coupled with AMI integrations and strong analytics for leak detection. Strategic implication: established utilities seeking end-to-end solutions will favor suppliers that can bundle meters, networks and analytics under contracted SLAs.
-
Sensus (Xylem, Lindon, USA) — Strengths: AMI-enabled meters with flexible cellular and private wireless options and a focus on customer-facing portals. Strategic implication: vendors offering multiple connectivity options reduce vendor lock-in risk for utilities that want phased network strategies.
-
Neptune Technology Group (Tallassee, USA) — Strengths: municipal utility integration expertise and field-proven AMI systems. Strategic implication: procurement teams should validate municipal reference sites and governance models; proven public-sector deployments lower adoption friction.
-
Itron (Madison, USA) — Strengths: advanced AMI platforms and a notable focus on AI/real-time leak prevention. Strategic implication: buyers prioritizing analytics-first strategies will value flexible APIs and data science toolkits that can be co-developed with vendors.
-
Kamstrup (Aalborg, Denmark) — Strengths: energy-efficient meters with LoRaWAN and cellular capabilities, high emphasis on low power design. Strategic implication: long-lived networks and constrained-power installations benefit from meters designed for ultra-low consumption.
-
Diehl (Nuremberg, Germany) — Strengths: ultrasonic offerings with standardized connectivity modules. Strategic implication: modular hardware designs simplify upgrades and can lower replacement costs over time.
-
Landis+Gyr (Schaffhausen, Switzerland) — Strengths: integrated software platforms and demand response experience. Strategic implication: utilities seeking cross-utility integration (electricity + water) will prioritize vendors with robust platform convergence roadmaps.
-
Zenner, Honeywell, Aclara (Hubbell), Wasion, BMETERS — Market roles: regional specialists, connectivity innovators (including 5G and RF-driven solutions), and providers with strong prepaid / international certification experience. Strategic implication: local certification, channel relationships and service presence remain decisive for municipal procurement processes.
Recent market movements and policy drivers — why 2026 is pivotal
Field activity and funding have picked up pace in early 2026, signaling that many projects which were planned or paused during earlier economic uncertainty are now restarting under clearer funding frameworks. Examples observed by PW Consulting include municipal rollouts completing upgrades and new AMI replacement starts, often leveraging federal grants and municipal funding. Additionally, public programs and R&D initiatives in Europe and North America are actively subsidizing smart water deployments to accelerate leak detection and conserve scarce resources.
-
Municipal upgrades returning to the field: multiple utilities completed or restarted large-scale rollouts in 2026, enabling hourly reads and customer portals.
-
Grant-driven acceleration: targeted reimbursement programs are materially lowering the capital hurdle for smaller districts and towns, enabling them to adopt AMI sooner than their internal budgets would have allowed.
-
Connectivity upgrades: vendors and carriers are moving toward 5G-ready and hybrid connectivity strategies, improving latency and supporting higher-resolution telemetry for real-time analytics.
Operational implications and go-to-market playbook for suppliers
For vendors, 2026 is a make-or-break year to demonstrate integrated solutions that minimize utility integration burden. Successful suppliers will combine:
- field-proven meter hardware with modular comms options,
- well-documented APIs and edge analytics to reduce integration timelines, and
- financial offers (leasing, managed services, risk-sharing contracts) that align vendor incentives with utility outcomes like reduced NRW (non-revenue water) and customer complaints.
For utilities, procurement should prioritize pilot-to-scale paths with explicit success gates tied to leak-detection performance, data quality KPIs and measurable OPEX savings from reduced manual reads.
Risks, mitigations and blind spots
-
Supply chain volatility: component lead times and certification delays can slow rollouts — mitigate with multi-sourcing and phased deployments that decouple meter hardware refreshes from network upgrades.
-
Interoperability: proprietary platforms create long-term switching costs — require open standards and data export clauses in contracts.
-
Cybersecurity: increased telemetry expands attack surface — insist on security-by-design, firmware update pathways and clear incident response SLAs.
-
Regulatory uncertainty: evolving standards and funding criteria can alter economics — model multiple grant-uptake scenarios and maintain flexible procurement windows.
What we are intentionally not disclosing here (and why)
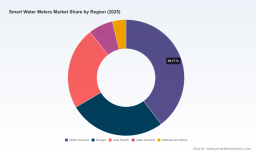
In keeping with our “trailer” principle — to demonstrate analytical depth while reserving high-resolution programmatic intelligence for purchasers — this article omits the full regional and application-level segmentation tables, detailed vendor market shares by channel, and the granular price curve models that underpin our procurement simulations. These items are included in the full PW Consulting Smart Water Meters Market report and are available via our report portal. Clients who need the full data pack and scenario models can access the detailed breakdowns, which include regional forecasts, type- and application-level demand drivers, and bespoke vendor scorecards.
How to proceed in 2026
-
If you lead procurement or asset planning: request the PW Consulting scenario pack to align your 2026 capex with the projected recovery curve and identify optimal tender windows.
-
If you are a vendor: use our vendor-scorecard templates to stress-test product roadmaps against utility buying criteria and to prepare for grant-funded municipal tenders.
-
If you are an investor or integrator: leverage the report’s market sizing and concentration analysis to prioritize partnerships and to size potential service revenue pools.
Next steps
PW Consulting’s Smart Water Meters Market study is designed to be immediately operational — translating market signals into procurement templates, integration best practices and vendor due diligence tools for 2026. To access the complete dataset, the modular scenario models, and the full competitive intelligence suite, please visit our report landing page (link included with the full release) or contact your PW Consulting analyst to schedule a briefing and customized walkthrough.
For detailed analysis of this topic, please visit the official page: Smart Water Meters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


