



PW Consulting: Low-Voltage DC-DC LED Drivers Set to Hit USD 458.6M by 2032 at 6.2% CAGR

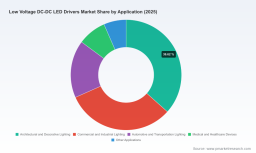
Low-Voltage DC-DC LED Drivers Market: Strategic Outlook for 2026 Decision-Makers
Introduction — why this market matters now
The low-voltage DC-DC LED drivers market sits at the intersection of two high-velocity trends: relentless efficiency improvements in LED lighting and the electrification of end systems (from portable devices to vehicles). Our latest PW Consulting study, using 2025 as the base year, shows the market reaching approximately USD 309.5 Million in 2025 and projecting to grow to about USD 458.6 Million by 2032 at a compound annual growth rate (CAGR) of 6.2% over the forecast period. The report covers historical performance (2020–2025), a detailed forecast window (2026–2032), and a multifaceted set of analytical tools designed to support commercial, product and M&A decisions ahead of and through 2026.
Low Voltage DC-DC LED Drivers Market
Why boardrooms, product teams and investors must pay attention in 2026
- Acceleration of energy-efficiency regulation and procurement specifications is compressing time-to-compliance for lighting OEMs and subsystem suppliers; decisions made in 2026 will shape product roadmaps and qualification pipelines for years.
- Technical advances (hysteretic buck architectures, high-efficiency ICs, integrated PWM dimming and flicker-free control) are creating a new performance floor — winners will convert efficiency gains into system-level differentiators.
- Market structure is neither a tight oligopoly nor a highly fragmented long tail: our concentration metrics show leading groups command a material but non-dominant share, leaving room for strategic consolidation and premium niche plays.
- Electrified platforms (automotive, portable medical devices, and IoT-enabled fixtures) are shifting design constraints toward miniaturization, thermal management and battery-friendly topologies — suppliers who adapt quickly will capture disproportionate value.
What this PW Consulting report delivers (practical, decision-ready content)
- Demand and revenue model calibrated to 2020–2025 history with scenario-based forecasts through 2032. The base-case embeds a 6.2% CAGR; alternate scenarios quantify upside/downside sensitivity to regulatory acceleration, EV adoption curves, and component cost volatility.
- Technology and product benchmarking, including architecture trade-offs (isolated vs non-isolated topologies), control modes (hysteretic vs PWM), dimming strategies, and reference designs that balance flicker, efficiency and cost.
- Supplier scorecards and comparative matrices that evaluate R&D depth, manufacturing footprint, product maturity, and channel reach — designed to accelerate vendor shortlists for qualification programs.
- Go-to-market playbooks for component vendors and lighting OEMs: SKU rationalization templates, pricing sensitivity analyses, and commercial partnership models (co-development, licensing, and joint validation strategies).
- Supply-chain and risk heatmaps: component bottlenecks, second-source strategies, inventory optimization levers, and near-term mitigation actions for commodity or capacity shocks.
- M&A and partnership intelligence: candidate lists, valuation heuristics, and integration checklists that balance technology capture with go-to-market scale.
- Regulatory and standards compendium: compliance timelines, testing implications, and product certification roadmaps relevant to low-voltage LED drivers across major markets.
Key market dynamics and technological implications
The market’s moderate, steady growth reflects a balance of tailwinds and headwinds. On the upside, LED efficacy improvements and procurement mandates for energy-efficient lighting systems continue to create replacement and upgrade cycles across commercial, architectural and industrial segments. Innovations at the IC and module level — exemplified by sub-1.5 A hysteretic buck controllers and near-98% peak conversion efficiencies — are pushing feasible system efficiencies higher while enabling smaller thermal envelopes.
Low Voltage DC-DC LED Drivers Market
Conversely, pressures including increasing expectations for flicker-free performance, EMI compliance, and tighter thermal budgets add engineering cycle time and qualification risk. Supply-chain constraints for passive components and some specialized semiconductors remain a persistent source of downside risk. Our study quantifies the trade-offs between cost, efficiency and time-to-market for a wide set of architectural choices so executives can prioritize investments with clear ROI horizons.
Low Voltage DC-DC LED Drivers Market
Competitive landscape — profiles and strategic implications
- Texas Instruments (Dallas, USA) — Strength: broad IC portfolio and reference designs supporting flicker-free, low-voltage drives. Strategic implication: TI’s leadership in reference designs accelerates OEM time-to-market; competitors should anticipate TI-driven platform expectations in spec sheets.
- Analog Devices (Wilmington, USA) — Strength: analog IC expertise and co-development focus for automotive/consumer lighting. Strategic implication: partnerships with ADI can de-risk automotive qualifications but may demand co-engineering investments.
- STMicroelectronics (Geneva, Switzerland) — Strength: PWM-dimmable driver ICs and integrated power-management solutions. Strategic implication: ST’s breadth supports vertically integrated modules, favoring OEMs seeking single-supplier simplification.
- Infineon Technologies (Munich, Germany) — Strength: high-current hysteretic buck ICs with exceptional efficiency metrics. Strategic implication: Infineon’s efficiency leadership allows system designers to trade power density for lower cooling costs in premium fixtures.
- Diodes Incorporated (Plano, USA) — Strength: medium/low-voltage driver portfolio targeting high-current LEDs. Strategic implication: Diodes can be an attractive second-source or niche play for mid-tier suppliers.
- Molex (Downers Grove, USA) — Strength: integrated driver modules (CoreSync, Transcend Smart) for constant-current LED engines. Strategic implication: Molex targets system integrators who prioritize fixture-level integration over IC-level design ownership.
- LEDdynamics (USA) — Strength: productized BuckToot drivers for fixture applications. Strategic implication: specialized module vendors present attractive targets for OEMs seeking plug-and-play solutions.
- ON Semiconductor (Scottsdale, USA) — Strength: discrete and IC-based power-management solutions. Strategic implication: ON’s portfolio favors cost-optimized, high-volume applications where design-for-manufacturability is paramount.
- Monolithic Power Systems (San Jose, USA) — Strength: hysteretic control buck drivers (e.g., MP2489) with DC/PWM dimming. Strategic implication: MPS competes on compactness and integration, a compelling option for battery-powered and space-constrained fixtures.
Collectively, the top-tier suppliers exercise meaningful influence — our concentration metrics indicate leading groups command a material share of the market while leaving substantive room for challengers and vertical integrators. That structure creates a strategic environment where focused R&D or a targeted acquisition can rapidly change a supplier’s competitive position.
Actionable strategic playbook for 2026
- For component manufacturers: prioritize platform architectures that optimize for thermal density and flicker-free dimming; invest in reference designs and validation kits to shorten OEM qualification cycles. Consider licensing or co-development to enter automotive lighting paths more quickly.
- For lighting OEMs: shift from component sourcing to platform procurement criteria — require full-system reference validation, test vectors for flicker/EMI, and life-cycle cost models. Build preferred-supplier partnerships with access to joint NPI roadmaps.
- For system integrators and installers: standardize on modular driver platforms that enable rapid retrofits and predictable maintenance; push for vendor-neutral certification templates to reduce project risk.
- For private equity and strategic buyers: target bolt-on acquisitions that add either high-efficiency topologies or productized module offerings that accelerate path-to-revenue. Use our report’s valuation heuristics and integration checklists to vet targets.
- Cross-cutting: implement a two-track inventory and qualification strategy — maintain a premium validated supplier for high-margin programs while developing a cost-optimized second source for volume deployments.
Scenario framing and risk sensitivities
Our base scenario (the one aligned with the 6.2% CAGR) reflects gradual regulatory tightening and steady uptake across key end-markets. Two alternative scenarios illustrate strategic sensitivities:
- Upside: accelerated electrification in transportation and mandatory energy-efficiency upgrades drive faster replacement cycles and higher ASPs for premium driver modules.
- Downside: component supply shocks or delayed regulatory enforcement push OEMs toward lower-cost topologies and extend qualification cycles, compressing near-term revenue growth.
Each scenario is modeled with clear sensitivities (price elasticity, time-to-qualification, BOM composition) in the full report so decision-makers can quantify trade-offs and design contingency plans.
What we intentionally withhold — and why
To preserve the trailer nature of this executive preview and to respect the value of our proprietary work, this introduction highlights macro-scale intelligence (market size, CAGR, concentration and qualitative supplier analysis) while withholding the granular, high-value segmentation tables, regional splits, per-application revenue curves, and company-level market shares. These elements are central to rapid, actionable decisions — and are available in the full dataset and downloadable models included with the PW Consulting report.
How to use this report in your 2026 planning cycle
- Embed our demand and scenario models directly into your 2026 budget and product roadmaps to align R&D investments with revenue and margin outcomes.
- Use supplier scorecards to compress vendor selection timelines and negotiate performance-based milestones into development contracts.
- Leverage the M&A intelligence and valuation heuristics to assemble a prioritized shortlist of acquisition or partnership targets that accelerate either technology or channel reach.
- Adopt the report’s regulatory and test-matrix checklists to reduce product recall and requalification risk on new hardware launches.
PW Consulting’s Low Voltage DC-DC LED Drivers Market study is designed to be a practical, execution-oriented tool for 2026: it pairs a clear macro outlook (USD 309.5 Million in 2025 growing at a 6.2% CAGR) with the tactical playbooks, supplier intelligence and financial models executives need to make high-consequence decisions. For the granular segmentation, vendor market shares, and downloadable financial models that underpin the recommendations summarized here, please consult the full report.
For detailed analysis of this topic, please visit the official page: Low Voltage DC-DC LED Drivers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


