



PW Consulting: Specialty Paper Market to Expand at 5.1% CAGR Through 2032

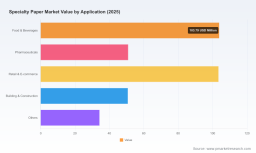
Specialty Paper Market — Strategic Preview for 2026 Decision-Makers
As companies reposition supply chains, re-price packaging, and decarbonize production in 2026, specialty papers have moved from a back-office raw material to a strategic battleground. This Specialty Paper Market introduction — prepared by PW Consulting’s senior industry team — synthesizes the directional intelligence and decision-grade analysis you need to prioritize investments, M&A, and commercial strategies over the next planning cycle. It demonstrates the depth of our work while deliberately withholding the granular segment spreadsheets and regional splits that are reserved for the full report.
Specialty Paper Market
Why this study matters now
The global specialty paper market has shown consistent expansion through 2020–2025 and entered 2026 from a position of renewed commercial significance. Measured in USD Million, the market rose from the high‑two‑hundreds in 2020 to a mid‑three‑hundreds base in 2025, and our consolidated forecast projects a continuation of growth through 2032. The report’s model produces an expected compound annual growth rate (CAGR) of 5.1% for the 2026–2032 forecast window — a profile that combines structural demand for higher‑value paper grades with episodic raw‑material and capacity shocks.
Specialty Paper Market
For executives this means three practical realities: (1) the market is large enough that modest share shifts materially affect revenue and margin; (2) premiumization and technical differentiation are the principal levers for profitable growth; and (3) tactical moves today (capacity deals, contracts, product launches) will determine competitive position over the next 3–5 years.
Specialty Paper Market
What the report delivers — practical, transaction‑grade insight
- Top‑line sizing and a transparent forecast model (historical years 2020–2025; base year: 2025; forecast period: 2026–2032), with scenario outputs and sensitivity analysis tied to pulp prices and capacity changes.
- A dynamics map of demand drivers (packaging evolution, e‑commerce, food safety, industrial applications) and supply‑side constraints (pulp availability, mill closures, regional expansions).
- Pricing and margin workstreams: cost‑build for key paper grades, recent pass‑through behaviour, and scenarios under sustained pulp price pressure.
- A competitive playbook: 11 in‑depth company profiles, strategic positioning matrices, and acquisition/opportunity heatmaps for buyers and sellers.
- Commercial diligence templates and an M&A checklist tailored to specialty paper transactions (technical, environmental, customer concentration, and capex cadence).
- Operational guidance: recommended short‑cycle levers (capacity redeployment, coating investments) and longer‑term bets (fiber innovation, circularity investment).
Key strategic themes for 2026
- Premiumization is accelerating. End‑market demand is increasingly for higher‑performance, barrier‑capable and functional papers that command margin premiums — rewarding firms that combine coating capability, consistent fiber quality, and regulatory compliance.
- Input cost volatility is decisive. Pulp cost shocks are propagating into list prices and contract renegotiations; companies that align procurement, hedging, and value capture will preserve margin.
- Regional capacity shifts are reshaping trade flows. Capacity additions and rationalizations in manufacturing hubs are changing export and import patterns; agility in logistics and sourcing is now a competitive advantage.
- Consolidation and targeted acquisitions are intensifying. The market concentration metrics show a moderate leader group (CR3 ~35%; CR5 ~50%), indicating meaningful scale effects but also space for focused specialists to compete via differentiation.
- Regulation and sustainability are structural disruptors. Environmental standards, single‑use packaging rules, and recycling infrastructure will alter design specifications and capital allocation for paper producers and converters.
Competitive landscape — who matters and why
The market combines global integrators, regional specialists, and nimble technical players. Understanding their strategic intent is essential when assessing partnership, supplier selection, or acquisition targets.
- Neenah Paper (Neenah, Wisconsin): A premium packaging and specialty paper manufacturer positioned on quality and brand reputation; attractive for partnerships where packaging differentiation is key.
- Pixelle Specialty Solutions (Spring Grove, Pennsylvania): Diverse specialty portfolio across labels and technical papers; its assets have been focal points for capacity consolidation and strategic buyers.
- UPM (Helsinki): Global integrator with capability in flexible packaging and industrial specialties — notable for R&D and product development that bridges fiber science and barrier performance.
- International Paper (Memphis): Large cellulose‑fiber platform that selectively prioritizes higher‑value specialty segments; recent operational closures evidence a shift toward rationalization and focus.
- Stora Enso (Helsinki): Leader in renewable materials and barrier‑coated solutions; recent product rollouts highlight a strategic emphasis on fiber‑based alternatives to plastic.
- Mondi (Vienna): Strong in industrial packaging grades and functional barrier lines, leveraging European manufacturing to serve adjacent export markets.
- Sappi (Johannesburg): Diversified specialty capabilities including technical grades and dissolving pulp linkages; an actor to watch in upstream fiber and product diversification plays.
- Ahlstrom (Kaukauna): Focused on fiber‑based specialty materials for filtration and food packaging; the company is actively expanding technical‑grade capacity through acquisitions.
- Burgo Group (Italy): Regional player with strengths in communication and packaging papers, useful as an entry/partner option in certain European corridors.
- Twin Rivers Paper (US): Pursuing growth via acquisition to scale specialty capability; demonstrates the strategic appetite for bolt‑on consolidation.
- Ivex Specialty Paper (US): Niche producer of crepe/kraft and technical grades — a reminder that specialized product portfolios remain attractive acquisition or partnership targets for larger players.
Recent industry moves and what they imply
- Acquisitions: Twin Rivers’ acquisition of Potsdam Specialty Paper (May 2026) and Ahlstrom’s purchase of a Pixelle mill (May 2026) underscore active consolidation aimed at technical capacity and geographic reach.
- Price actions: A March 2026 price increase announced by a major producer for kraft grades highlights the market’s ability to pass through input inflation under tight supply conditions.
- Product innovation and capacity adjustments: Recent launches of barrier‑coated fiber papers and ramp‑ups of functional barrier lines demonstrate how incumbents are competing on product differentiation rather than commodity volume alone.
- Plant rationalizations: Select mill closures and re‑tooling programs reflect a broader strategy to prioritize higher‑margin specialty lines and reduce exposure to low‑margin commodity segments.
How leaders should use this study in 2026
- Board & CEO: Use the report’s scenarios to test portfolio choices — product premiumization vs. scale — and to set capital allocation thresholds for new coating or recycling investments.
- M&A teams: Apply the market concentration maps and asset heatmaps to identify attractive bolt‑on targets, especially mills with upgrade potential for functional coatings or niche grades.
- Procurement: Reconfigure supplier strategies with options for long‑term pulp agreements, dual‑sourcing, and working capital mechanics to absorb episodic price shocks.
- R&D and Product: Prioritize barrier and performance upgrades that align with regulatory trends and end‑market requirements, leveraging partnerships with converters for faster adoption.
- Sustainability & Compliance: Integrate regulatory scenario outputs into product roadmaps to avoid stranded asset risk and to capture early‑mover advantage on fiber‑based plastic alternatives.
Methodology and confidence bounds
The report’s build integrates historical demand tracking (2020–2025), plant‑level capacity audits, primary interviews with producers and converters, pricing trend analysis, and a bottom‑up supply‑demand model. The base year is 2025 (USD Million revenue units), with forecasts covering 2026–2032 and a central CAGR assumption of 5.1% for that window. Market concentration indicators (CR3 and CR5) are included to quantify competitive dynamics and to support scenario stress‑testing for vertical integration and entry strategies.
We provide probabilistic scenarios to reflect key uncertainties: pulp price volatility, regulatory tightening, and selective capacity additions/closures. Sensitivity outputs show which investments are resilient across outcomes and which are contingent on a narrow set of assumptions.
Next steps — how to get the full intelligence
This preview outlines the strategic contours and commercial implications that matter for 2026 planning. The full Specialty Paper Market report contains the proprietary segmentation, regional splits, detailed company financials, downloadable datasets, and the interactive forecast model you’ll need to execute transactions or capital plans. For event‑driven deal teams, procurement directors, and product leaders, the report is designed to be operational the day it’s read: templates, checklists, and scenario tools are all included.
PW Consulting invites senior leaders and transaction teams to access the full study to obtain the granular tables, regional and application breakdowns, and plant‑level assessments that underpin the analyses summarized here. The preview demonstrates direction and strategic insight; the full report provides the numbers and supporting evidence you will use to act decisively in 2026.
For detailed analysis of this topic, please visit the official page: Specialty Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


